
Why Umbrella Insurance is Essential Financial Protection
Life can be unpredictable. A serious car accident, a guest injured at your home, or even a social media post gone wrong can lead to lawsuits that exceed your standard insurance limits. That’s where umbrella insurance becomes your financial safety net.
Umbrella insurance provides extra liability protection beyond your home and auto policies. For a surprisingly low annual cost, a $1 million umbrella policy can protect your assets, savings, and future earnings from devastating lawsuits. It also covers situations your regular insurance might miss, like libel, slander, and accidents that happen anywhere in the world.
The reality is simple: anyone with assets to protect—or future earnings to lose—needs this coverage. Whether you own a home, have teenage drivers, or simply want peace of mind, umbrella insurance is one of the most cost-effective ways to safeguard your financial future.
At Strange Insurance Agency, we’ve seen how the right umbrella policy can mean the difference between financial security and potential ruin. With over 15 years of experience, we’ve helped countless families find the best umbrella insurance solutions to protect their hard-earned assets when life’s unexpected storms hit.
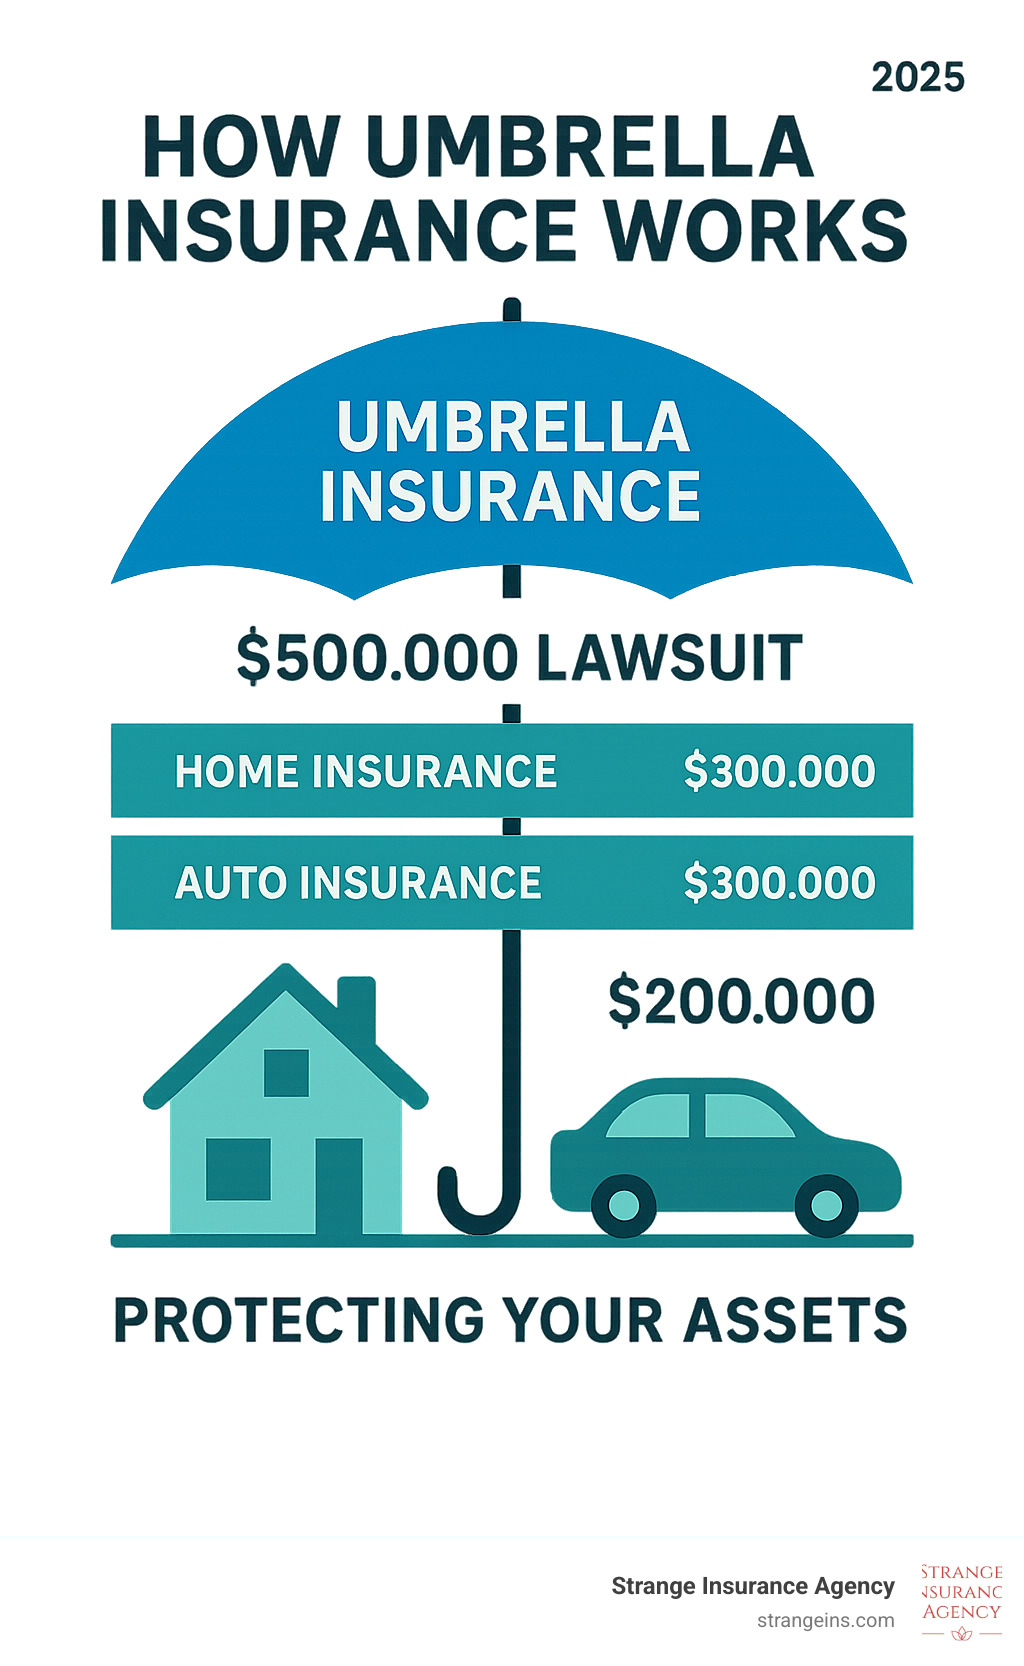
Handy best umbrella insurance terms:
What is Umbrella Insurance and How Does It Protect You?
Imagine you’re involved in a serious car accident, and the damages total $800,000. If your auto insurance only covers up to $300,000, you’re responsible for the remaining half-million dollars. Without umbrella insurance, that burden falls squarely on your shoulders.
Umbrella insurance is extra liability coverage that acts as a financial safety net above your existing home and auto policies. When a lawsuit or claim exceeds your primary insurance limits, your umbrella policy steps in to cover the difference, protecting your assets and future earnings. It’s called “umbrella” because it provides a broad layer of protection over your other policies.
But it isn’t just for massive accidents. It provides broad protection against personal liability claims from everyday activities, like your dog biting a neighbor, your teenager causing a multi-car pileup, or even a claim of online defamation.
For a deeper understanding, check out What Is Umbrella Liability Insurance and Umbrella insurance, explained.

What an Umbrella Policy Covers
When you’re looking for the best umbrella insurance, you’ll find the coverage is incredibly comprehensive. It typically includes:
- Bodily Injury Liability: Covers medical bills, lost wages, and pain-and-suffering damages for others if you’re at fault in an accident.
- Property Damage Liability: Protects you if you accidentally damage someone else’s property, like in a car accident.
- Landlord Liability: Offers protection from claims related to your rental properties, such as a tenant’s guest getting injured.
- Personal Injury Offenses: Covers claims like libel, slander, and defamation, which are increasingly common in the social media age.
- Legal Defense Costs: Pays for attorney fees and court costs to defend you against a lawsuit, even if it’s frivolous.
- Worldwide Coverage: Protects you no matter where an incident occurs, at home or abroad.
To explore the full range of protections, dive into Umbrella Policy What Does It Cover.
What an Umbrella Policy Excludes
While broad, umbrella insurance doesn’t cover everything. Key exclusions include:
- Your own injuries or property damage: Your health, auto, and homeowners insurance cover these.
- Intentional or criminal acts: Insurance protects against accidents, not deliberate harm.
- Business-related losses: You need separate Commercial Umbrella Insurance for business liability.
- Contractual liability: It won’t cover liabilities you voluntarily assume in a contract.
Umbrella vs. Excess Liability Insurance
While often confused, these two policies are different.
- Excess liability insurance simply increases the dollar limits of your existing policies. It offers more of the same coverage you already have.
- Umbrella insurance does that plus it fills coverage gaps. It provides broader coverage for risks your underlying policies may not cover, like slander or false arrest.
For most families, umbrella insurance is the more robust solution because it adds new layers of protection, not just higher limits. Learn more about Excess Liability Coverage.
Who Needs an Umbrella Policy and How Much Coverage is Enough?
Many people assume umbrella insurance is only for the wealthy, but the reality is that anyone who could face financial hardship from a major lawsuit should consider it. You don’t need to be a millionaire to be sued like one. A serious accident could result in a judgment that exceeds your standard policy limits, putting your current assets and future earnings at risk.
To determine your need, start with a simple risk and asset evaluation. Calculate your net worth (assets minus debts), but also consider your future earning potential. A court can garnish future wages to satisfy a large judgment. Our guide on How Much Umbrella Insurance Do I Need can walk you through the process.

High-Risk Situations That Call for Coverage
Certain everyday situations naturally increase your liability risk. Consider if you:
- Are a homeowner with a pool or trampoline.
- Are a dog owner.
- Are a parent of teen drivers.
- Are a landlord with rental properties.
- Frequently host parties or gatherings.
- Volunteer as a coach or serve on a board.
- Have a public profile that increases your risk of libel or slander claims.
Determining Your Ideal Coverage Amount
The goal is to balance protection with cost. Start by covering your net worth, including home equity, savings, and investments. Then, consider protecting your future earnings.
Typical policies start at $1 million. A $1 Million Umbrella Policy is a great starting point for many families. As your assets grow, you might consider a $5 Million Dollar Umbrella Policy or even a $10 Million Umbrella Policy. The cost for each additional million in coverage is surprisingly affordable, often just $50-$75 per year. We can help you calculate the right amount for your specific situation.
Finding the Best Umbrella Insurance: A Buyer’s Guide
Shopping for the best umbrella insurance isn’t just about finding the cheapest price. You need a policy from a financially stable company that provides excellent service and comprehensive coverage.
At Strange Insurance Agency, we simplify this process. We gather quotes from over 30 insurers, comparing not just price but the quality of coverage and service you’ll receive. This saves you time and ensures you find the right fit. Learn more about our approach in How to Find the Best Umbrella Insurance.

Key Factors for Choosing the Best Umbrella Insurance Provider
When evaluating providers, we focus on these critical factors:
- Financial Strength: Can the company pay large claims? We look for strong ratings from agencies like AM Best.
- Customer Satisfaction: How does the company treat its policyholders? We check independent reviews and data from organizations like the National Association of Insurance Commissioners (NAIC).
- Coverage Limits: Does the provider offer enough protection for your needs, from $1 million up to $100 million?
- Bundling Discounts: Can you save money by combining your umbrella policy with your home and auto insurance?
- Stand-Alone Options: Can you buy an umbrella policy even if your other insurance is with a different company?
For High-Net-Worth Families: Securing Your Legacy
If you have significant assets, a standard $1 million policy may not be enough. Wealth can make you a target for lawsuits, making higher liability limits essential. We work with high-net-worth families to secure coverage of $5 million, $10 million, or more to protect their assets, legacy, and even cover liabilities related to household staff. This type of Personal Excess Liability is critical for protecting everything you’ve built.
For the Savvy Bundler: Combining Policies for Savings
Bundling your umbrella policy with your Umbrella Homeowners Insurance and Umbrella Auto Policy is often the smartest move. You get the convenience of a single provider and can open up significant multi-policy discounts. Most insurers require you to have certain liability limits on your underlying policies (e.g., $250,000/$500,000 for auto, $300,000 for home) before they will issue an umbrella policy.
Can You Get a Stand-Alone Umbrella Policy?
Yes, a Standalone Umbrella Policy is an option if you want to keep your current home and auto insurer but get umbrella coverage elsewhere. While this offers flexibility, you’ll miss out on bundling discounts, and fewer companies offer this option. We can help you explore all possibilities, including Umbrella Insurance Without Auto policies, to find the right solution.
Understanding the Cost and Value of Umbrella Insurance
Many people worry about adding another insurance premium to their budget. But umbrella insurance offers extraordinary value for the protection it provides. For less than the cost of a daily coffee, you can protect millions of dollars in assets and future earnings from a single lawsuit that could otherwise be financially devastating.
The peace of mind alone is often worth the cost. It’s not just asset protection; it’s the freedom to live your life without the constant fear of financial ruin from an unexpected accident. To learn more, see if Are Umbrella Policies Worth It for you.

How Much Does an Umbrella Policy Cost?
The affordability of umbrella insurance surprises most people. A $1 million policy typically costs just $150 to $300 per year. That’s less than a dollar a day for a million dollars of liability protection.
The Cost Of Umbrella Policy is even more attractive as you add coverage. A second million in coverage might only add $75 annually, with each additional million costing around $50. Your specific premium will depend on your risk profile (e.g., teen drivers, a pool), location, and the number of properties and vehicles you own. Even so, it remains one of the best bargains in financial protection.
The Pros and Cons of Umbrella Insurance
Like any financial product, it’s important to weigh the pros and cons.
Pros:
- Massive protection for minimal cost.
- Shields both current assets and future earnings.
- Fills dangerous gaps in standard home and auto policies (e.g., libel, slander).
- Provides peace of mind and worldwide coverage.
- Covers expensive legal defense costs.
Cons:
- It is an additional expense in your budget.
- You must maintain higher liability limits on your underlying policies.
- It doesn’t cover your own property or injuries, only your liability to others.
- It excludes intentional acts and business activities.
For most families, the benefits overwhelmingly outweigh the minor drawbacks.
Frequently Asked Questions About Umbrella Insurance
We get a lot of questions about umbrella insurance. Here are the most common ones, with straightforward answers.
What’s the difference between umbrella and excess liability insurance?
Think of it this way: excess liability gives you more of the same coverage you already have by raising your policy limits. Umbrella insurance gives you broader coverage. It not only raises your limits but also covers claims your underlying policies might not, like libel or slander. For most people, an umbrella policy is the more comprehensive choice.
Do I still need umbrella insurance if I don’t have a high net worth?
Yes, absolutely. A major lawsuit can target your future earnings, not just your current assets. A court can garnish your wages for years to satisfy a judgment. An umbrella policy is an affordable way to protect your financial future, regardless of how much you have in the bank today.
How do I get a quote for the best umbrella insurance policy?
The smartest approach is to work with an independent insurance agency like ours. We gather quotes from over 30 different carriers to find the best fit for you. This saves you time and ensures you’re comparing policies that match your specific needs and budget, whether you have a pool in Virginia Beach or rental properties in North Carolina. You can start the process with a Personal Liability Umbrella Policy Quote today, and we’ll guide you every step of the way.
Conclusion: Your Shield Against Life’s Financial Storms
Life is unpredictable, and a single unexpected event—a car accident, an injury on your property, a misinterpreted social media post—can lead to a lawsuit that threatens your financial security. This is why the best umbrella insurance isn’t a luxury; it’s an essential shield for your family’s future.
For a remarkably affordable price, typically $150 to $300 per year for $1 million in coverage, an umbrella policy provides a critical layer of protection when your standard policies are not enough. It safeguards your home, your savings, and your future earnings from being wiped out by a catastrophic liability claim.
At Strange Insurance Agency, we provide a true concierge service to our clients across Virginia, North Carolina, West Virginia, and Florida. We shop over 30 top-rated companies for you, doing the heavy lifting to compare quotes and coverage options. Our goal is to find you comprehensive, custom protection at a competitive price, so you can have confidence and peace of mind.
Your financial future is too important to leave to chance. Don’t wait for the storm to hit. Take the next step to secure your financial future by exploring your personal insurance options today. We’re ready to help you steer insurance with confidence and ease.