
Why Building Insurance Quote Landlord Coverage Is Critical for Your Investment
A building insurance quote landlord policy protects your rental property from damage, liability, and lost income—coverage your standard homeowner’s policy doesn’t provide.
Key Coverage Areas:
- Property damage from fire, storms, vandalism, and other covered perils
- Liability protection for tenant and visitor injuries
- Loss of rental income when property becomes uninhabitable
- Landlord’s personal property like appliances and maintenance equipment
What’s NOT Covered:
- Tenant’s personal belongings (they need renters insurance)
- Normal wear and tear or maintenance issues
- Intentional damage by tenants
Cost Factors:
- Property location and condition
- Coverage limits and deductibles
- Number of units and property type
- Your claims history
Landlord insurance typically costs about 20% more than standard homeowner’s insurance—a small price for protecting your investment. As one industry expert noted: “The right coverage can make or break a rental property investment.”
Standard homeowner’s insurance won’t cover your rental property because it’s designed for owner-occupied homes, not businesses. The moment you start collecting rent, you’re running a business with different risks.
I’m Christian Strange. With over 15 years of experience, I help property owners steer insurance challenges. At Strange Insurance Agency, we secure comprehensive building insurance quote landlord coverage to protect your property and rental income.
Building insurance quote landlord terms explained:
What is Landlord Building Insurance?
Building insurance quote landlord coverage is a specialized shield for rental property investments. Unlike regular homeowner’s insurance, it’s designed for properties you rent to tenants. When you collect rent, you’re running a business, and this policy, also called rental property insurance or a dwelling fire policy, provides coverage that matches your actual risks.
Your rental property is a business asset that needs business-level protection under Commercial Lines Insurance. The increased risks of renting—from tenant accidents to property damage—require specialized coverage that understands the landlord-tenant relationship.
The Critical Difference: Landlord vs. Homeowner’s Insurance
Here’s the reality check: your homeowner’s insurance won’t cover your rental property. This fundamental mismatch could be a costly mistake.
Owner-occupied versus non-owner occupied properties face different risks. As a landlord, you rely on tenants to report issues, meaning a small problem like a leak could become a major one before you know it. These are business risks that require business insurance.
The liability differences are also striking. Personal liability covers a neighbor slipping on your icy sidewalk. Business liability covers you when a tenant’s guest sues you over an injury they claim was caused by your negligence. The legal exposure is completely different, and so is the insurance.
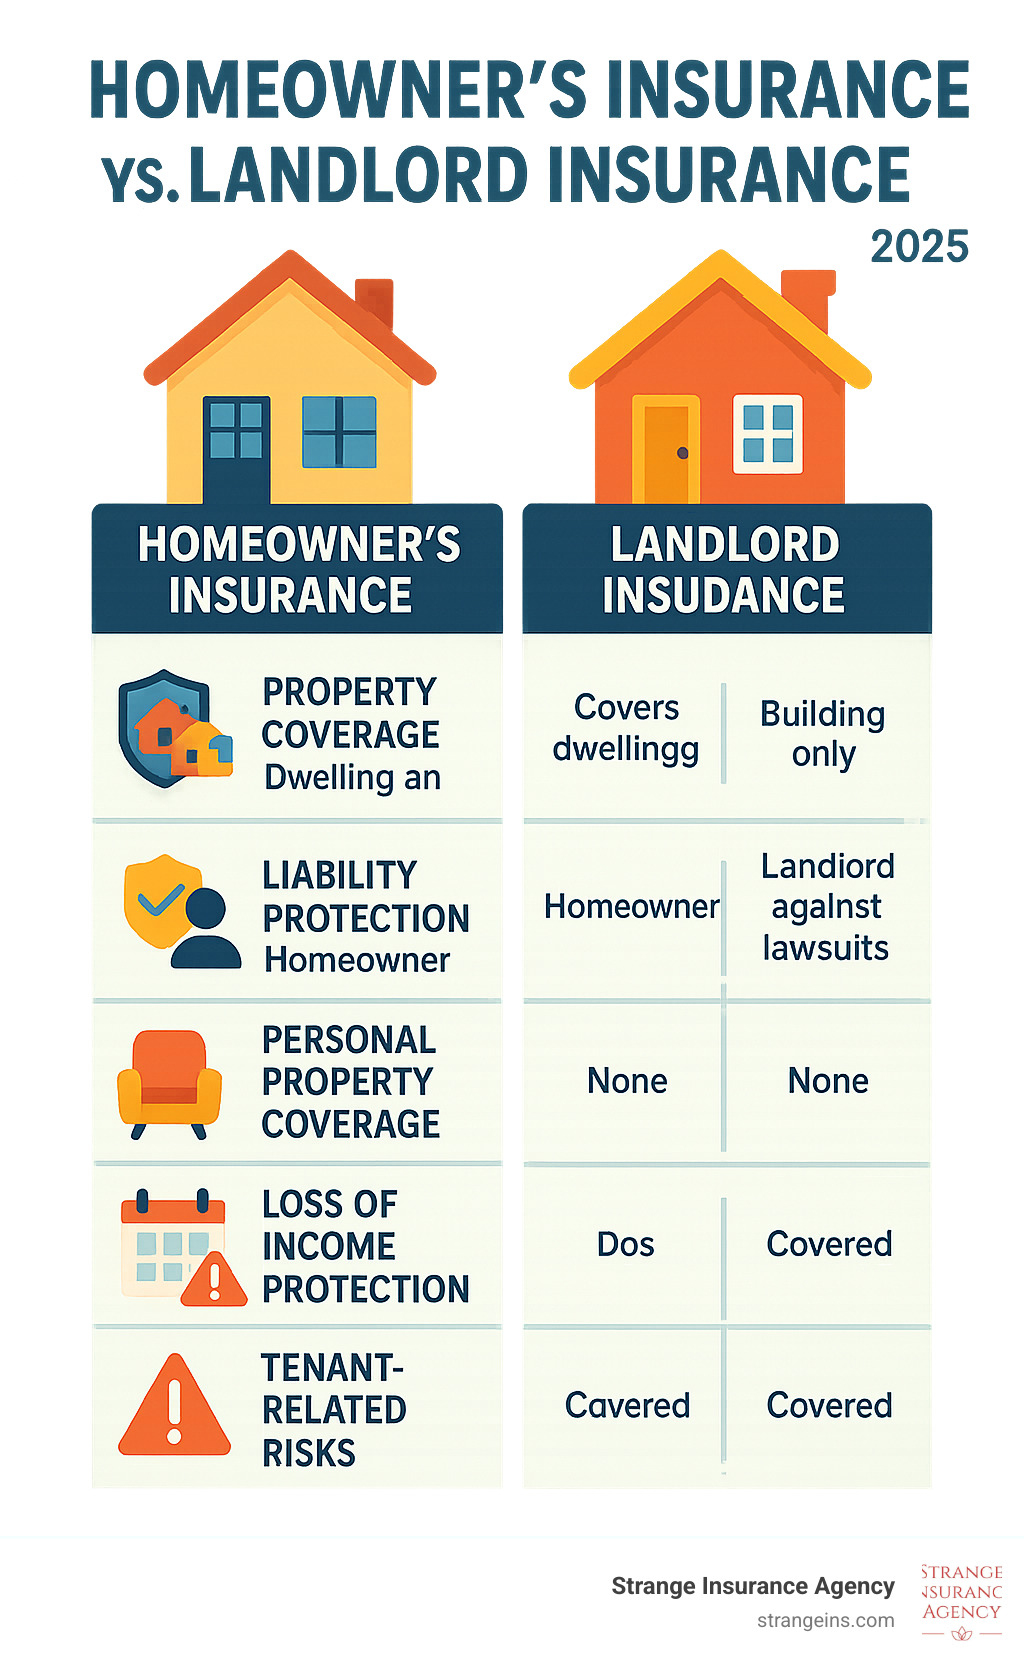
Here’s how the two types of coverage stack up:
| Coverage Area | Homeowner’s Insurance | Landlord Insurance |
|---|---|---|
| Property Coverage | Your dwelling and personal belongings | Rental dwelling and your landlord equipment |
| Liability | Personal activities and family | Business operations and tenant relations |
| Personal Property | Your furniture, clothes, electronics | Your appliances, tools, maintenance equipment |
| Loss of Income | Temporary living expenses if displaced | Lost rent when property is uninhabitable |
The bottom line is if you’re collecting rent, you need landlord insurance. We’ve helped countless property owners make this transition through our Homeowners Insurance Policy for Rental Property guidance.
Why Your Investment Property Needs Specialized Coverage
Your rental property is your financial future. Specialized landlord coverage protects both your property and your income, something no homeowner’s policy can do.
Protecting your rental income stream is a key benefit. When a fire or major leak makes your property uninhabitable, your mortgage and tax payments don’t stop, but your rental income does. Loss of rent coverage bridges this gap, replacing your income while repairs are made. A four-month repair on a $2,000/month rental means $8,000 in lost income on top of repair costs.
Liability protection for tenants and guests is essential. As a landlord, you’re responsible for maintaining safe conditions. If someone is hurt and claims it’s due to your negligence, this coverage handles the legal and financial fallout.
Mortgage lender requirements often mandate this coverage. Most lenders require adequate insurance on investment properties to protect their loan.
Specialized coverage provides peace of mind, allowing you to focus on Insuring Investment Property and growing your Real Estate Business portfolio. Building insurance quote landlord coverage isn’t an expense—it’s an investment in your investment’s future.
Decoding Your Landlord Insurance Policy: What’s Covered (and What’s Not)
Understanding your building insurance quote landlord policy is crucial for protecting your investment. Think of it as learning the rules of the game.
Most landlord policies cover either “named perils” (specific disasters listed in your policy) or operate on an “all-risk” basis (covering everything except what’s specifically excluded). Knowing which type you have is key to ensuring you have the Best Building Insurance for Landlords for your situation.
Core Protections for Your Property and Assets

A solid building insurance quote landlord policy shields you from the most common and costly risks.
Dwelling protection is the backbone of your coverage, protecting the physical structure of your rental property—foundation, roof, walls, and permanent fixtures. It covers disasters like fire, lightning, windstorms, or hail.
Your policy also extends to other structures on your property, such as a detached garage, storage shed, or fence.
Landlord’s personal property coverage protects items you keep on the property for maintenance or tenant use, like appliances, tools, or carpeting. This doesn’t cover your tenant’s belongings; they need their own renters insurance.
Liability Coverage for Rental Property is perhaps the most critical protection. As a property owner, you’re responsible for maintaining a safe environment. If someone is injured on your property and claims it’s your fault, this coverage handles legal fees, medical costs, and potential settlements.
Finally, loss of rent coverage (or fair rental value) protects your income. When a covered disaster makes your property uninhabitable, this coverage replaces that lost income while repairs are made, ensuring you can still meet your financial obligations.
Common Exclusions and Optional Add-Ons
No insurance policy covers everything. Understanding common exclusions helps you identify gaps in your coverage.
Your policy won’t cover tenant’s personal belongings, normal wear and tear, or maintenance issues from neglect. Intentional damage by tenants is also typically excluded from standard policies. Disasters like flood damage from rising water and earthquake damage usually require separate policies. Pest infestations are considered a maintenance issue and are not covered.
You can often add coverage for these gaps. Optional add-ons may include:
- Vandalism and malicious mischief coverage for intentional damage.
- Equipment breakdown coverage for HVAC systems or water heaters.
- Sewer backup coverage, a lifesaver in areas with aging systems.
Some landlords also add Landlord Umbrella Insurance for extra liability protection or Business Flood Insurance Quote in flood-prone areas. An experienced agent can help you identify which optional coverages are right for your property.
How to Get the Best Building Insurance Quote Landlord
Getting the right building insurance quote landlord coverage means finding comprehensive protection at a fair price. The key is understanding what drives your costs and how to compare policies effectively.
At Strange Insurance Agency, we help landlords across Virginia, North Carolina, and beyond steer this process. We simplify it by comparing options from over 30 carriers, helping you make informed decisions about your Buy to Let Buildings Insurance Quotes. We translate the insurance jargon and show you exactly what you’re getting for your money.
Factors That Influence Your Premium

Understanding the factors that influence your premium helps you anticipate costs and find savings.
- Location: A property in a high-risk area for hurricanes, floods, or crime will cost more to insure.
- Property’s age and condition: A newly renovated property with updated electrical, plumbing, and roofing signals lower risk than an older, un-renovated one.
- Construction materials: A brick home is typically less expensive to insure than a wood-frame one because it’s more resistant to fire and wind.
- Claims history: A clean claims record can help you qualify for better rates, while multiple recent claims will increase your premium.
- Coverage limits and deductible: Higher coverage limits increase premiums, while a larger deductible (the amount you pay out-of-pocket) can lower your costs.
We consider all these elements when securing your Investment Property Insurance to help you make smart decisions.
Tips for Finding a Cheap building insurance quote landlord
“Cheap” shouldn’t mean “inadequate.” The goal is comprehensive coverage at the best price. Here are proven strategies to reduce your premiums.
- Bundle policies: Combining your landlord insurance with your personal home and auto policies often leads to significant multi-policy discounts.
- Increase your deductible: Raising your deductible from $500 to $2,500 could cut your premium significantly. Just ensure you can afford the higher out-of-pocket cost.
- Install safety features: Modern smoke detectors, security systems, and smart water leak detectors can qualify you for discounts by preventing claims.
- Maintain your property: Regular roof inspections, HVAC servicing, and plumbing updates show insurers you’re a responsible owner, which can lead to better rates. This is key for House Insurance for Buy to Let properties.
- Comparison shop: Rates vary significantly between carriers. We handle the time-consuming process of gathering and comparing multiple building insurance quote landlord options from our network of over 30 carriers. This comprehensive approach helps you find Cheap Buy to Let Building Insurance without sacrificing protection.
The Landlord-Tenant Dynamic: Insurance Responsibilities
Insurance plays a vital role in the landlord-tenant relationship, defining responsibilities and mitigating risks. Clear communication and a solid lease agreement are paramount for managing this dynamic and your Real Estate Property Management Insurance.
Common Claims Scenarios for Landlords
Understanding common claims can help you appreciate your policy’s value and take preventive steps.
- Tenant or visitor injury (slip and fall): A common liability claim. If a guest is injured due to a property hazard (e.g., icy walkway, loose stair), your liability coverage helps with medical and legal costs.
- Fire or water damage: An accidental kitchen fire or a burst pipe can cause major structural damage. Your dwelling protection covers repairs, and loss of rent coverage replaces lost income.
- Weather-related damage: Wind, hail, or falling trees can damage your roof and siding. These perils are typically covered by dwelling protection.
- Sewer backup: A municipal sewer backup can flood your property with contaminated water. This usually requires an optional coverage add-on.
- Vandalism: Damage by unknown third parties, like graffiti or broken windows, can be covered. Coverage for tenant vandalism may require a special endorsement.
Why You Should Require Tenants to Have Renters Insurance
Your landlord policy protects your property, not your tenant’s. Requiring tenants to carry renters insurance is a smart move for everyone.
- Covers tenant’s belongings: It ensures tenants can replace their personal property after a covered event like a fire or theft.
- Provides tenant liability: If a tenant accidentally damages your property (e.g., an overflowing tub), their policy can cover the costs.
- Reduces landlord’s risk: It gives tenants a direct path to compensation for their losses, reducing the chance they’ll look to you for reimbursement.
- May cover landlord’s deductible: If a tenant is responsible for damage, their policy might cover your policy’s deductible.
- Peace of mind: Knowing both parties are protected creates a more secure rental experience.
Frequently Asked Questions about Getting a Building Insurance Quote Landlord
Here are answers to the most common questions we receive about building insurance quote landlord coverage.
Does landlord insurance cover damage caused by a tenant?
It depends on whether the damage was accidental or intentional.
Accidental damage, like a small kitchen fire or a cracked window from a thrown toy, is typically covered under your building insurance quote landlord policy as a standard peril.
Intentional damage or vandalism by a tenant, such as punched holes in walls, is usually not covered by a standard policy. However, many insurers offer a “malicious damage by tenant” endorsement you can add for extra protection.
The key is to review your policy’s exclusions. Ask your agent to clarify what tenant-related damage is covered.
Is landlord insurance a legal requirement?
Landlord insurance isn’t legally mandated in most states, including Virginia and North Carolina.
However, it’s often required by mortgage lenders. If you have a loan on your rental property, your lender will almost certainly require proof of landlord insurance to protect their investment. Failing to have it could put you in breach of your mortgage contract.
Beyond any requirements, think of it as essential business protection. The potential cost of a single fire or lawsuit can be financially devastating. Your building insurance quote landlord policy is your financial safety net.
Can I use my homeowner’s insurance for a short-term rental?
The answer is almost always no.
Standard homeowner’s policies exclude business activity, and renting your home—even for short periods—is a business. Once you collect payment from guests, you’ve entered commercial territory.
Short-term rentals face unique risks from high guest turnover that require specialized short-term rental insurance or commercial property coverage. Don’t risk having a claim denied for using the wrong policy. We can help you find the right coverage that actually protects your short-term rental business.
Conclusion
Congratulations! You now have the knowledge to protect your rental property investment. Building insurance quote landlord coverage isn’t just an expense—it’s the financial safety net that keeps your investment dreams alive.
You’ve worked hard to build your rental portfolio. The right insurance protects that hard work from being derailed by an unexpected event.
The key takeaways are clear: you need dwelling protection for the structure, liability coverage for injuries, and loss of rent coverage to maintain cash flow. Requiring tenants to have renters insurance adds another layer of security for everyone.
At Strange Insurance Agency, we’ve spent over 15 years helping property owners like you steer the insurance market. We serve landlords across Virginia, North Carolina, West Virginia, and Florida with the personal touch of a local agency and the power of a national network.
We act as your concierge insurance agency, comparing quotes from over 30 leading carriers to find the best coverage at the right price. We take the time to understand your unique needs because protecting your investment shouldn’t be complicated.
Don’t leave your valuable rental property exposed. Your future self will thank you for taking this crucial step today.
Get a quote for your Commercial Property Insurance and let us help you secure the peace of mind that comes with knowing your investment is properly protected.