
Why Virginia Small Businesses Need Liability Insurance Protection
Business liability insurance Virginia is essential protection for the nearly 800,000 small businesses operating in the Old Dominion State. Without proper coverage, a single lawsuit from a customer injury, property damage claim, or advertising dispute can lead to financial ruin and threaten your personal assets.
Quick Answer: Business Liability Insurance Virginia Essentials
- What it is: Commercial General Liability (CGL) insurance that protects against third-party claims
- Average cost: $43 per month or $516 annually for Virginia small businesses
- Coverage includes: Bodily injury, property damage, personal/advertising injury, and legal defense
- Required by law: No, but often required by clients, landlords, and licensing boards
- Recommended coverage: $500,000 to $1 million for most small businesses
Virginia’s unique contributory negligence standard means that even if a plaintiff shares some fault, your business could still face significant liability. This legal landscape makes comprehensive liability coverage even more critical for protecting your business investment.
Whether you’re running a restaurant in Richmond, a consulting firm in Arlington, or a retail store in Virginia Beach, understanding your liability insurance options helps you make informed decisions about protecting your business from unexpected legal claims and settlements.
I’m Christian Strange, and with over 15 years of experience in treasury management, business consulting, and insurance, I help Virginia businesses steer business liability insurance Virginia requirements and find comprehensive coverage that fits their unique needs. Through my work, I’ve seen how proper liability protection can be the difference between a minor setback and a business-ending catastrophe.
Common business liability insurance Virginia vocab:
What is Business Liability Insurance and What Does It Cover?
Think of business liability insurance Virginia as your business’s financial bodyguard. Officially called Commercial General Liability (CGL) insurance, this coverage stands between your business and the unexpected lawsuits that can pop up during everyday operations.
Here’s what makes this insurance so important: it protects you from “third-party” claims. These are lawsuits filed by customers, clients, vendors, or anyone else who isn’t your employee. When someone gets hurt on your property or claims your business damaged their stuff, CGL insurance steps in to handle the financial fallout.
Without this protection, even a minor incident can snowball into a major financial crisis. One slip-and-fall accident or property damage claim could drain your business savings and put your personal assets at risk.

Core Coverages of Business Liability Insurance in Virginia
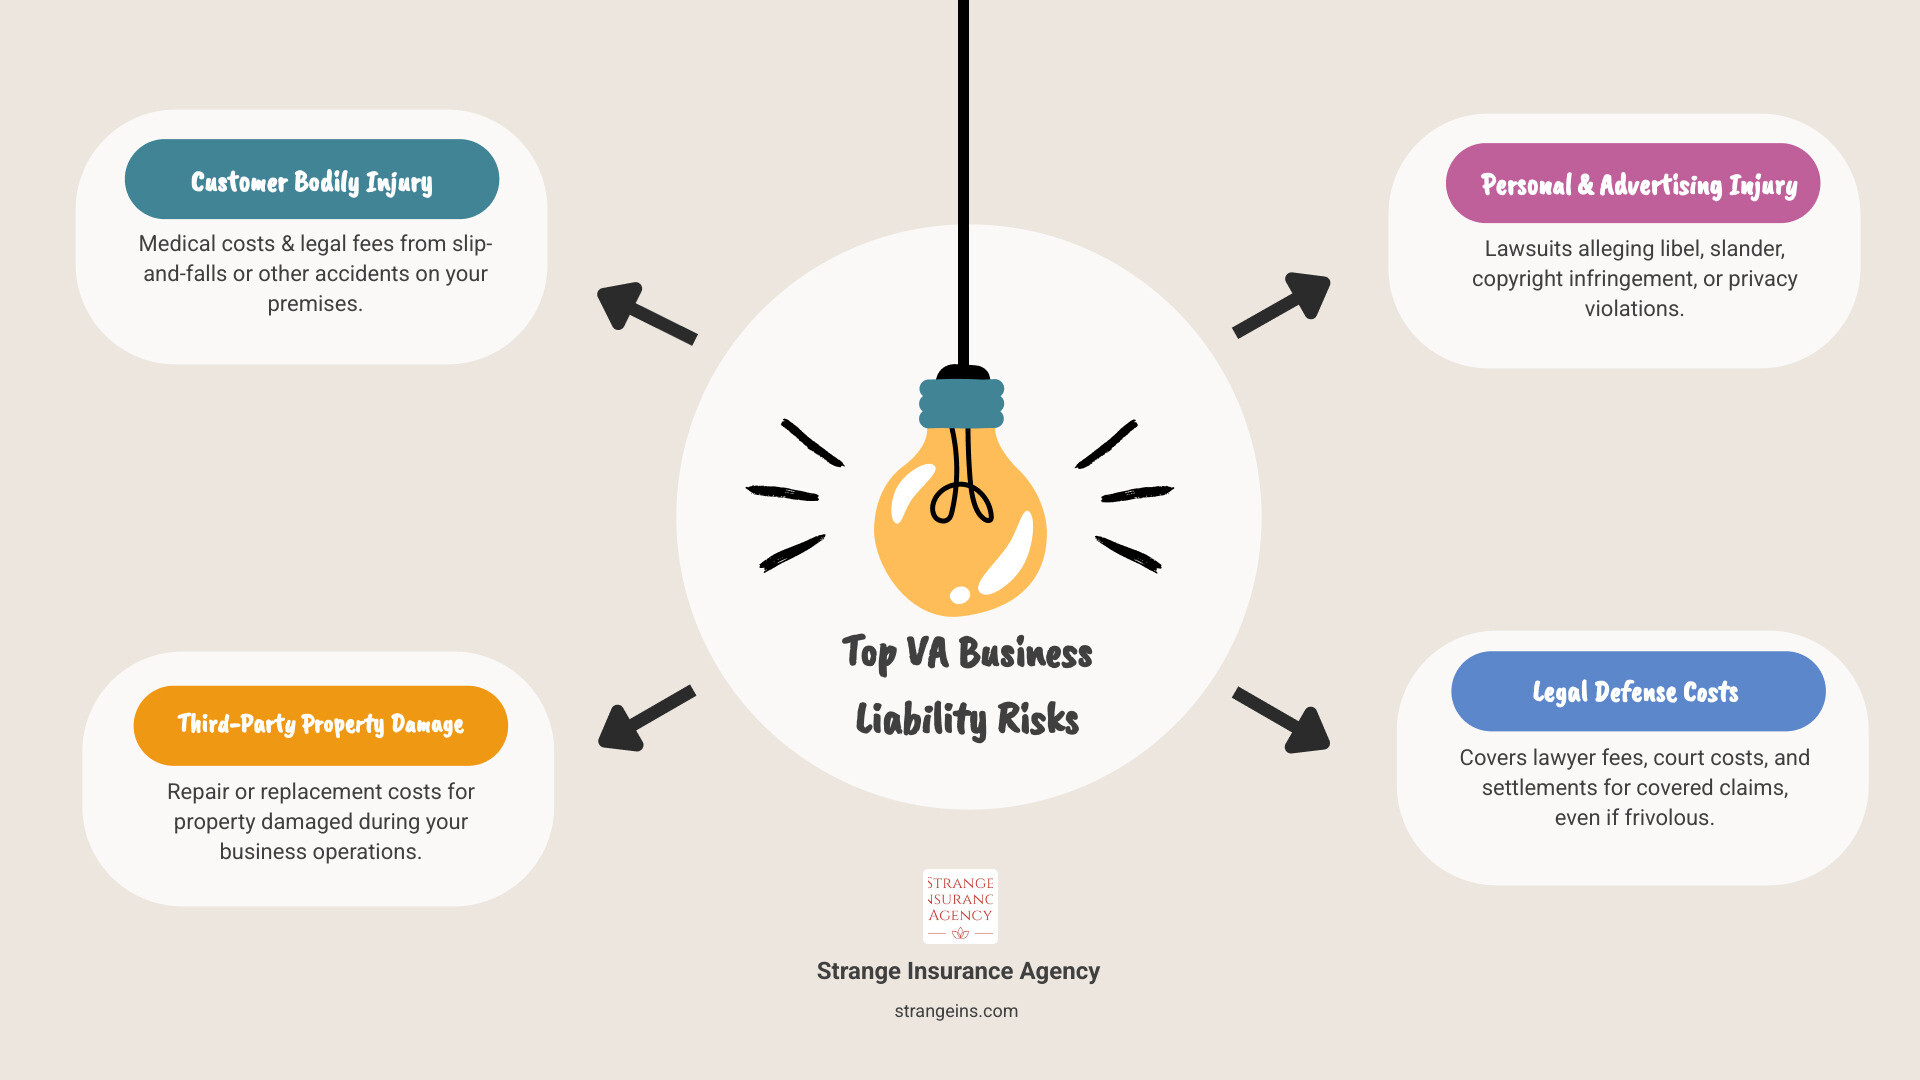
Your business liability insurance Virginia policy covers four main areas that protect your business from different types of claims:
Bodily Injury coverage kicks in when someone gets physically hurt because of your business. Picture this: a customer slips on a wet floor in your Richmond store and breaks their wrist. Your policy covers their medical expenses, lost wages, and any legal fees if they decide to sue. This coverage also applies to injuries caused by your products or services, not just accidents on your premises.
Property Damage protection handles the costs when your business operations accidentally damage someone else’s property. Let’s say you’re a contractor working in Virginia Beach, and your employee accidentally puts a hole in the client’s expensive drywall. Your liability insurance covers the repair or replacement costs, saving your business from paying out of pocket.
Personal & Advertising Injury coverage protects against claims that don’t involve physical harm but can still hurt your business financially. This includes lawsuits over libel, slander, or copyright infringement. With social media being such a big part of business today, even an innocent post could lead to a lawsuit. If someone claims your business defamed them or used their copyrighted material without permission, this coverage handles the legal costs.
Legal Defense & Judgments might be the most valuable part of your policy. Even if you win a lawsuit, the legal costs can be crushing. Lawyer fees, court costs, and settlement negotiations add up quickly. Your business liability insurance Virginia policy covers these expenses regardless of whether you’re found liable, protecting your business from the high cost of defending itself in court.
Is Liability Insurance Mandatory in Virginia? (And Other Requirements)
Here’s a question I get asked almost daily: Is business liability insurance Virginia required by state law? The short answer is no – Virginia doesn’t typically require all businesses to carry commercial general liability insurance as a blanket rule.
But here’s the thing: just because it’s not legally mandatory doesn’t mean you can skip it. In my experience helping Virginia business owners, most find they need liability coverage anyway due to practical business requirements.
Your clients often demand it before they’ll work with you. I’ve seen countless contractors, consultants, and service providers lose out on lucrative contracts simply because they couldn’t provide a certificate of insurance. Government contracts and larger corporations almost always require proof of liability coverage.
Commercial landlords are another story entirely. Most lease agreements in Virginia include clauses requiring tenants to carry specific liability coverage limits. Your landlord wants protection if something happens on their property due to your business operations.
Professional licensing boards may also require liability insurance to obtain or maintain your license. This varies by industry, but it’s worth checking with your specific board or association.
Virginia’s legal landscape adds another layer of complexity. The state follows a contributory negligence standard, which means if an injured party is found even 1% at fault for their injury, they may be barred from recovering damages. While this can work in your favor, it doesn’t prevent lawsuits from being filed or eliminate your legal defense costs.
The reality is that defending against any claim – even a frivolous one – can cost thousands in legal fees. That’s where having proper coverage becomes invaluable.

Mandatory Insurance for Virginia Businesses
While business liability insurance Virginia isn’t universally required, there are two types of coverage that Virginia law absolutely mandates for many businesses.
Workers’ Compensation Insurance is non-negotiable if you have employees. Virginia’s three or more employees rule means any business with three or more regular employees – whether they’re part-time or full-time – must carry workers’ compensation coverage. This insurance covers employee medical bills and lost wages if they’re injured on the job, while also protecting your business from employee injury lawsuits.
Even if you’re just starting out, keep this threshold in mind as you grow. The moment you hire your third employee, you’ll need coverage. Sole proprietors without employees are exempt, but the rules can be tricky. For complete details, check the Virginia Workers’ Compensation Commission website.
Commercial Auto Insurance becomes mandatory when your business owns, leases, or regularly uses vehicles for business purposes. Here’s something many business owners don’t realize: your personal auto policy will almost certainly exclude accidents that happen while you’re using your vehicle for business.
Virginia’s financial responsibility requirements for business vehicles currently require $30,000 bodily injury liability per person, $60,000 bodily injury liability per accident, and $20,000 property damage liability per accident. These limits are increasing in January 2025 to $50,000 per person, $100,000 per accident, and $25,000 for property damage.
You can find all the current requirements and upcoming changes on Virginia’s minimum requirements page from the DMV.
Your Guide to Business Liability Insurance Virginia Costs & Premiums
When Virginia business owners ask about business liability insurance Virginia costs, they’re often pleasantly surprised by how affordable this crucial protection can be. The average small business in Virginia pays around $43 per month for general liability insurance – that’s about $516 annually. For most businesses, that’s less than what you’d spend on a decent coffee habit!
Of course, your actual premium won’t be exactly $43. Every business is unique, and insurance companies assess your specific risk factors when determining your rate. We believe in complete transparency about insurance costs, which is why we help you compare comprehensive Business Insurance options that fit both your budget and your protection needs.

How Premiums Are Calculated
Think of insurance underwriting like a risk assessment report card for your business. Insurance companies look at multiple factors to determine how likely your business is to file a claim, then price your premium accordingly.
Your industry and risk level plays the biggest role in your premium. A construction company working on rooftops faces very different risks than a consulting firm working from a home office. Building trades, restaurants, and retail stores typically see higher premiums because they have more opportunities for accidents and customer interactions.
Business location and foot traffic also matter. A busy storefront in downtown Richmond will generally cost more to insure than a quiet office in a suburban business park. More people coming and going means more chances for slip-and-fall incidents or other accidents.
The number of employees on your payroll directly affects your premium calculation. More team members mean more exposure to potential liability situations, whether they’re interacting with customers or working on client projects.
Your annual revenue and payroll give insurers a sense of your business size and scope. Higher revenue often indicates larger operations with more moving parts, which can translate to increased risk exposure.
Claims history is like your business’s driving record – a clean history keeps your rates lower, while previous claims can bump up your premium. If you’ve never filed a liability claim, that works in your favor.
Finally, your coverage limits and deductibles directly impact your premium. Higher coverage limits mean you’ll pay more, while choosing a higher deductible (the amount you pay before insurance kicks in) can lower your monthly cost.
How Much Coverage Do You Need?
Here’s where the rubber meets the road: determining the right amount of business liability insurance Virginia coverage for your specific situation. Most small businesses do well with coverage between $500,000 and $1 million. This range provides solid protection against the majority of liability claims without breaking the bank.
However, if you’re in a high-risk industry, you’ll want to lean toward the higher end of that range or even beyond it. Building trades face significant exposure from job site accidents and property damage. Restaurants deal with food-related illnesses, spills, and burns. Retail stores see constant foot traffic and product liability concerns.
The key is finding that sweet spot where you have enough coverage to protect your business assets and give you peace of mind, without paying for more insurance than you realistically need. This isn’t just about protecting your business – it’s about protecting the personal assets and financial future you’ve worked so hard to build.
Beyond the Basics: Other Insurance Virginia Businesses Should Consider
While business liability insurance Virginia forms the foundation of your protection, truly comprehensive coverage requires thinking beyond the basics. It’s like building layers of security around your business – each type of insurance addresses different risks that could threaten your operations and financial stability.
Think of it this way: general liability protects you from accidents and injuries, but what happens if you make a professional mistake? Or if hackers steal your customer data? These scenarios require specialized coverage that goes beyond standard liability insurance.

We help you explore all your options for Virginia Small Business Insurance to create a safety net that truly protects your hard work and investment.
Professional Liability (Errors & Omissions)
If your Virginia business provides professional services or advice, Professional Liability insurance (also called Errors & Omissions or E&O) isn’t just helpful – it’s essential. This coverage fills a critical gap that general liability doesn’t address: mistakes in your professional work.
Service-based businesses like consultants, accountants, and real estate agents face unique risks every day. Unlike a slip-and-fall accident, professional mistakes can be subtle but financially devastating. E&O insurance protects you when clients claim your negligence led to their financial loss, when you miss important deadlines, or when they argue your advice caused them harm.
Picture this: an accountant in Virginia Beach makes a calculation error that costs a client thousands in tax penalties. Or a consultant’s recommendation leads to a business decision that backfires. These situations don’t involve physical injury or property damage, but they can result in expensive lawsuits that general liability won’t cover.
Professional liability insurance steps in to handle legal defense costs, settlements, and judgments related to your professional services. For more detailed information, check out our More info about professional liability services page.
Cyber Liability Insurance
Here’s a sobering fact: Hackers are three times more likely to target small businesses than large corporations. Why? Small businesses often lack the sophisticated cybersecurity defenses that bigger companies have, making them easier targets.
Data breaches and cyberattacks aren’t just tech company problems anymore. Any Virginia business that stores customer information, processes payments, or operates online faces cyber risks. And when a breach happens, the costs add up quickly.
Virginia’s data breach laws require businesses to notify affected customers, which means you’ll need to pay for customer notification costs and credit monitoring services. Beyond legal requirements, you might face lawsuits, need public relations help to protect your reputation, and require expert assistance to secure your systems.
Cyber liability insurance covers these expenses, helping your business survive what could otherwise be a financially crippling event. Whether you’re a small retailer in Richmond or a professional services firm in Northern Virginia, cyber coverage has become essential protection in today’s digital world.
Business Owner’s Policy (BOP)
For many small to medium-sized Virginia businesses, a Business Owner’s Policy offers the perfect balance of comprehensive coverage and cost-effectiveness. Think of a BOP as a streamlined bundle that combines your two most important coverages into one convenient package.
This cost-effective bundle includes General Liability insurance (protecting against third-party claims) and Commercial Property insurance (protecting your building, equipment, inventory, and furniture from perils like fire, theft, and vandalism).
The beauty of a BOP lies in its simplicity and savings. Instead of juggling separate policies with different renewal dates and coverage terms, you get comprehensive protection in one package. Plus, bundling typically costs less than buying the coverages separately – a win-win for budget-conscious business owners.
BOPs work especially well for businesses with standard operations and moderate risk levels. If you’re running a retail store, restaurant, or professional office in Virginia, a BOP might be exactly what you need to protect your investment without overcomplicating your insurance program.
Virginia Insurance Regulations and Helpful Resources
Understanding business liability insurance Virginia requirements becomes much easier when you know where to find reliable information. The Commonwealth of Virginia has established clear regulatory oversight through the State Corporation Commission (SCC) and its Bureau of Insurance, which work tirelessly to protect consumers and ensure insurance companies operate fairly.
These regulatory bodies aren’t just there to oversee the industry – they’re genuinely committed to helping business owners like you make informed decisions about your insurance needs. Whether you’re trying to understand coverage requirements, compare policies, or resolve disputes, they provide valuable resources and guidance.
The Bureau of Insurance serves as your advocate in the insurance marketplace, ensuring that companies follow state regulations and treat customers fairly. They also maintain extensive educational materials specifically designed to help Virginia entrepreneurs steer the sometimes complex world of commercial insurance. You can access these resources and learn more by visiting the Virginia Bureau of Insurance.
Official Resources for Virginia Entrepreneurs
Virginia offers an impressive network of official resources designed to support small business owners in making smart insurance decisions. The Virginia SCC Commercial Insurance Guide provides comprehensive information about various types of commercial coverage, including liability insurance, and explains how these policies work within Virginia’s regulatory framework. This guide is particularly helpful for understanding state-specific requirements and regulations.
For broader business support beyond insurance, the Virginia Small Business Development Center offers invaluable counseling, training, and resources to help small businesses start, grow, and thrive throughout the Commonwealth. Their experienced counselors can help you understand how insurance fits into your overall business strategy and risk management plan.
The U.S. Small Business Administration Virginia District provides federal-level programs and services to help small businesses succeed. They offer information on funding, counseling, and government contracting opportunities, and can guide you toward insurance resources that align with federal requirements if your business works with government contracts.
Finally, the Insurance Information Institute (III) serves as an excellent educational resource. This non-profit organization is dedicated to improving public understanding of insurance and provides clear, unbiased information about different types of coverage, industry trends, and best practices for business owners.
We regularly refer our clients to these official resources because we believe informed business owners make better insurance decisions. These organizations complement our personalized service by providing the regulatory context and educational foundation that helps you understand not just what coverage you need, but why you need it.
Conclusion
Securing the right business liability insurance Virginia is far more than checking a box on your business to-do list. It’s one of the smartest investments you can make in protecting everything you’ve worked so hard to build. In Virginia, where our unique contributory negligence laws can create unexpected legal challenges, having comprehensive coverage isn’t just wise—it’s essential for your peace of mind.
Think about it this way: you wouldn’t drive your car without insurance, so why would you operate your business without proper protection? The right liability coverage acts as a financial safety net, allowing you to focus on what you do best—growing your business and serving your customers—without constantly worrying about what could go wrong.
We get it. We understand that navigating insurance options can feel overwhelming, especially when you’re already juggling the countless responsibilities of running a business. That’s exactly why we created our concierge service approach. We don’t just sell you a policy and disappear. Instead, we work as your dedicated insurance partner, taking the time to understand your unique needs and challenges.
Our process is refreshingly straightforward. We compare quotes from multiple top-rated insurance companies, ensuring you get comprehensive coverage that actually fits your budget and business requirements. No cookie-cutter solutions or pushy sales tactics—just honest advice and efficient service that respects your time.
Whether you’re a consultant in Arlington, a restaurant owner in Virginia Beach, or a contractor in Richmond, we’ve helped hundreds of Virginia businesses find the right protection. Don’t leave your hard work vulnerable to a single lawsuit or unexpected claim that could change everything.
Ready to protect what you’ve built? Get a comprehensive business insurance consultation today, and let’s find the coverage that gives you the confidence to focus on growing your business.