
Why Esthetician Liability Insurance is Your Business’s Best Friend
What is esthetician liability insurance? It’s crucial protection for your esthetics business that covers legal costs from client injury or negligence claims, protects your business from financial losses, and offers peace of mind.
Every esthetician performs delicate procedures with inherent risks. Even with the best training, a client could have an unexpected reaction, a slip-and-fall, or claim property damage. Defending against a claim can be incredibly expensive—the average spa industry claim is $5,500, and legal fees can quickly exceed that.
This guide will explain what esthetician liability insurance is, why it’s vital, and how to choose the best policy.
As Christian Strange, with over 15 years in risk mitigation and insurance, I’ve seen how essential this coverage is for protecting your livelihood. My expertise helps estheticians like you find the right policy, ensuring peace of mind.
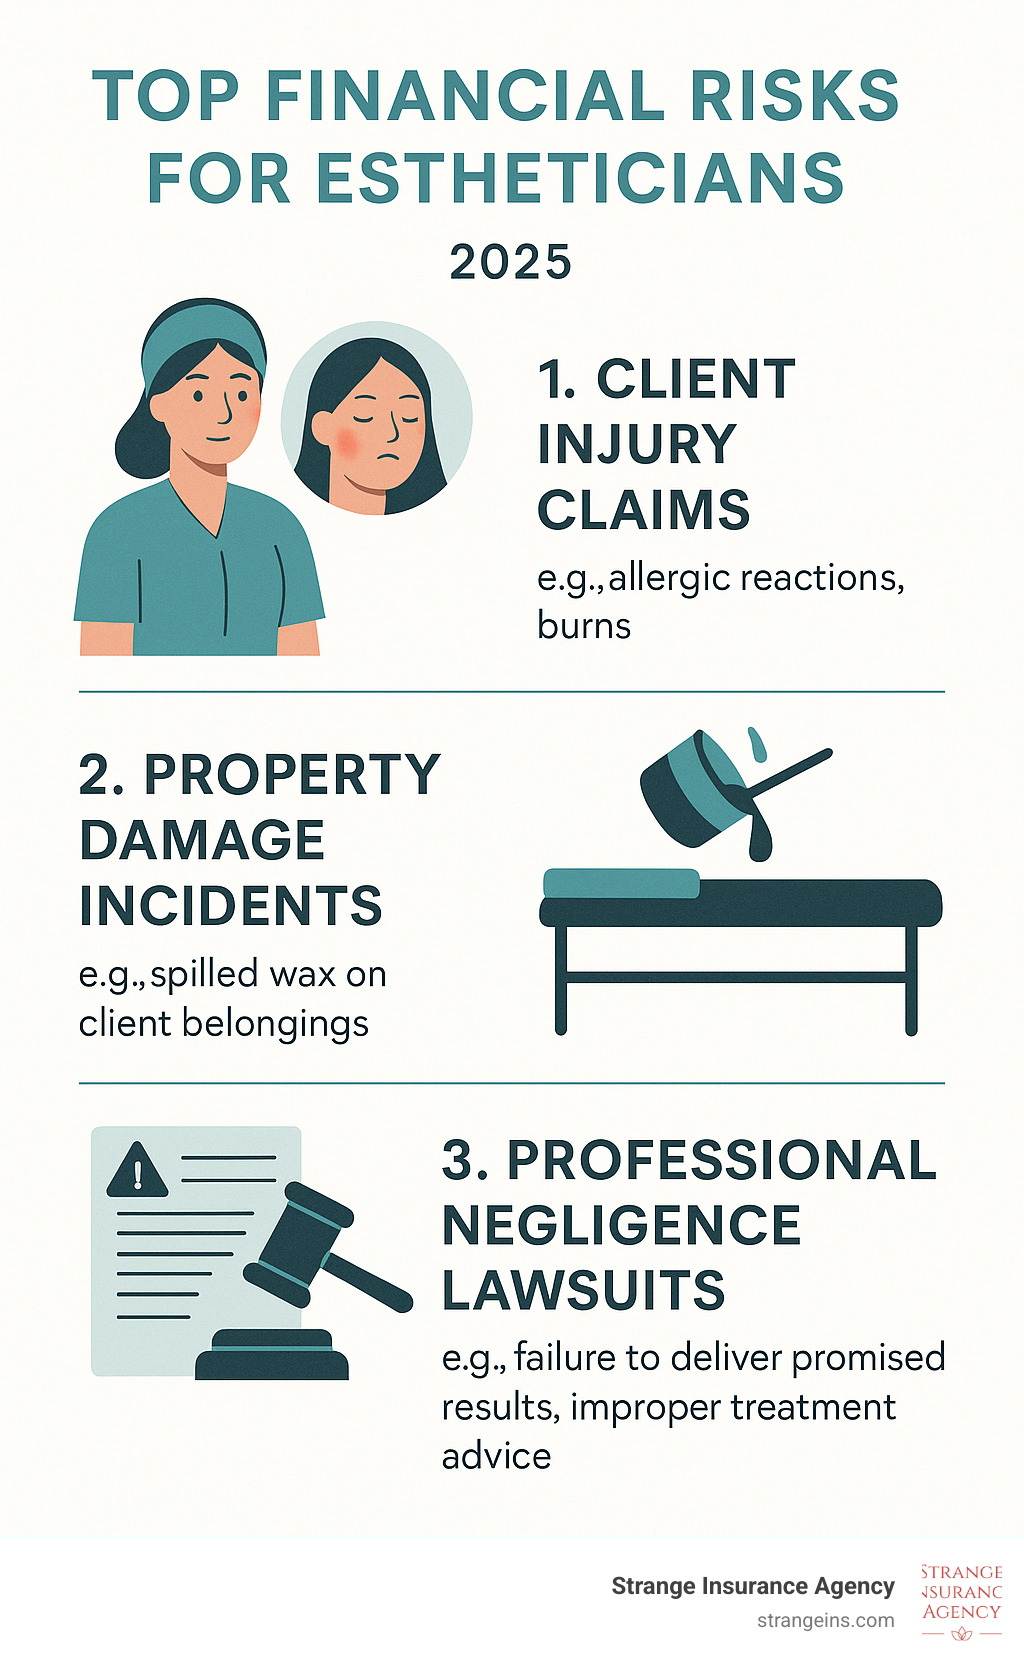
Key terms for esthetician liability insurance:
What is Esthetician Insurance and Why Is It Essential?
Imagine a client slips near your workstation, or claims a chemical peel caused an unexpected reaction. These incidents can escalate into costly legal battles that threaten your business. This is where esthetician liability insurance steps in.
At its core, it’s a specialized business insurance designed to protect skincare professionals from the unique risks in our field. It’s a shield offering financial protection, safeguarding your professional credibility, and ensuring business continuity. Without it, you could be personally liable for significant losses. The average spa industry claim is $5,500, and that’s before factoring in medical expenses, lost wages, and devastating legal defense costs. Even baseless claims can be financially ruinous.
Real-world risks we face daily include:
- Allergic Reactions: Clients can have unforeseen reactions to skincare products, leading to potential claims.
- Chemical Burns: Procedures like chemical peels carry the risk of burns if a client has an unexpected sensitivity.
- Slip-and-Fall Accidents: A wet floor or misplaced item can lead to injuries and demands for compensation.
- Product-Related Issues: If a product you use or sell causes harm, you could face product liability claims.
- Professional Negligence: Claims that a treatment caused a rash or didn’t deliver promised results can lead to lawsuits.
Esthetician liability insurance transfers this financial risk to the insurance provider, allowing you to focus on your clients. We can guide you in securing robust Business Liability Insurance customized for estheticians.
The Core Coverages in a Policy
A comprehensive policy combines several types of coverage, each designed to protect you from different risks.

Let’s break down the core coverages you’ll find in a robust policy:
Professional Liability Insurance
Also known as malpractice insurance or Errors and Omissions Insurance (E&O), this is the most critical component. It protects you from claims arising from your professional services, such as negligence claims, mistakes in service, or a failure to deliver results. If a client alleges a chemical peel burn or that incorrect treatment advice led to a bad outcome, this insurance covers legal defense costs, settlements, and judgments.
General Liability Insurance
Often called “slip-and-fall” insurance, general liability insurance protects you from broader third-party claims for bodily injury and property damage on your premises. For example, if a client falls on a wet floor or you spill wax on their property, this covers their medical bills or repair costs, plus legal fees if they sue. It’s a fundamental part of our General Liability Insurance strategy.
Beyond the big two, a comprehensive esthetician liability insurance policy often includes other vital protections:
- Product Liability Insurance: Essential if you use, recommend, or sell products. It protects you if a product causes an allergic reaction or harm.
- Rental Damage Coverage: A lifesaver if you rent a booth or space. It covers accidental damage you might cause to the premises, like from a fire or water leak.
- Tools & Equipment Coverage: Protects your essential assets—like facial machines and product inventory—from theft, fire, or damage, whether they’re at your salon, in transit, or at a client’s home.
How Much Does Esthetician Liability Insurance Cost?
A common question is, “How much does esthetician liability insurance cost?” It’s surprisingly affordable, especially considering the protection it provides. Policies can cost as little as $0.45 per day, or around $179 to $259 per year for full-time professionals. Student policies can be as low as $49 to $60 annually.

Many providers offer monthly payment options, and you can often save up to 25% by bundling policies. For example, general liability might start around $29 per month, with professional liability around $42 monthly. However, the exact cost is influenced by several key factors unique to your business.
Factors That Influence Your Premium
Your insurance premium is customized to your specific needs and risks. Key factors include:
- Services Offered: High-risk services like microblading, permanent makeup, laser treatments, or chemical peels typically increase premiums.
- Geographic Location: Costs vary by state and city due to different legal environments and claim histories. We can provide specific insights for our clients in Norfolk VA, Virginia, North Carolina, West Virginia, and Florida.
- Coverage Limits and Deductibles: Higher coverage limits increase your premium, while a higher deductible can lower it.
- Business Revenue and Size: Larger businesses with more employees or higher revenue may have higher premiums due to greater risk exposure.
- Claims History: A history of claims can lead to higher premiums.
- Experience and Training: Some insurers may offer better rates for experienced professionals with advanced certifications.
Is Cheap Esthetician Insurance the Best Option?
While it’s tempting to choose the cheapest esthetician liability insurance, we caution against deciding on price alone. A bare-bones policy might save money upfront but leave you exposed when a claim arises. The true value is in comprehensive coverage that protects your livelihood. Look beyond the cost and examine the policy details:
- Coverage Breadth: Does the policy cover all your services with sufficient limits? We recommend at least $2 million per occurrence for both general and professional liability.
- Policy Exclusions: Carefully review what the policy doesn’t cover to avoid unexpected gaps.
- Long-Term Protection: An “occurrence-form” policy offers lifelong protection for incidents that happen while the policy is active, which is often a better long-term value than a “claims-made” policy.
Our goal is to find the Best Esthetician Insurance that offers robust protection and value, not just the lowest price.
Choosing the Right Policy for Your Skincare Business
Now that you know why esthetician liability insurance is vital, let’s choose the right policy for your business. The options can seem confusing, but we’re here to simplify the process and help you make an informed decision. As experts in Insurance for Beauty Professionals, we’ll guide you to feel confident that your business is truly protected.
Key Features to Look For in Your Esthetician Liability Insurance Policy
When comparing policies, a few key details make a real difference in your long-term peace of mind.
First is Occurrence-Form vs. Claims-Made Coverage. This is a critical distinction.
- An Occurrence-Form policy covers any incident that happens while your policy is active, regardless of when the claim is filed. This offers superior, long-term protection.
- A Claims-Made policy only covers claims made while your policy is active. If you let it lapse, you could lose coverage for past incidents.
Next are your Coverage Limits, the maximum amount your insurer will pay for a claim. We suggest generous limits, with most top policies offering at least $2 million per occurrence (for a single incident) and a $3 million annual aggregate (the total payout in a policy year). Higher limits ensure you’re protected against significant lawsuits.
Also, consider an Individual vs. Shared Aggregate. Some association policies have a “shared aggregate,” meaning the total coverage limit is split among all members. If others make claims, it could deplete the funds available for you. We advocate for policies with an “individual aggregate,” where your limits are dedicated solely to you.
You’ll also want the ability to Add Additional Insureds. Landlords or salon owners often require you to add them to your policy. A good policy makes this easy and free, letting you generate unlimited certificates.
Finally, look for Policy Portability. If you’re a mobile esthetician or work in multiple locations, you need coverage that follows you wherever you practice within the U.S.
Is Esthetician Liability Insurance a Legal Requirement?
The answer is: it varies. Some states and cities require liability insurance to maintain your business license. It’s wise to check with your State Board or look up your state licensing information for local rules. We can help clients in Virginia, North Carolina, West Virginia, and Florida understand specific requirements.
Even if not legally mandated, Landlord and Salon Requirements often make it necessary. If you rent a booth or space, the owner will almost certainly require you to have your own policy to protect them. Beyond any rules, carrying insurance boosts your Professional Credibility, showing clients you are a responsible professional who cares about their safety.
How to Get a Certificate of Insurance (COI)
Once your policy is active, you’ll need a Certificate of Insurance (COI) as proof of coverage for landlords or event organizers. Modern providers make this easy. You can typically get instant access to a digital COI through an online account or mobile app as soon as you purchase your policy. Most policies also offer unlimited certificates, allowing you to add additional insureds at no extra cost. We ensure this process is smooth so you can focus on your clients!
Frequently Asked Questions about Esthetician Coverage
We know you have questions, and we’re here to answer them. Let’s address some of the most common inquiries about esthetician liability insurance.
Do I need insurance if I only work part-time or am a student?
Yes, absolutely! Accidents and claims don’t depend on your work schedule. The risks of working with clients and products exist whether you’re full-time, part-time, or a student. For part-time professionals, the potential cost of a single lawsuit dwarfs the insurance premium. For students, insurance is crucial because even under supervision, you’re performing treatments on real people. A mishap could leave you personally liable for legal bills. The good news is that many providers offer affordable student policies—sometimes as low as $49-$60 annually—that provide full coverage during your training.
Does insurance cover me if I work in multiple locations or am a mobile esthetician?
Yes. Most individual esthetician liability insurance policies are designed to be flexible and fully portable. Your coverage travels with you, whether you work in a salon, rent a booth, have a home studio, or provide mobile services at clients’ homes. This portability means you’re protected wherever you practice within the 50 U.S. states, giving you peace of mind without needing separate policies for different locations.
What advanced services might require extra coverage or a special policy?
As esthetics evolves, so do the services we offer. While many comprehensive esthetician liability insurance policies cover over 500 modalities, certain advanced procedures may require extra coverage or a specific policy endorsement due to heightened risks.
Always double-check your coverage for services like:
- Microblading and Permanent Makeup: These semi-invasive procedures carry risks of infection or allergic reactions.
- Laser Treatments: Laser hair removal or skin resurfacing is considered high-risk due to the potential for burns or scarring.
- Intense Pulsed Light (IPL): Similar to lasers, IPL carries risks of burns or skin damage.
- Cryolipolysis: Fat reduction treatments using extreme cold have unique risks.
- Radiofrequency and High-Frequency Treatments: These energy-based treatments carry risks of burns or irritation.
Before offering a new, advanced service, verify coverage with your insurance provider. If it’s not included, ask about seeking an endorsement (an addition to your policy) or a specialized policy. A proactive conversation with your insurer can save you from significant financial and legal trouble.
Secure Your Business and Your Future
You’ve worked hard to build your career as an esthetician, pouring your heart into helping clients. Esthetician liability insurance isn’t just another expense; it’s a fundamental pillar that supports your business and protects your passion.

Think of it as your ultimate peace of mind. The right coverage provides a solid financial safeguard and smart risk management, ensuring your career has longevity. It allows you to focus on what you do best: helping clients achieve that perfect glow.
At Strange Insurance Agency, we understand the unique needs of estheticians. As your personal concierge insurance partner, we make getting comprehensive esthetician liability insurance simple and stress-free. Powered by Goosehead Insurance, we bring you multiple options from over 30 top-rated companies, ensuring you get custom coverage that fits your services and location. Whether you’re in Norfolk VA, or anywhere across Virginia, North Carolina, West Virginia, or Florida, we’ve got you covered quickly and efficiently.
Ready to protect your practice and ensure your passion thrives? Explore your Business Insurance options and find the perfect coverage. We’re here to help you steer the details so you can keep making the world a more beautiful place.