
Why Food Product Liability Insurance Is Essential for Every Food Business
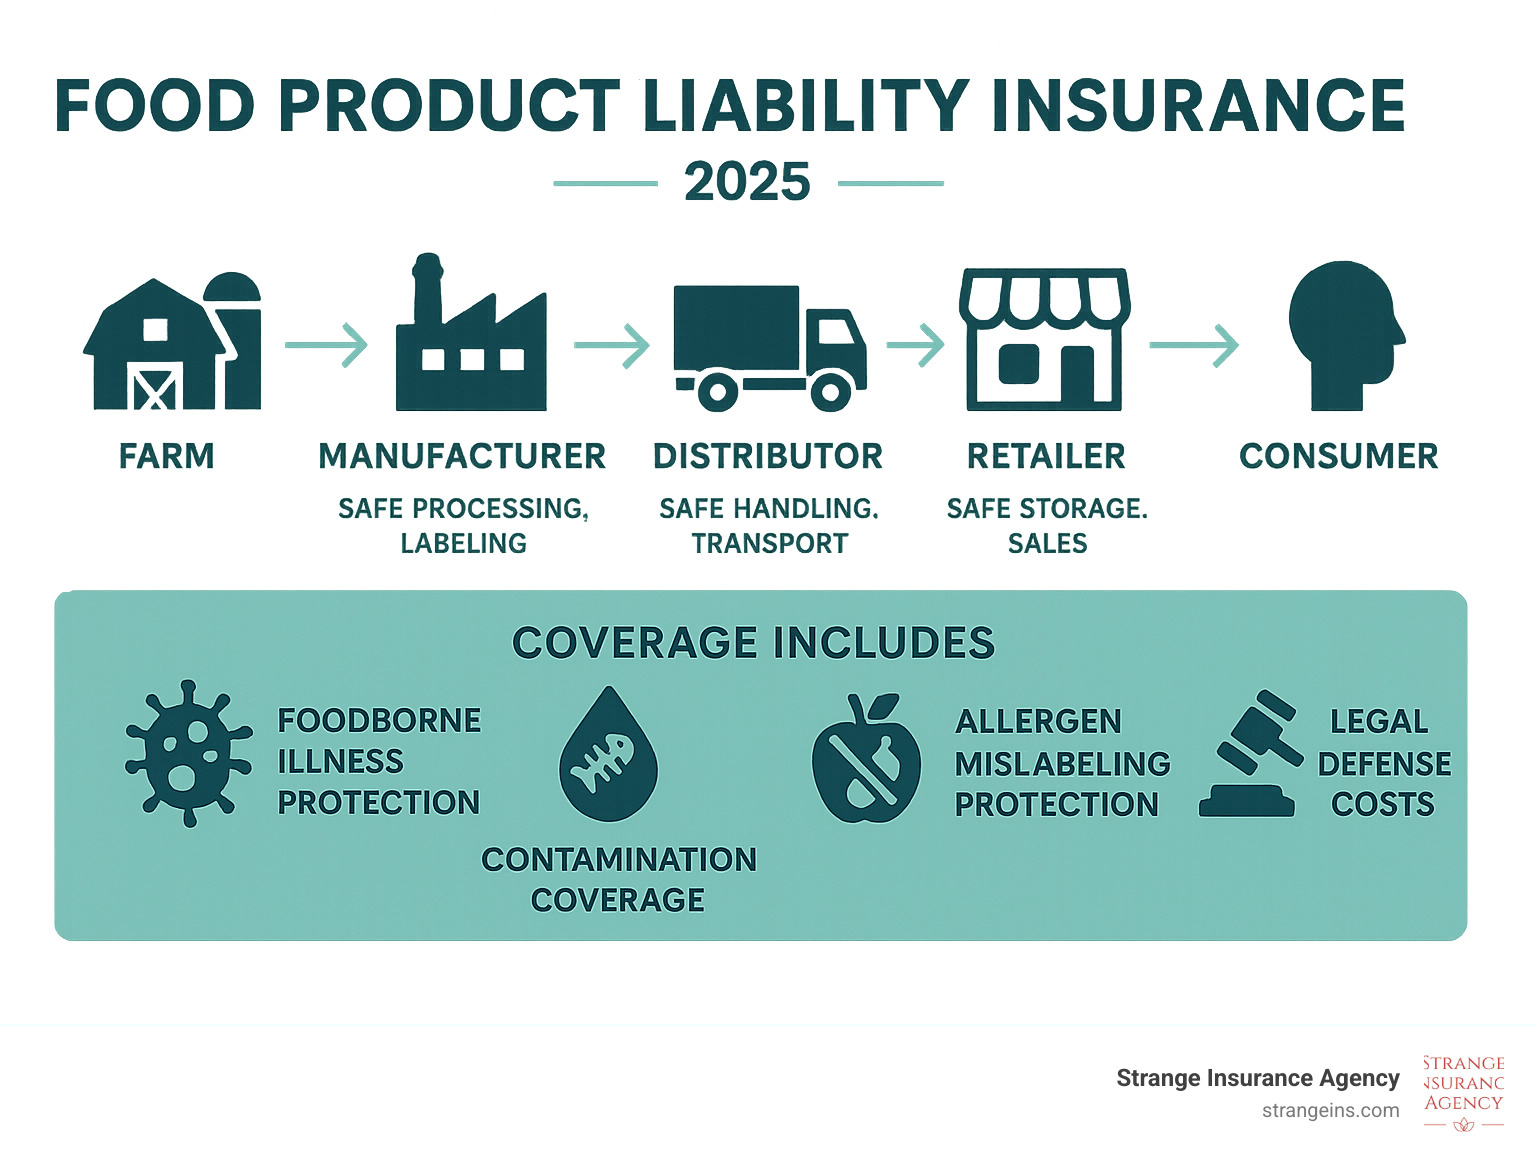
Food product liability insurance protects food businesses from financial losses when customers claim illness, injury, or property damage from consuming their products. This specialized coverage handles legal defense costs, medical expenses, and settlements when foodborne illnesses, allergic reactions, or contamination issues arise.
Key Coverage Areas:
- Foodborne illness claims (E. coli, Salmonella, Listeria)
- Allergic reactions from mislabeled ingredients
- Foreign objects causing injury (glass, metal fragments)
- Property damage from contaminated products
- Legal defense and settlement costs
Who Needs This Coverage:
- Food manufacturers and processors
- Restaurants, cafes, and food trucks
- Caterers and bakeries
- Online food retailers
- Beverage producers
- Cottage food operations
The food industry faces unique risks that can devastate businesses overnight. According to the Food and Drug Administration (FDA), approximately 48 million cases of foodborne illnesses occur annually in the US – that’s 1 in 6 Americans getting sick each year. These incidents result in 128,000 hospitalizations and 3,000 deaths annually.
Without proper coverage, a single contamination incident can lead to hundreds of thousands of dollars in medical bills, legal fees, and settlements. Many venues, distributors, and retailers now require food businesses to carry this insurance before they’ll work with them.
As Christian Strange with over 15 years of experience in insurance and business consulting, I’ve helped countless food businesses understand the critical importance of food product liability insurance in protecting their operations from devastating financial losses. My expertise at Strange Insurance Agency ensures food entrepreneurs get the right coverage to safeguard their passion and profits.
Must-know food product liability insurance terms:
- what does business liability insurance cover
- general liability insurance and workers comp
- insurance for online marketplace sellers
What is Food Product Liability Insurance and What Does It Cover?

Food product liability insurance is your business’s financial shield when customers claim your food products caused them harm. This specialized coverage steps in when someone gets sick from your food, suffers an allergic reaction, or gets injured by something in your product.
Think of it as protection for the “what ifs” that keep food business owners up at night. What if a customer gets food poisoning from your restaurant? What if someone finds a piece of glass in your packaged goods? What if you accidentally mislabel an allergen?
This insurance covers several key areas of financial protection. It handles bodily injury claims when customers get sick or hurt from your products. It also covers property damage claims – like when contaminated food ruins someone’s kitchen or event. The policy pays for legal defense costs, which can quickly reach tens of thousands of dollars even for baseless claims.
Your coverage also includes medical payments for immediate medical expenses, settlements you agree to pay, and court judgments if a case goes to trial. It’s comprehensive protection that lets you focus on running your business instead of worrying about potential lawsuits.
For more details on how business liability protection works, check out our guide on Business Liability Insurance.
Specific Risks Covered
Food product liability insurance protects against the unique dangers that come with feeding people. Foodborne illness claims are the most common – think E. coli outbreaks from contaminated lettuce or Salmonella poisoning from undercooked chicken. These cases can involve hundreds of people and millions in damages.
Contamination coverage protects when unwanted substances get into your food. This could be chemical contamination from cleaning supplies, biological contamination from bacteria, or cross-contamination between different food items.
Foreign objects in food cause serious injuries. Broken glass, metal fragments, plastic pieces, or even natural items like bones where they shouldn’t be can chip teeth, cause cuts, or require emergency surgery. Your insurance handles these painful and expensive claims.
Mislabeled allergens represent a growing risk as food allergies become more common and severe. If your product contains nuts, dairy, gluten, or other allergens but your label doesn’t clearly state this, you could face serious liability when someone has a reaction.
Faulty packaging that fails to protect food can lead to spoilage, contamination, or exposure to harmful elements. Incorrect preparation instructions can also cause problems – if your cooking directions are wrong and someone gets sick, you’re responsible.
Common covered incidents include:
- Restaurant food poisoning outbreaks
- Contaminated batch recalls
- Allergic reactions from unlisted ingredients
- Injuries from foreign objects in packaged foods
- Illness from improperly preserved foods
- Cross-contamination between allergens
What is not covered by food product liability insurance?
While food product liability insurance offers broad protection, it doesn’t cover everything. Understanding these gaps helps you build complete coverage for your food business.
Product recalls aren’t covered by standard policies. When you need to pull products from shelves, the costs for notifications, shipping, storage, and disposal come out of your pocket. Recall expenses can easily reach hundreds of thousands of dollars, so many food businesses buy separate recall coverage.
Lost income during business interruptions isn’t included either. If a liability incident forces you to close temporarily or causes sales to plummet, your policy won’t replace that lost revenue. You’d need separate business interruption insurance for this protection.
Intentional acts are always excluded. Insurance only covers accidents and mistakes, not deliberate harm. If you or your employees intentionally contaminate food or cause injury, you’re on your own.
Employee injuries fall under a different type of coverage entirely. If your kitchen staff gets burned, cut, or hurt while working, that’s a workers’ compensation claim, not a product liability issue. Every food business needs both types of protection since they cover completely different risks.
For more information about protecting your employees, visit our Workers Compensation Insurance page.
Why Every Food Business Needs a Serving of Protection

Running a food business is like hosting a dinner party for thousands of strangers every day. You pour your heart into creating amazing dishes, but you can’t control what happens after that first bite. This is exactly why food product liability insurance isn’t just recommended – it’s absolutely essential for protecting everything you’ve worked so hard to build.
The moment you hand over that sandwich, sell that jar of sauce, or serve that wedding cake, you become legally responsible for its safety. If something goes wrong, the financial consequences can be staggering. We’re not just talking about a few hundred dollars here and there – foodborne illness claims regularly reach six or seven figures.
But it’s not just about potential lawsuits. Today’s food industry operates on contractual requirements that make this coverage mandatory. Try getting your products into a grocery store chain without proof of liability insurance – it simply won’t happen. These retailers have learned from experience that uninsured suppliers create massive headaches when problems arise.
Venue requirements are equally strict. Whether you’re running a food truck at the local festival or catering a corporate event, property owners and event organizers will demand to see your insurance certificate before you can set up shop. They’re protecting themselves, and they expect you to do the same. For mobile food vendors, this coverage often overlaps with Event Vendor Insurance.
Your brand reputation is another crucial consideration. In our social media world, news of a food safety incident spreads faster than butter on warm toast. While insurance can’t prevent negative publicity, it provides the financial resources to handle claims professionally and invest in damage control efforts.
Most importantly, food product liability insurance protects your financial solvency. Without it, a single serious claim could force you to close your doors permanently. It’s not just about protecting your business – it’s about protecting your dreams.
Types of Businesses That Need Coverage
The food industry is beautifully diverse, but that diversity means virtually every type of food business faces product liability risks. Food manufacturers and processors sit at the beginning of the supply chain, where a single contaminated batch can affect thousands of consumers across multiple states.
Restaurants and cafes create their products fresh daily, serving customers face-to-face. Every meal that leaves your kitchen becomes your responsibility, from food poisoning claims to allergic reactions from undeclared ingredients.
Caterers face unique challenges because they’re preparing large quantities of food off-site, often with limited kitchen facilities. When you’re feeding 200 wedding guests, the stakes are incredibly high.
Food trucks bring additional complexity with mobile preparation and serving in various locations. The combination of cooking on the go and serving diverse crowds creates multiple liability exposures.
Bakeries might seem lower-risk, but allergen cross-contamination and ingredient mislabeling can lead to serious claims. That “nut-free” cookie better actually be nut-free.
Online food sellers face modern challenges as e-commerce grows. If you’re selling through major online platforms, you need specialized coverage – learn more about insurance for online marketplace sellers.
Even cottage food operations working from home kitchens need protection. State cottage food laws don’t shield you from liability if your homemade jam makes someone sick.
Beverage producers aren’t exempt either. From craft beer to cold-pressed juices, drinks can harbor bacteria or contain undeclared allergens just like solid foods.
The Consequences of Being Uninsured
Operating without food product liability insurance is like driving blindfolded on a busy highway – you might get lucky for a while, but eventually, disaster strikes. The financial consequences can be absolutely devastating.
Out-of-pocket legal fees start accumulating the moment someone files a claim, even if it’s completely baseless. Defense attorneys specializing in food liability cases charge $300-500 per hour, and these cases can drag on for years. A simple case easily costs $50,000 just in legal fees.
Paying for large settlements comes next. Food poisoning cases regularly settle for hundreds of thousands of dollars, especially when multiple victims are involved. A severe outbreak affecting dozens of people can result in multi-million dollar judgments that would bankrupt most small businesses overnight.
Potential bankruptcy becomes a real threat when legal costs and settlements exceed your business assets. We’ve seen successful restaurants and food manufacturers forced to close permanently after a single uninsured incident.
Damaged business reputation might be the hardest consequence to overcome. News of food safety problems spreads instantly through social media and review sites. Rebuilding customer trust after a publicized incident can take years – if it’s even possible.
The inability to grow or partner with larger companies limits your business potential permanently. Without insurance, you’re locked out of major distribution channels, retail partnerships, and growth opportunities that could transform your business.
These consequences aren’t theoretical – they happen to real food businesses every year. Don’t let your business become another cautionary tale.
Product Liability vs. General Liability: A Key Distinction
Many food business owners wonder about the difference between food product liability insurance and general liability insurance. While both are essential for protecting your business, they work like two different safety nets, each catching different types of risks that could threaten your operation.
Think of general liability insurance as your day-to-day operations protector. This coverage handles the classic scenarios that happen at your business location – like when a customer slips on a wet floor in your restaurant, trips over equipment near your food truck, or gets injured by your delivery driver. It also covers situations where you accidentally damage someone else’s property while working at their venue, or claims involving advertising injuries like copyright infringement.
Food product liability insurance, however, focuses specifically on what happens after your food products leave your hands. This coverage kicks in when the actual food or beverage you created, manufactured, or sold causes harm to someone. The key difference is that the problem stems from the product itself, not from something that happened at your location.
Here’s how these two types of coverage compare:
| Coverage Focus | Product Liability Insurance | General Liability Insurance |
|---|---|---|
| Primary Protection | Product-related harm after sale | Premises and operations incidents |
| Common Claims | Foodborne illness, contamination, foreign objects | Slip and fall, property damage, advertising injury |
| When It Applies | After product leaves your control | During business operations |
| Location | Anywhere the product is consumed | Primarily at business premises |
The relationship between these policies is important to understand. Many food businesses bundle both coverages together, and some insurers offer food product liability insurance as an endorsement to a general liability policy. This approach often provides better coverage coordination and can be more cost-effective than purchasing separate policies.
For comprehensive protection, most food businesses need both types of coverage working together. Your general liability handles the everyday operational risks, while product liability protects against the unique dangers that come with putting food products into the marketplace.
To learn more about how general liability insurance fits into your overall business protection strategy, visit our detailed guide: More info about Business Insurance/General Liability Insurance.