
Why Your Pressure Washing Business Needs Financial Protection
General liability insurance for pressure washing business is essential coverage that protects your company from third-party claims of bodily injury, property damage, and personal injury lawsuits. Here’s what you need to know:
Key Protection Areas:
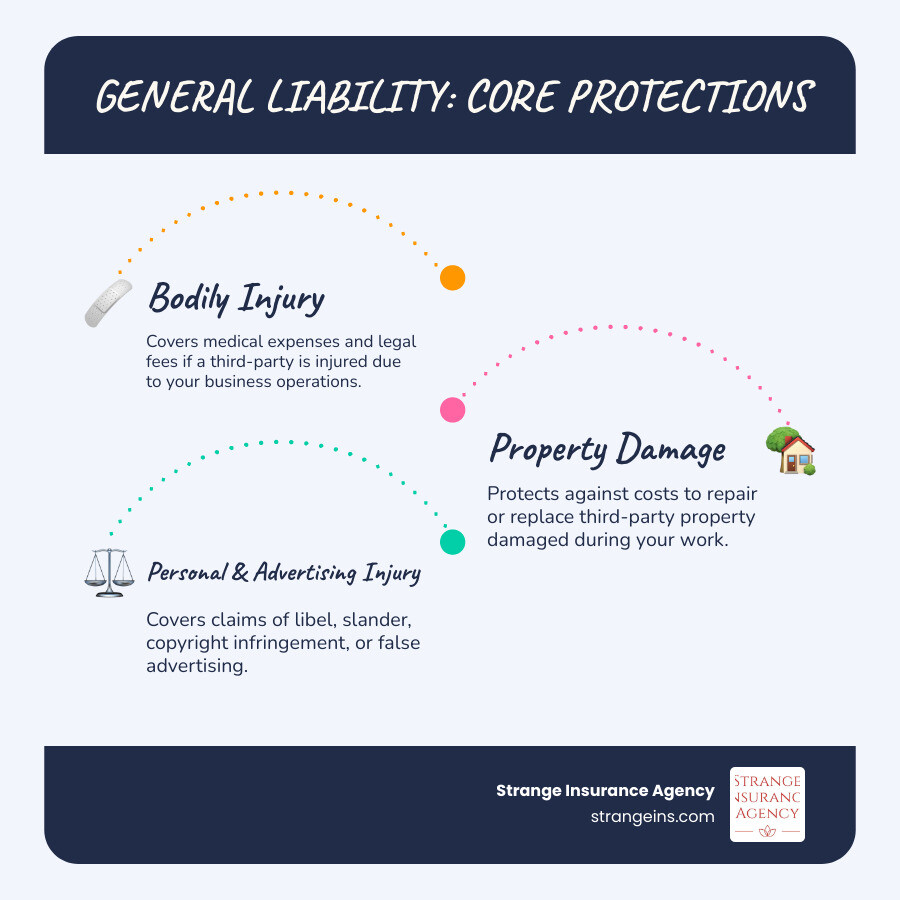
- Bodily Injury Claims – Customer trips over equipment or gets injured on your job site
- Property Damage – Accidental damage to client’s siding, windows, or landscaping from high-pressure water
- Legal Defense Costs – Coverage for attorney fees and court costs even if claims are groundless
- Personal & Advertising Injury – Protection against libel, slander, or copyright infringement claims
Average Costs:
- Monthly premiums range from $75-$103 for most pressure washing businesses
- Annual coverage typically costs between $895-$1,233
- Policy limits commonly include $1 million per occurrence and $2 million aggregate
Running a pressure washing business means working with powerful equipment that can cause serious damage in seconds. A pressure washer’s forceful spray could easily damage a home’s siding or cause an injury – and business insurance helps pay for legal expenses, medical bills, and repair costs that could otherwise sink your business.
As Christian Strange with over 15 years of experience in insurance and business consulting, I’ve helped countless service businesses understand why general liability insurance for pressure washing business operations is non-negotiable protection. At Strange Insurance Agency, I’ve seen how the right coverage transforms a risky venture into a secure, professional operation.
Must-know general liability insurance for pressure washing business terms:
- what does business liability insurance cover
- business liability insurance
- general liability insurance and workers comp
What is General Liability Insurance and Why Do Pressure Washers Need It?
Imagine you’re finishing up a driveway cleaning job when your client steps outside to admire your work. Unfortunately, they don’t see the wet surface and slip, breaking their wrist in the fall. Or picture this: while pressure washing a home’s exterior, a slight miscalculation sends a powerful stream through a window, shattering glass and damaging expensive furniture inside.
These scenarios aren’t meant to scare you – they’re real situations that happen to even the most careful pressure washing professionals. That’s exactly why general liability insurance for pressure washing business operations exists.
General liability insurance (sometimes called commercial general liability or CGL) is your business’s financial shield against third-party claims. It covers situations where someone else gets hurt or their property gets damaged because of your business activities. Think of it as protection against the “what if” moments that keep business owners awake at night.
For pressure washing businesses, this coverage isn’t just helpful – it’s absolutely essential. You’re working with equipment that can generate up to 4,000 PSI of pressure. To put that in perspective, that’s about 275 times more powerful than your average garden hose. While this incredible force makes you excellent at removing stubborn dirt and grime, it also creates unique risks that most other service businesses never face.
The reality is that pressure washing involves high-pressure equipment and often chemical cleaning solutions on someone else’s valuable property. Every job site presents potential hazards, from the equipment itself to the wet surfaces you create. Even the most experienced professionals can have accidents – and when they do, the financial consequences can be devastating without proper protection.
Many clients, especially commercial customers, won’t even consider hiring you without proof of insurance. They’ll ask for a Certificate of Insurance before signing any contract. Having Business and Public Liability Insurance demonstrates your professionalism and shows clients that you take their safety and property seriously.
The medical research backs up these concerns too. Reports of serious injuries from pressure washers document cases of severe lacerations, eye injuries, and even amputations. While these extreme cases are rare, they highlight why having proper insurance coverage isn’t optional – it’s a business necessity.
The Unique Risks of the Pressure Washing Industry
Your pressure washing business faces risks that most other service companies never encounter. The combination of powerful water pressure, slippery surfaces, and working on customer property creates a perfect storm of potential liability issues.
Water damage tops the list of common problems. High-pressure water can force its way behind siding, into window frames, or through small cracks, leading to expensive mold problems or structural damage that might not show up for weeks. What starts as a simple exterior cleaning job could turn into thousands of dollars in hidden water damage.
Property damage scenarios happen more often than you’d think. Siding damage from too much pressure, broken windows from direct spray contact, or paint stripping from aggressive cleaning techniques can turn a profitable job into a financial nightmare. Even experienced operators can have equipment malfunction or misjudge the right pressure setting for delicate surfaces.
Then there are the slip-and-fall hazards that come with the territory. Wet driveways, soapy walkways, and debris washed onto pathways create dangerous conditions for anyone walking nearby. Your cleaning process naturally makes surfaces slippery, and that creates liability exposure every single day.
Chemical use adds another layer of risk. Cleaning solutions can damage landscaping, stain surfaces, or cause allergic reactions in sensitive individuals. Even eco-friendly products can harm certain plants or materials if not used correctly.
General liability insurance covers third-party accidents – injuries or damage involving your clients, their visitors, or the general public. Employee accidents fall under workers’ compensation insurance, which is a separate coverage we’ll discuss later. Your general liability policy focuses specifically on protecting you from claims made by people outside your business.
How General Liability Protects Your Business Assets
When someone files a claim against your pressure washing business, you’re not just facing the cost of repairs or medical bills. You’re potentially looking at a lawsuit that could threaten everything you’ve worked to build.
General liability insurance steps in as your financial bodyguard, covering legal defense costs even when claims are completely groundless. We’ve seen frivolous lawsuits cost businesses tens of thousands of dollars in attorney fees alone. Your policy helps pay for lawyers, court costs, and expert witnesses needed to defend your business.
If the claim has merit, your insurance can cover settlements reached outside of court or judgments awarded by a judge or jury. This protection extends up to your policy limits, creating a financial safety net that keeps one bad day from destroying your entire business.
Without this protection, a single serious incident could force you into bankruptcy. Legal fees can easily reach $50,000 or more before a case even goes to trial. Add in potential damage awards or settlement costs, and you’re looking at financial exposure that could wipe out years of hard work and savings.
The peace of mind that comes with proper coverage is invaluable. Instead of worrying about every potential mishap, you can focus on growing your business and serving your customers. You’ll sleep better knowing that if something does go wrong, you have professional support and financial backing to handle the situation properly.
This protection becomes even more critical as your business grows. More jobs mean more exposure, and higher-value clients often mean higher-stakes potential claims. Having robust Business Liability Insurance allows you to take on bigger projects and expand your services with confidence.
What Does General Liability Insurance for a Pressure Washing Business Cover?
Understanding what general liability insurance for pressure washing business actually covers can help you make informed decisions about protecting your company. At its core, this insurance focuses on claims from third parties who might be injured or have their property damaged during your pressure washing operations.
When you purchase a general liability policy, you’ll encounter several key terms that determine how much protection you have. The per-occurrence limit is the maximum your policy pays for any single incident – typically $1 million for pressure washing businesses. The aggregate limit represents the total amount your policy will pay out during the entire policy year, commonly set at $2 million.
Most general liability policies for pressure washers come with minimal or zero deductibles, meaning you won’t pay out-of-pocket before coverage kicks in. This is different from your auto insurance, where deductibles are standard.
One document you’ll use constantly is your Certificate of Insurance (COI). This official proof of coverage is what clients request before letting you start work. At Strange Insurance Agency, we can provide instant COIs once your policy is active, helping you secure contracts without delays.
Key Coverages in General Liability Insurance for a Pressure Washing Business
Your general liability insurance for pressure washing business includes several distinct types of protection that work together to shield you from financial disaster.
Third-party bodily injury coverage handles medical bills, lost wages, and legal expenses when someone gets hurt because of your business operations. This could be a homeowner who slips on your freshly washed deck or a neighbor who trips over equipment you’ve placed on the sidewalk.
Third-party property damage coverage is absolutely critical for pressure washing operations. When your high-pressure water accidentally damages vinyl siding, cracks a window, or kills a client’s prized landscaping with chemical overspray, this coverage pays for repairs or replacement.
Products-completed operations coverage extends your protection beyond the job site and after you’ve finished work. If problems surface days or weeks later that trace back to your pressure washing service, you’re still covered. Think of a deck board that weakens from your cleaning and later breaks when someone steps on it.
Personal and advertising injury protection covers non-physical harm to others. This includes libel (written defamation), slander (spoken defamation), and copyright infringement. If you accidentally use someone else’s copyrighted photo in your marketing materials or if a competitor claims you’ve copied their advertising slogan, this coverage helps with legal defense costs.
Real-World Claim Scenarios for Pressure Washers
Let me paint a picture of how these coverages work in real situations that pressure washing businesses face regularly.
Picture this: you’re cleaning a driveway in Virginia Beach, and your hose stretches across the walkway. The homeowner comes outside to check your progress, doesn’t see the hose, and takes a hard fall that breaks their wrist. Your bodily injury coverage steps in to handle their medical bills and any potential lawsuit.
Here’s another common scenario: while pressure washing a two-story home in Charlotte, your water spray hits a second-floor window at just the wrong angle, sending spider cracks across the glass. The property damage portion of your policy covers the window replacement, saving you from a hefty out-of-pocket expense.
Chemical mishaps happen too. You’re cleaning a concrete patio in Norfolk, and some of your cleaning solution drifts onto the client’s expensive ornamental plants, causing them to wither and die. Again, your property damage coverage handles the cost of replacing those plants.
Even advertising can create problems. Say you launch a new marketing campaign, and another local business claims your tagline infringes on their trademark. The personal and advertising injury coverage helps pay for legal defense, even if the claim turns out to be baseless.
These real-world examples show why general liability insurance for pressure washing business operations isn’t optional – it’s essential protection that keeps your business running when accidents happen. For more comprehensive information about what’s covered, check out our detailed guide on General Liability Insurance.
The Cost of Coverage: What to Expect
Let’s talk numbers – because we know that’s probably what you’re wondering about right now. The good news? General liability insurance for pressure washing business is surprisingly affordable, especially when you consider what it protects you from.
Most pressure washing businesses pay between $75 and $103 per month for solid general liability coverage. That translates to roughly $895 to $1,233 annually – less than what many of us spend on coffee in a year, yet it protects your entire livelihood.
Here’s what that investment typically gets you: $1 million per occurrence coverage and $2 million aggregate protection with around a $500 deductible. That’s substantial financial backing for what amounts to a few dollars a day.
I always tell my clients to think about it this way: one accidental window break could cost you $500 to replace. One slip-and-fall lawsuit? That could easily run into the tens of thousands – or more. Your monthly premium suddenly looks like the bargain it really is.
The beauty of having proper coverage is the confidence it gives you. You can bid on those bigger commercial jobs, work in upscale neighborhoods, and sleep well at night knowing you’re protected. That peace of mind often translates directly into business growth opportunities you might otherwise pass up.
Every policy we write is customized to fit your specific needs and budget. We’re not interested in selling you coverage you don’t need, but we also want to make sure you’re not underprotected.
Factors Influencing the Cost of General Liability Insurance for a Pressure Washing Business

Your premium isn’t pulled out of thin air – insurance companies look at several key factors to determine what you’ll pay for general liability insurance for pressure washing business coverage.
Your business location plays a bigger role than you might expect. Operating in Norfolk, VA might have different risk factors than serving clients across North Carolina, West Virginia, or Florida. Urban areas with higher population density often mean more foot traffic around your work sites, which can translate to higher premiums. Rural areas might have their own considerations, like longer response times for emergency services.
The size of your operation directly impacts your rates. Flying solo? You’ll typically pay less than a business owner managing multiple crews. More employees mean more opportunities for something to go wrong, and insurance companies price accordingly.
Your claims history is like your credit score in the insurance world. A clean record with no past claims keeps your rates low, while previous incidents signal higher risk to insurers. The good news is that even businesses with past claims can still get coverage – it just might cost a bit more.
The type of work you do matters too. Residential driveways and deck cleaning carry different risks than commercial building washing or industrial equipment cleaning. If you’re also offering services like roof cleaning or exterior painting, that changes your risk profile and affects pricing.
Coverage limits give you control over your costs. Higher limits like $2 million per occurrence instead of the standard $1 million provide more protection but increase your premium. We help you find that sweet spot between adequate protection and affordable rates.
Your deductible choice is another way to manage costs. Choosing a higher deductible – say $1,000 instead of $500 – can lower your monthly premium. Just make sure you’re comfortable paying that amount out-of-pocket if a claim arises.
At Strange Insurance Agency, we work through all these factors with you to build a policy that fits both your protection needs and your budget. No surprises, no overselling – just honest advice to keep your business safe and profitable.
Is General Liability Required and How Does It Compare to Other Policies?
The question of whether general liability insurance for pressure washing business is legally required isn’t straightforward, and the answer depends on where you operate and who you work with. From a federal standpoint, there’s no blanket requirement for general liability coverage. However, individual states have their own rules that can vary significantly.
In our service areas of Virginia, North Carolina, West Virginia, and Florida, you’ll find different requirements. Some states mandate workers’ compensation insurance if you have employees, while others require commercial auto insurance for business-owned vehicles. It’s always wise to check with your state and local government guidelines to understand what’s specifically required in your area.
But here’s where it gets interesting – while the law might not require general liability insurance, your clients almost certainly will. Most residential homeowners want to see proof of coverage before they’ll hire you, and commercial clients? They’re even more stringent about it. Without a Certificate of Insurance in hand, you could find yourself locked out of the most profitable contracts.
This isn’t just about checking a box for clients. They want assurance that if something goes wrong on their property, they’re protected and you have the financial means to handle any damages. It’s really about demonstrating that you’re a professional who takes responsibility seriously.
| Policy Type | What it Covers | What it Doesn’t Cover |
|---|---|---|
| General Liability Insurance | Third-party bodily injury, property damage to others, personal/advertising injury, legal defense costs | Your own injuries, employee injuries, your own property damage, your tools and equipment |
| Tools & Equipment Insurance | Theft, damage, or loss of your pressure washing equipment, generators, hoses, and other tools | Third-party injuries, property damage to others, legal defense for liability claims |
| Workers’ Compensation Insurance | Employee injuries, illnesses, medical expenses, lost wages, rehabilitation costs | Third-party injuries, property damage, your own injuries as the owner |
Differentiating General Liability from Other Essential Coverages
Understanding how general liability insurance for pressure washing business fits into your overall protection strategy means knowing what it doesn’t cover – and what other policies you might need to fill those gaps.
Tools & Equipment Insurance, also known as Inland Marine coverage, protects your actual pressure washing equipment. When your $3,000 pressure washer gets stolen from a job site or damaged in transport, general liability won’t help you replace it. This coverage steps in to cover the repair or replacement costs for your essential business tools.
Commercial Auto Insurance becomes crucial if you’re using vehicles for your business operations. Here’s a critical point many pressure washing business owners miss: your personal auto insurance explicitly excludes business use. If you’re driving to job sites, transporting equipment, or using your vehicle for any business purpose, you need commercial coverage. For those times when you or your employees use personal vehicles for work, Hired and Non-Owned Auto coverage can bridge that gap.
Workers’ Compensation Insurance protects your employees when they get injured on the job. While general liability covers third-party injuries, workers’ comp specifically handles your team members’ medical expenses, lost wages, and rehabilitation costs. In many states, this coverage is legally required once you have employees, and even as a sole proprietor, it can protect you from work-related injuries.
Professional Liability, sometimes called Errors & Omissions insurance, covers you when clients claim your work was inadequate or caused damage through negligence. While general liability handles accidents, professional liability addresses allegations that you didn’t perform your services properly or made mistakes that led to financial losses for your clients.
The beauty of understanding these distinctions is that you can build a comprehensive protection plan that covers all your bases. At Strange Insurance Agency, we help you identify which coverages are essential for your specific situation and which ones might be nice-to-have additions as your business grows.
For a deeper understanding of how these policies work together, you can explore our resources on Workers Compensation Insurance and General Liability Insurance and Workers Comp to see how they complement each other in protecting your pressure washing business.