
Why Protecting Your Williamsburg Home Starts with Smart Insurance Choices
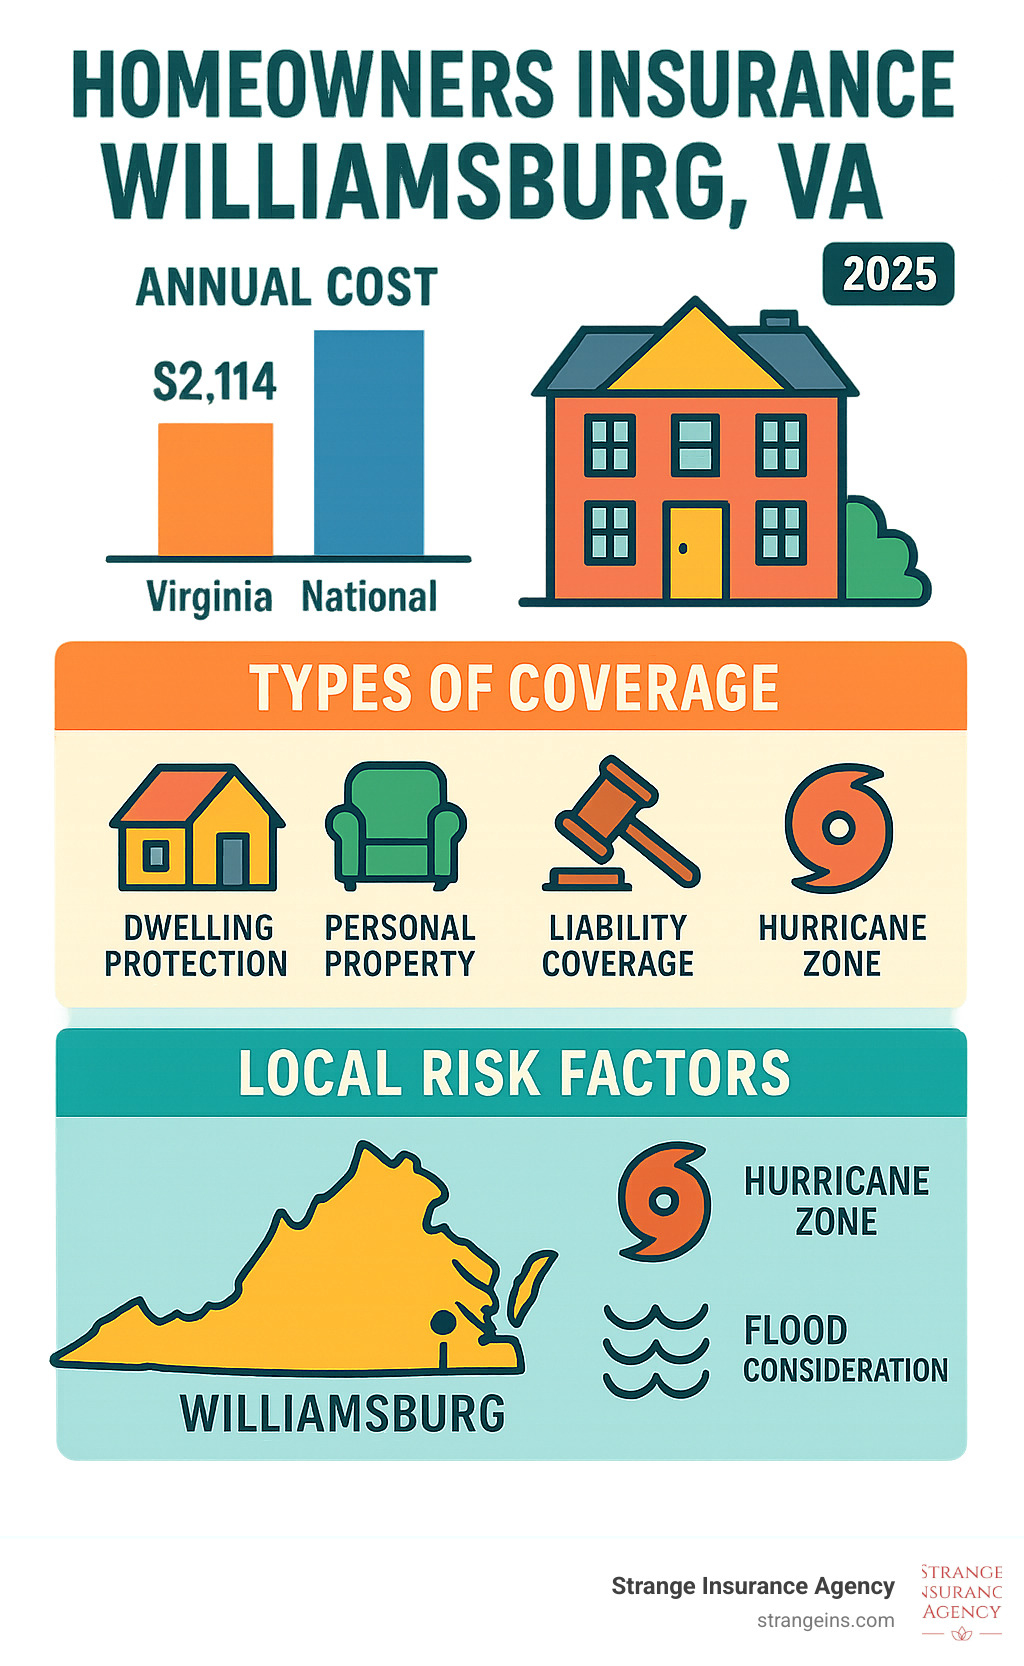
Homeowners insurance williamsburg va is essential protection for your most valuable investment, with average annual premiums of $2,114 for $300,000 in dwelling coverage. Whether you own a historic Colonial in the heart of Williamsburg or a modern home in New Town, the right coverage protects against hurricanes, flooding, and liability risks unique to Virginia’s coastal region.
Quick Answer for Homeowners Insurance in Williamsburg, VA:
– Average Cost: $2,114/year for $300k dwelling coverage
– Cheapest Provider: American Family at $687/year average
– Required by Law: No, but mortgage lenders require it
– Key Local Risks: Hurricanes, flooding, historic home code upgrades
– Best Savings: Bundle home + auto (save up to $950/year)
Your home faces unique challenges in Williamsburg. Hurricane season brings wind and water damage. Historic district regulations mean rebuilding costs often exceed standard estimates due to special materials and code requirements. Even homes outside flood zones can experience water damage from nor’easters and heavy rainfall.
Virginia homeowners pay 25% less than the national average for home insurance. But rates vary dramatically – from $687 to over $4,500 annually depending on your credit score, home value, and coverage choices.
Smart homeowners compare quotes from multiple carriers, understand their local risks, and work with experienced agents who know Williamsburg’s specific challenges.
I’m Christian Strange, and I’ve spent over 15 years helping families and businesses steer insurance decisions and risk management. Through my work with homeowners insurance williamsburg va clients, I’ve seen how the right coverage provides peace of mind when storms hit our coastal community.
Handy homeowners insurance williamsburg va terms:
– home insurance quotes in virginia
– property insurance virginia
– best home insurance companies virginia
Homeowners Insurance Williamsburg VA: Why It Matters
Living in Williamsburg means calling one of America’s most charming historic communities home. But this prime spot between the James and York Rivers also puts your property squarely in hurricane alley. We’ve watched too many neighbors learn the hard way that coastal storms can turn from weekend inconveniences into financial disasters.
Those gorgeous historic homes in Colonial Williamsburg face unique challenges. When Hurricane Isabel roared through in 2003, homeowners found their policies didn’t account for the sky-high costs of historically accurate restoration. Try finding hand-forged hardware or period-appropriate brick – your wallet will feel the difference.
The flooding risk sneaks up on people who think they’re safe because they’re not waterfront. Williamsburg sits in low-lying terrain where heavy rainfall overwhelms storm drains faster than you’d expect. We’ve helped clients deal with soggy basements after nor’easters dumped several inches of rain in just a few hours.
Virginia law doesn’t require homeowners insurance, but your mortgage lender absolutely will. More importantly, your home represents your family’s biggest financial investment. Without proper coverage, one bad storm could erase decades of equity.
The liability landscape in Virginia means you need solid protection if someone gets hurt on your property. Between delivery drivers, contractors, and neighbors dropping by, your home sees more foot traffic than you realize.
Explore Williamsburg flood map
Community resilience in Williamsburg is strong. Neighbors help neighbors, and local contractors know how to rebuild better. The right insurance coverage ensures you’re part of that recovery story.
What Is Homeowners Insurance Williamsburg VA
Homeowners insurance williamsburg va works like a financial safety net with six essential pieces that protect different parts of your life.
Dwelling coverage rebuilds your home’s structure when covered disasters strike. This includes your walls, roof, built-in appliances, and permanently attached fixtures.
Personal property coverage protects your belongings – furniture, clothes, electronics, and all those items that make your house feel like home. This coverage even follows you around.
Liability protection handles the legal mess if someone gets injured on your property. With Virginia’s legal environment, we recommend at least $300,000 in coverage.
Loss of use coverage pays for hotels and restaurant meals when your home becomes unlivable during repairs. This coverage has saved our clients thousands when they couldn’t cook in their own kitchen or sleep in their own beds.
Other structures coverage protects detached buildings like your garage, garden shed, or fence. Standard policies typically provide 10% of your dwelling coverage for these extras.
Medical payments coverage quickly handles minor guest injuries without the drama of a liability claim.
Unique Risks in Williamsburg VA
Williamsburg’s beautiful location creates specific challenges that directly impact your insurance needs and costs.
Hurricane season runs from June through November, with August and September bringing the biggest threats. These storms pack damaging winds, torrential rain, and storm surge that can reach properties miles from the water.
Nor’easters sneak in throughout winter and spring, often dumping more total rainfall than hurricanes. These slow-moving storms stick around longer, giving floodwater more time to find its way into unexpected places.
Tidal flooding affects low-lying neighborhoods even during minor weather events. Climate change has made “sunny day flooding” more common during high tides and full moons.
Historic district requirements in Colonial Williamsburg demand specific materials and construction methods that cost significantly more than standard building practices.
How Much Does Homeowners Insurance Cost in Williamsburg?
When I sit down with Williamsburg homeowners to discuss their insurance needs, the first question is always about cost. The good news? Homeowners insurance williamsburg va averages around $2,114 annually for a solid policy with $300,000 dwelling coverage, $100,000 liability protection, and a $1,000 deductible.
That’s actually a pretty sweet deal compared to many coastal areas. Virginia homeowners enjoy premiums that run about 25% lower than the national average, thanks to our state’s reasonable weather patterns and strong insurance regulations.
Your home’s value directly impacts what you’ll pay. A more modest $200,000 dwelling coverage policy typically costs around $1,615 per year, while homeowners protecting higher-value properties see proportional increases.
| Dwelling Coverage | Annual Premium | Monthly Cost |
|---|---|---|
| $200,000 | $1,615 | $135 |
| $300,000 | $2,114 | $176 |
| $400,000 | $2,682 | $224 |
| $600,000 | $3,982 | $332 |
These averages give you a starting point, but your actual premium depends on factors we can often influence in your favor through smart shopping and risk management.
Homeowners Insurance Williamsburg VA Rates by Credit Tier
Your credit score has a huge impact on your insurance premium. I’ve watched clients save thousands of dollars annually just by improving their credit before shopping for coverage.
Homeowners with excellent credit scores (750 and above) enjoy average premiums around $1,039 annually. These folks get access to the best rates and premium discounts.
Those with good credit (700-749) pay closer to $1,615 annually – still very reasonable rates with access to most discount programs.
Fair credit (650-699) bumps the average to $2,348 annually. You’ll have fewer discount options and higher base rates, but coverage remains accessible.
Poor credit (below 650) creates real challenges, with average premiums jumping to $4,531 annually. Carrier choices become limited, and discount opportunities practically disappear.
The math is sobering: excellent credit saves you $3,492 annually compared to poor credit. That’s enough money for a nice family vacation or major home improvement project.
Factors That Shape Your Premium
Every home tells a unique story, and insurance companies read that story carefully when setting your premium.
Your home’s age and construction matter tremendously. Newer homes with modern electrical systems, updated plumbing, and efficient HVAC equipment qualify for better rates because they present fewer risks.
Roof condition deserves special attention in our hurricane-prone area. A newer roof, especially one made from impact-resistant materials, can slash your premium by 10-15%.
Security systems provide both peace of mind and premium savings. Monitored alarm systems, security cameras, and smart home devices can reduce your costs significantly.
Your deductible choice creates a direct trade-off between premium costs and out-of-pocket expenses during claims. Higher deductibles lower your annual premium but increase what you’ll pay when filing a claim.
Claims history follows you for 3-5 years, especially water damage or liability incidents. However, many carriers offer claim-free discounts for homeowners who maintain clean records.
Location specifics within Williamsburg affect your rates too. Distance from fire stations, flood zone designations, and local crime statistics all factor into pricing.
Replacement cost represents what it would actually cost to rebuild your home today, including materials, labor, permits, and code upgrades.
Coverage Essentials & Smart Add-Ons for Virginia Homes

A standard HO-3 homeowners policy provides broad coverage for most perils, but Williamsburg’s unique risks often require additional protection.
Standard Coverage Includes:
– Dwelling protection against fire, wind, hail, vandalism, and theft
– Personal property coverage for belongings (typically 50-70% of dwelling coverage)
– Personal liability protection (usually $100,000-$300,000)
– Medical payments to others ($1,000-$5,000)
– Additional living expenses during repairs
– Other structures coverage (typically 10% of dwelling coverage)
What’s NOT Covered:
– Flood damage (requires separate policy)
– Earth movement (earthquakes, sinkholes, landslides)
– Maintenance issues and wear-and-tear
– Business activities conducted from home
– Certain high-value items without scheduling
Must-Have Optional Coverages
Based on our experience with Williamsburg claims, these optional coverages often prove essential:
Flood Insurance protects against water damage from storms, heavy rainfall, and storm surge. Standard homeowners policies exclude flood damage entirely. Even homes outside high-risk flood zones can benefit from coverage – about 25% of flood claims occur in moderate-to-low risk areas.
Personal Property Replacement Cost upgrades your belongings coverage from actual cash value to full replacement cost. This endorsement eliminates depreciation.
Water Backup Coverage protects against sewer and drain backups, sump pump failures, and similar water intrusion. This coverage has become increasingly important as aging infrastructure struggles with heavy rainfall.
Ordinance or Law Coverage pays extra costs when rebuilding must meet current building codes. Historic homes in Williamsburg often face significant code upgrade expenses during reconstruction.
Equipment Breakdown Coverage protects home systems and appliances – HVAC, electrical panels, water heaters, and built-in appliances.
Nice-to-Have Endorsements for Williamsburg
Additional coverages worth considering:
Umbrella Liability provides extra liability protection beyond your homeowners policy limits. With Virginia’s legal environment and Williamsburg’s tourist population, we recommend umbrella coverage for homeowners with significant assets.
Valuable Articles Coverage schedules high-value items like jewelry, art, collectibles, and musical instruments.
Identity Fraud Coverage helps with expenses related to identity theft, including legal fees, lost wages, and document replacement costs.
Service Line Coverage protects underground utility lines from your home to the street connection.
Common Exclusions to Watch
Understanding what’s NOT covered prevents claim surprises:
Earth Movement: Earthquakes, sinkholes, landslides, and soil subsidence require separate coverage.
Wear and Tear: Gradual deterioration, maintenance issues, and aging components aren’t covered.
Pest Damage: Termites, rodents, and other pest damage typically aren’t covered unless they cause sudden, accidental damage.
Mold: Most policies limit mold coverage or exclude it entirely unless it results from a covered peril.
Business Activities: Home-based businesses need separate coverage.
Saving Money on Homeowners Insurance in Williamsburg
Nobody wants to overpay for insurance, especially when you’re already dealing with Virginia’s coastal weather risks. Smart homeowners insurance williamsburg va shoppers can save hundreds – sometimes thousands – of dollars annually without sacrificing protection.
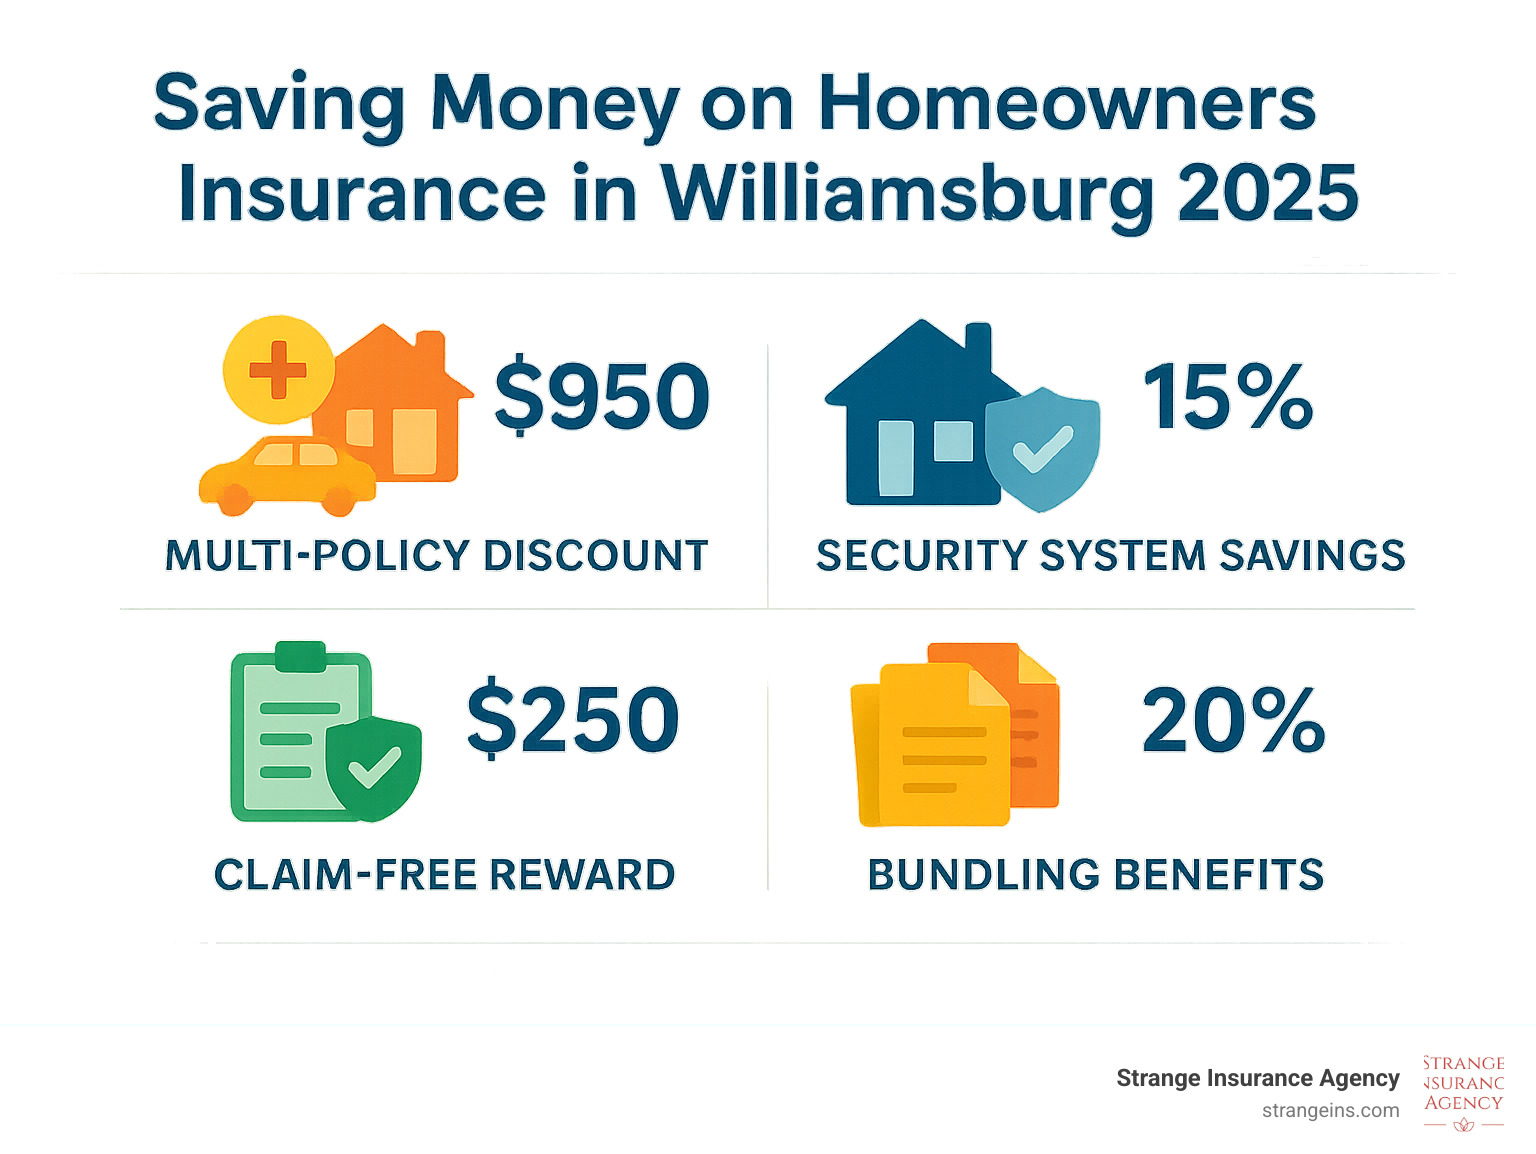
The biggest money-saver is multi-policy bundling. When you combine your home and auto insurance, you can save up to $950 per year. That’s real money that stays in your pocket instead of going to insurance premiums.
Security improvements pay for themselves through insurance discounts. A monitored alarm system can save you $63 annually, while comprehensive security packages with cameras and smart home devices offer even larger reductions.
Claims-free discounts reward homeowners who haven’t filed recent claims, with savings that increase over time. Some carriers offer up to 25% off for five claim-free years.
New home discounts recognize that newer construction typically means fewer problems. If your home was built within the last 5-10 years, you’ll likely qualify for these savings.
Don’t overlook occupational discounts either. Teachers, engineers, military personnel, and other professionals often qualify for special rates. Senior discounts help retirees who spend more time at home.
Homeowners Insurance Rates Virginia
Here’s where the real savings potential lies: credit score improvement. Moving from poor to excellent credit can save over $3,000 annually on homeowners insurance.
Higher deductibles reduce your premiums, but make sure you can comfortably afford the out-of-pocket costs if you need to file a claim.
Cheap Homeowners Insurance Strategies
Finding affordable coverage without cutting corners requires a strategic approach.
Shopping early gives you the advantage of time and choice. Start your insurance search 30-60 days before your current policy expires.
Annual reviews keep you competitive in a changing market. Insurance rates shift frequently, and what was a great deal last year might not be competitive today.
Working with an independent agent like Strange Insurance Agency gives you access to 30+ carriers instead of being stuck with just one company’s rates. We shop the market for you.
Defensive home improvements can qualify you for immediate discounts while making your home more resilient. Upgrading your roof, installing impact-resistant windows, or adding security systems often pay for themselves through reduced premiums.
Bundling Home & Auto in Williamsburg VA
Combining your homeowners and auto insurance delivers benefits that go way beyond just saving money.
The average savings from bundling can reach up to $950 annually on your combined premiums. Individual savings vary based on your coverage levels and chosen carrier, but most families see meaningful reductions.
Simplified management makes your life easier. One agent to call, one renewal date to remember, and coordinated coverage limits mean less paperwork and fewer headaches.
Some carriers offer unique benefits for bundled customers that you can’t get elsewhere. These might include gap coverage improvements, extended rental car coverage, or priority claims handling.
Claims coordination becomes much smoother when both policies are with the same carrier.
Quote-to-Claim Roadmap for Williamsburg Homeowners

Getting the right homeowners insurance williamsburg va coverage involves several important steps:
Online Quote Process:
1. Gather basic home information (year built, square footage, construction type)
2. Document safety features (alarms, sprinklers, security systems)
3. Determine appropriate coverage limits based on replacement cost
4. Compare quotes from multiple carriers
5. Review coverage details, not just premiums
Dwelling Valuation: Accurate replacement cost calculation is crucial. We help clients account for Williamsburg’s unique factors like historic district requirements, local labor costs, and premium materials.
Documentation Needs: Maintain detailed home inventories with photos and receipts. This preparation speeds claim processing and ensures accurate settlements.
Latest data on VA home-insurance costs
Claim Filing Timeline:
– Immediate: Secure your property and prevent further damage
– 24-48 Hours: Contact your insurance company to report the claim
– 3-7 Days: Adjuster inspection and damage assessment
– 1-2 Weeks: Initial settlement estimate and advance payments
– 30-60 Days: Final settlement for complex claims
Adjuster Visits: Prepare for thorough property inspections. Document all damage with photos and maintain receipts for temporary repairs and additional living expenses.
Repair Contracts: Choose contractors carefully and ensure they’re licensed and insured. Your insurance company may recommend preferred contractors but cannot require you to use them.
Choosing the Best Agent or Carrier
Selecting the right insurance partner involves evaluating several key factors:
Financial Strength: Choose carriers with strong financial ratings from A.M. Best, Moody’s, or Standard & Poor’s. These ratings indicate the company’s ability to pay claims.
Complaint Ratios: Research carrier complaint ratios through your state insurance department. Lower ratios indicate better customer service and claims handling.
Local Expertise: Agents familiar with Williamsburg’s unique risks provide better guidance on coverage needs and local contractors.
Digital Tools: Modern carriers offer online account management, mobile apps for claims reporting, and digital payment options.
24/7 Claims Service: Storm damage doesn’t wait for business hours. Choose carriers with round-the-clock claims reporting and emergency services.
First-Time Homebuyer Tips in Williamsburg
New homeowners face unique insurance challenges:
Closing Checklist: Your lender requires proof of insurance before closing. Start shopping for coverage as soon as your offer is accepted.
Escrow Considerations: Most mortgage payments include insurance premiums in escrow. Understanding this process helps with budgeting.
Proof of Insurance Requirements: Lenders typically require specific coverage levels and may have preferred carrier lists. Confirm requirements early in the process.
Deductible Affordability: Choose deductibles you can afford to pay out-of-pocket. New homeowners often have limited emergency funds after closing costs.
Frequently Asked Questions about Homeowners Insurance Williamsburg VA
Is homeowners insurance required by law in Virginia?
Virginia doesn’t legally require homeowners insurance williamsburg va, but don’t let that fool you into thinking it’s optional. Your mortgage lender will absolutely require coverage before you can close on your home. They’re protecting their investment just as much as yours.
Even if you’ve paid off your mortgage completely, skipping homeowners insurance is like driving without a seatbelt. Your home is probably your biggest asset, and living in Williamsburg means dealing with hurricanes, flooding, and other coastal risks that could wipe out your investment overnight.
We’ve seen too many homeowners think they can save money by going without coverage, only to face devastating losses when storms hit. The peace of mind alone is worth the annual premium.
Do I really need flood insurance if I’m outside a high-risk zone?
This is one of the most important questions we get, and the answer is a resounding yes. About 25% of flood insurance claims happen in moderate-to-low risk areas – areas that many homeowners assume are “safe” from flooding.
Williamsburg sits in a unique geographic position that creates flood risks even outside officially designated flood zones. We’re surrounded by water, built on relatively low-lying land, and subject to both coastal storms and heavy rainfall events that can overwhelm drainage systems.
Here’s what many homeowners don’t realize: your standard homeowners insurance williamsburg va policy excludes flood damage completely. That means if water enters your home from outside sources – whether from storm surge, heavy rain, or overflowing creeks – you’re paying for repairs out of your own pocket.
NFIP flood insurance for homes outside high-risk zones typically costs just $400-600 annually. Compare that to the tens of thousands you might spend replacing flooring, drywall, and belongings after a flood. We’ve helped clients file flood claims, and the relief on their faces when they realize they’re covered is priceless.
How long does a typical claim take from inspection to payout?
The timeline for homeowners insurance claims varies significantly based on the complexity of your situation. Simple claims often wrap up within 1-2 weeks, while more complex situations can take 30-60 days or even longer.
Several factors influence how quickly your claim gets resolved. Minor damage with clear documentation processes much faster than major reconstruction projects. If you have good photos, receipts, and a detailed home inventory, your adjuster can move through the assessment quickly.
Storm-related claims take longer because everyone files at once, creating backlogs for adjusters and contractors. After Hurricane Isabel, some of our clients waited weeks just for their initial inspection because adjusters were overwhelmed with claims throughout the region.
Documentation quality makes a huge difference in claim speed. Clients who maintain detailed home inventories with photos and receipts typically see much faster settlements than those scrambling to recreate their losses from memory.
We work closely with our clients throughout the claims process, helping them understand what to expect and advocating for fair, timely settlements. Having an experienced agent in your corner can significantly improve both the speed and outcome of your claim.
Conclusion
Your Williamsburg home deserves protection that goes beyond checking boxes for your mortgage company. Homeowners insurance williamsburg va coverage shields your family’s biggest investment from hurricanes that sweep up from the Atlantic, flooding that can strike even outside high-risk zones, and liability situations that could threaten your financial security.
The numbers work in your favor here in Virginia. At $2,114 annually for solid coverage, you’re paying about 25% less than homeowners in other states. But don’t let those reasonable rates fool you into thinking the risks are small.
Your coverage strategy should reflect Williamsburg’s unique character. If you own a historic home, those beautiful period details come with premium reconstruction costs that standard policies might not fully cover. Whether your home dates to Colonial times or went up last year, flood insurance makes sense for every Williamsburg property – about a quarter of flood claims happen in areas not even considered high-risk.
The best protection combines smart dwelling coverage that accounts for true replacement costs, personal property protection that covers your belongings at full value, and liability limits that protect your assets from Virginia’s legal environment.
Your premiums don’t have to break the bank. Bundling your home and auto insurance can save nearly $1,000 annually, while security systems and claim-free records open up additional discounts. Most importantly, maintaining excellent credit can slash your rates by thousands compared to homeowners with poor credit scores.
At Strange Insurance Agency, we’ve spent over 15 years helping families in our community find the right balance of protection and affordability. Our concierge approach means we do the heavy lifting – comparing quotes from 30+ top carriers, explaining coverage options in plain English, and staying available when you need us most.
We understand that insurance isn’t exciting. But the peace of mind that comes from knowing your family’s security is rock-solid? That’s priceless. When the next storm approaches or life throws you a curveball, you’ll rest easy knowing your coverage has your back.
Ready to give your Williamsburg home the protection it deserves? Let’s chat about your specific needs and find coverage that fits your budget and lifestyle. Your family’s financial future is worth a few minutes of your time today.