
Why Individual Umbrella Insurance Is Your Financial Lifeline
Individual umbrella insurance provides extra liability protection beyond your standard home and auto policies, covering you when lawsuit costs exceed your basic coverage. This safety net protects your assets, future earnings, and financial security from catastrophic claims that could otherwise devastate your family’s finances.
Quick Answer: Individual Umbrella Insurance Essentials
- What it is: Extra liability coverage that kicks in when your home/auto policy limits are exceeded.
- Cost: Typically $200-$300 annually for $1 million in coverage.
- Who needs it: Anyone with assets to protect or higher lawsuit risk (e.g., pool owners, landlords, teen drivers).
- Coverage: Bodily injury, property damage, legal defense costs, and personal injury claims like slander.
- Requirements: Usually need $250k+ auto liability and $300k+ homeowners liability coverage first.
One lawsuit can change everything. Research shows 70% of umbrella claims are auto-related. Without proper protection, a single accident could drain your savings, retirement funds, and even future earnings to pay a judgment that exceeds your standard policy limits.
The reality is stark: if you cause serious injuries in a car accident or someone gets hurt on your property, medical bills and legal costs can easily reach millions of dollars. Your standard auto policy might only cover $100,000 per person, while your homeowners policy typically provides $300,000 in liability. When facing a $2 million lawsuit, you’re personally responsible for the difference.
I’m Christian Strange. With over 15 years in insurance, I’ve seen how this affordable coverage can be the difference between a lawsuit being a minor inconvenience versus a life-altering financial disaster. At Strange Insurance Agency, we believe it’s one of the most cost-effective forms of financial protection available.
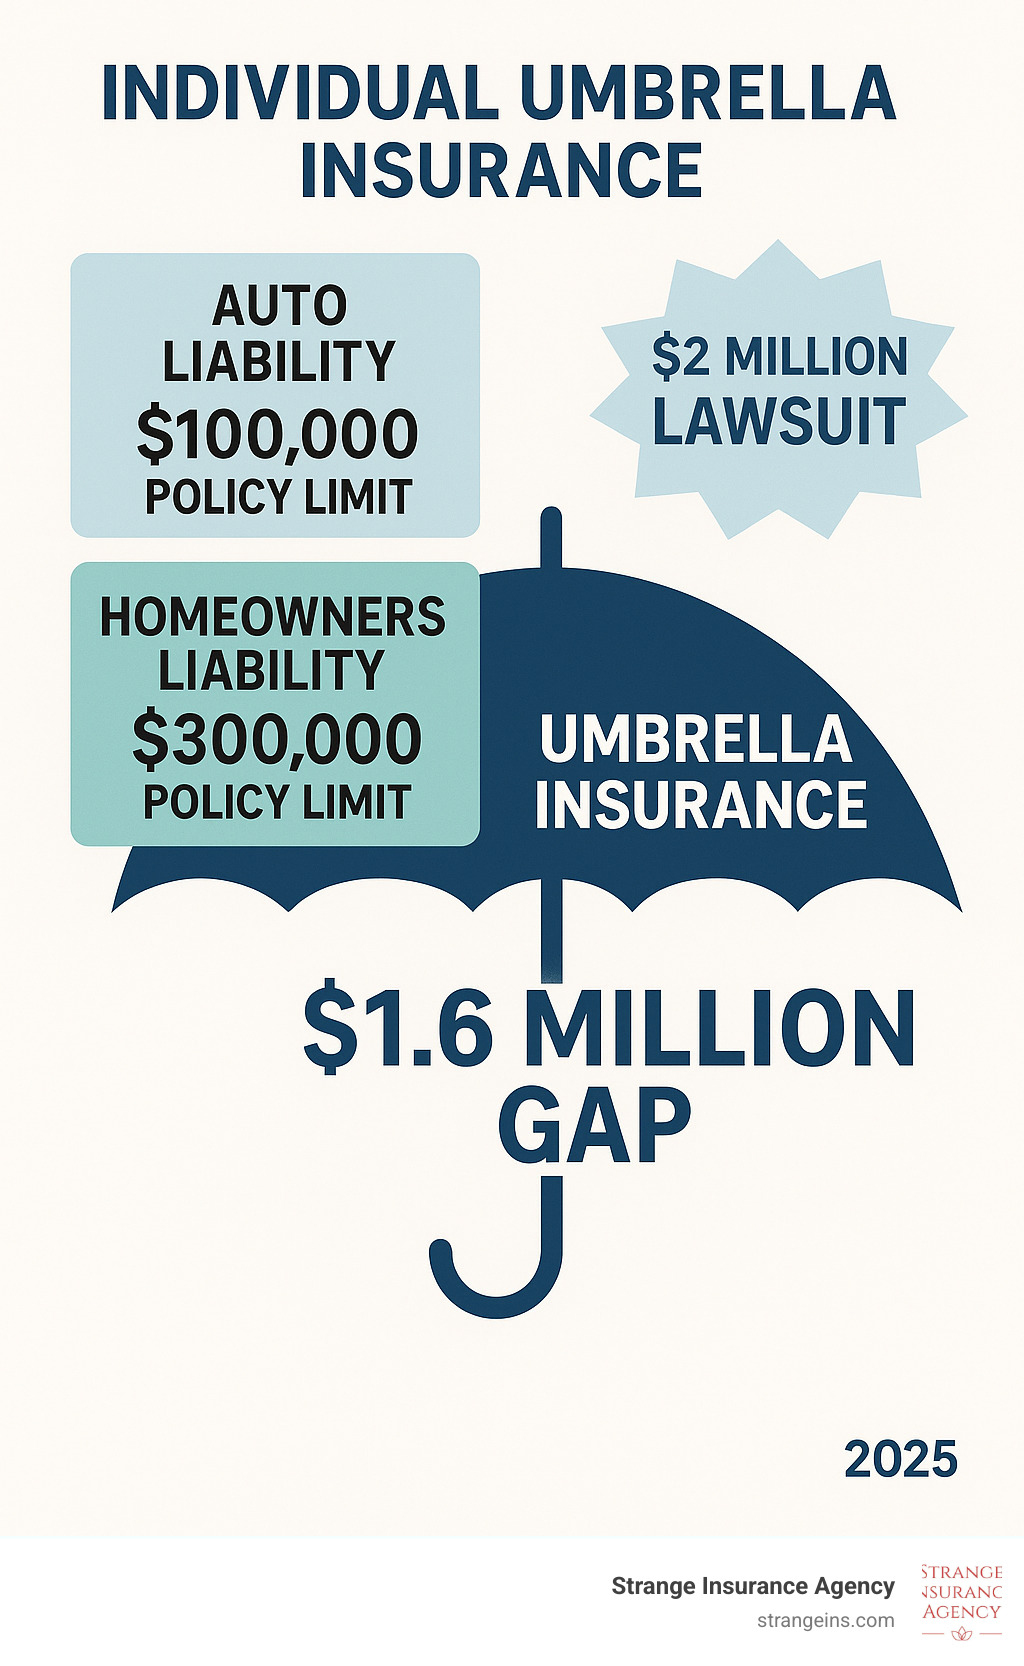
Simple individual umbrella insurance word guide:
What is Umbrella Insurance? The Ultimate Safety Net Explained
Imagine causing a serious car accident that results in a $2 million lawsuit. Your auto insurance only covers $100,000. The remaining $1.9 million would have to come from your savings, retirement fund, and future earnings—unless you have individual umbrella insurance.
Individual umbrella insurance is a protective shield that covers you when life’s storms hit hardest. It’s an extra layer of liability protection that kicks in when your regular insurance policies reach their limits. Think of it as your financial bodyguard, standing ready to protect everything you’ve worked so hard to build.
Here’s how it works: your umbrella policy sits on top of your existing homeowners, auto, and watercraft policies. When a claim exceeds those underlying policy limits, your umbrella coverage steps in to handle the overflow. It’s often called “excess liability coverage” because it provides protection in excess of your standard policies.
Crucially, individual umbrella insurance also protects you from claims your standard insurance might not cover at all, like libel, slander, or invasion of privacy. In our social media world, these personal injury claims are becoming more common.
Sometimes, your umbrella policy might act as your primary coverage for certain claims. When this happens, you’ll typically pay a “Self-Insured Retention” (SIR)—think of it like a deductible—before your umbrella coverage kicks in. This is less common than the umbrella simply providing an extra layer of protection.
The peace of mind that comes with knowing you’re protected is invaluable. For more detailed information, check out these resources:
The Role of Your Underlying Policies
Your existing insurance policies—auto, homeowners, boat insurance—form the foundation of your liability protection. Your individual umbrella insurance doesn’t replace these policies; it builds on top of them.
Before you can get an umbrella policy, insurance companies require you to carry substantial liability limits on your base policies. Most insurers will ask for at least $250,000 in auto liability coverage and $300,000 in homeowners liability coverage.
This makes financial sense, ensuring that everyday claims are handled by your primary policies, keeping your umbrella coverage available for truly catastrophic situations.
Why aren’t standard policies enough? The cost of a serious accident can skyrocket. Medical bills, lost wages, and pain and suffering awards can push total damages into the millions. For example, if a guest suffers a traumatic brain injury on your property and the lawsuit is for $1.5 million, your $300,000 homeowners policy leaves you responsible for the remaining $1.2 million. That’s where your individual umbrella insurance becomes a financial lifeline, covering the gap and protecting your assets.

Do You Need an Umbrella? Assessing Your Personal Liability Risk
At Strange Insurance Agency, we believe nearly everyone with assets or future earnings to protect should consider individual umbrella insurance. A single lawsuit can compromise your financial security, potentially draining your savings, investments, and even future income. A court could mandate that a portion of your future earnings be garnished to satisfy a judgment, highlighting the critical need for comprehensive protection.

To help you assess your personal liability risk, we’ve developed resources like:
High-Risk Lifestyles and Activities
Certain lifestyles and activities significantly increase your risk of a lawsuit. If any of the following apply to you, an individual umbrella insurance policy is more of a necessity than a luxury:
- Landlords: Owning rental properties exposes you to liability risks from tenants or property issues where a lawsuit can exceed standard coverage.
- Volunteers: Volunteering for non-profits or community events could lead to personal liability if an incident occurs.
- Youth Sports Coaches: Coaching children’s sports carries inherent risks, and an injury to a child could result in a lawsuit.
- Dog Owners: If your pet injures someone or damages their property, you could be held liable.
- Pool or Trampoline Owners: These are “attractive nuisances” that significantly increase the risk of serious injury on your property.
- Teen Drivers: Households with young drivers face a higher risk of serious auto accidents, which account for 70% of umbrella claims.
- Social Media Activity: Online posts, reviews, or comments can lead to claims of libel, slander, or defamation.
- Hosting Parties: Entertaining guests increases the chances of an injury occurring on your property.
Who Benefits Most from an Individual Umbrella Insurance Policy?
While the list above highlights common risks, anyone who wants to safeguard their financial future should consider this coverage. However, certain individuals benefit most:
- Individuals with Significant Assets: If you have substantial savings, investments, or properties, these assets are targets in a lawsuit. An umbrella policy protects them.
- Professionals with Public Profiles: Doctors, lawyers, and other professionals have higher public visibility, increasing their exposure to lawsuits like defamation.
- Families with Young Drivers: Auto incidents are a leading cause of large liability claims. Protecting your family with an umbrella policy is a smart move.
- Owners of Rental Properties: Landlords face specific risks related to tenants, maintenance, and visitor injuries that an umbrella policy can cover.
- Anyone Protecting Their Financial Future: Even if you aren’t “wealthy,” a major lawsuit can put your future earnings and retirement savings at risk. An umbrella policy protects what you plan to build.
We also offer specialized guidance for professionals looking to manage their risks, which you can learn more about here: Liability Insurance for Professionals.
Comprehensive Coverage: What an Individual Umbrella Insurance Policy Protects
One of the most compelling aspects of individual umbrella insurance is its broad scope of coverage. It goes beyond typical bodily injury and property damage, offering protection for a wider array of claims.
Generally, an umbrella policy will protect you against:
- Bodily Injury Liability: Covers costs for injuries to another person for which you’re responsible, including medical expenses, lost wages, and pain and suffering.
- Property Damage Liability: Covers costs if you damage someone else’s property.
- Legal Defense Costs: Crucially, your umbrella policy covers legal defense and attorney fees, even if a lawsuit is groundless. This is a significant benefit, as legal battles are expensive regardless of the outcome.
- Worldwide Protection: Many policies offer worldwide coverage, protecting you even when traveling internationally.
To dive deeper into the specifics, review:
What’s Covered: Beyond Standard Policies
This is where individual umbrella insurance truly shines, extending protection into areas often overlooked by basic policies:
Personal Injury Claims: This broad category includes non-physical injuries. Your umbrella policy can cover lawsuits arising from:
- Libel (written defamation)
- Slander (spoken defamation)
- False Arrest
- Malicious Prosecution
- Wrongful Eviction
- Invasion of Privacy
These claims can arise from social media posts or online reviews, making this coverage increasingly relevant.
Uninsured/Underinsured Motorist Protection (Optional Excess Coverage): Many policies offer optional excess uninsured/underinsured motorist (UM/UIM) coverage. This is vital because it protects you if you’re injured by a driver with little or no insurance. Your umbrella can provide additional coverage for your injuries beyond what the at-fault driver’s policy (or your own UM/UIM coverage) offers. This is particularly important in areas we serve like Virginia and North Carolina.
Understanding the Exclusions
While an individual umbrella insurance policy offers broad protection, it’s important to understand what it typically does not cover:
- Your Own Injuries or Property Damage: An umbrella policy is for liability to others. Your own home, auto, and health insurance cover your own property and injuries.
- Business-Related Losses: Personal umbrella policies exclude business activities. You need a separate commercial umbrella or business insurance policy for that.
- Intentional or Criminal Acts: Insurance is for accidents, not deliberate harm. Intentional acts are not covered.
- Liability Assumed Under Contract: If you sign a contract assuming liability you wouldn’t normally have, it may be excluded.
- Punitive Damages: Policies generally cover compensatory damages (to make the injured party whole) but not punitive damages, which are meant to punish egregious conduct.
The Financial Details: Costs, Limits, and Requirements
At Strange Insurance Agency, clients are often surprised by how affordable individual umbrella insurance is. For less than a dollar a day, you can add a powerful layer of protection against financial catastrophe—it’s one of the best values in insurance.
Consider the potential exposure:
| Scenario | Potential Cost of Lawsuit | Standard Policy Coverage (e.g., $300k) | Out-of-Pocket Exposure Without Umbrella | Cost of $1M Umbrella Policy (Annual) |
|---|---|---|---|---|
| Serious Car Accident | $1,500,000 | $250,000 (Auto) | $1,250,000 | $200 – $300 |
| Guest Injured on Property | $800,000 | $300,000 (Homeowners) | $500,000 | $200 – $300 |
| Defamation Lawsuit | $600,000 | $0 (Often not covered by standard) | $600,000 | $200 – $300 |
That annual premium looks very reasonable when you consider what you’re protecting against. Without umbrella coverage, you’d be personally responsible for the massive gaps between what your standard policies cover and what you owe.
For deeper insights into the financial aspects, explore these resources:
How Much Does an Individual Umbrella Insurance Policy Cost?
Individual umbrella insurance is budget-friendly. Most families pay between $200 and $300 annually for $1 million in coverage, with some policies starting even lower. You’re protecting your entire financial future for less than many people spend on coffee each month.
Your specific premium depends on your coverage amount and risk profile. A $2 million policy costs more than $1 million, but the increases are modest. Factors like teenage drivers, rental properties, or a swimming pool might slightly increase your premium.
Location matters too. In Virginia and North Carolina, rates can vary based on local claim patterns. The best savings often come from bundling discounts. At Strange Insurance Agency, we work with over 30 companies to find you the best bundling opportunities and overall value.
We’re committed to helping you find affordable, quality protection:
Coverage Limits and Prerequisites
Individual umbrella insurance typically starts at $1 million in coverage and can extend to $10 million or more, usually in $1 million increments. Choosing the right amount isn’t just about your current assets—consider your future earning potential, too. A good starting point is coverage that matches or exceeds your total net worth.
Before you can get umbrella coverage, insurers require substantial liability limits on your underlying policies. For auto insurance, you’ll typically need at least $250,000 per person and $500,000 per accident for bodily injury liability. Your homeowners insurance usually needs at least $300,000 in personal liability coverage.
When choosing your limit, think beyond today’s bank account. Consider your career trajectory and the lifestyle you’re building. A young professional with high earning potential might benefit from more coverage than their current net worth suggests.
For detailed guidance on coverage limits, these resources offer valuable insights:
- Personal Umbrella and Excess Liability Insurance
- 1 Million Dollar Umbrella Policy
- 5 Million Dollar Umbrella Policy
Frequently Asked Questions about Individual Umbrella Insurance
At Strange Insurance Agency, we get thoughtful questions about individual umbrella insurance from clients across Virginia, North Carolina, and the U.S. These are the most common.
Can I get an umbrella policy without owning a home?
Absolutely! This is a common question from renters. Individual umbrella insurance works just as well for renters as for homeowners. Instead of homeowners insurance, your renters insurance policy becomes the underlying coverage.
You’ll still need to meet minimum liability limits, but once you do, you’re all set. This protection is especially important for renters with significant assets or future earnings to protect. A lawsuit doesn’t care if you rent or own; your financial exposure is the same. We help renters explore standalone umbrella options for their specific situation.
For more details, check out: Umbrella Insurance Without Homeowners.
Are legal defense costs included in my coverage limit?
This is one of the best features of individual umbrella insurance. In most cases, your legal defense costs and attorney fees are paid in addition to your policy’s liability limit, not subtracted from it.
This means if you have a $1 million umbrella policy, you won’t watch that money disappear paying lawyers. The policy covers your legal defense separately, preserving the full coverage amount for any judgment or settlement.
Even better, your umbrella policy will typically defend you even when a lawsuit is groundless or fraudulent. We’ve seen cases where frivolous lawsuits still incur tens of thousands in legal fees. Your individual umbrella insurance steps in to handle those costs, protecting you from the expense of litigation.
Does my umbrella policy cover incidents that happen outside the country?
Yes, and this is a standout feature. Most individual umbrella insurance policies offer worldwide coverage, protecting you whether you’re at home in Richmond, visiting family, or traveling abroad.
If you’re found liable for an incident while traveling internationally, your umbrella policy can provide protection. This worldwide coverage typically includes the U.S., Canada, and most other international destinations.
This benefit provides genuine peace of mind for frequent travelers. We always recommend confirming the specific geographic scope with your Strange Insurance Agency advisor to ensure it aligns with your lifestyle.
Conclusion: Secure Your Future with the Right Protection
You’ve spent years building your dream life—saving for a home, planning for retirement, and securing your family’s future. A single unexpected event, like a car accident or an injury on your property, could jeopardize it all. Without proper protection, one lawsuit could wipe out everything you’ve worked for.
This is why individual umbrella insurance is essential. For less than a dollar a day, you can protect millions in assets and future earnings. It’s one of the smartest financial decisions you can make.
Umbrella coverage goes far beyond standard policies. While your auto and home insurance have limits, today’s lawsuits regularly exceed them. Individual umbrella insurance shields your assets from major bodily injury and property damage claims, protects you from personal injury accusations like libel and slander, and even travels with you worldwide. The peace of mind that comes with knowing you’re truly protected is priceless.
At Strange Insurance Agency, we’ve seen how the right coverage makes all the difference. We’re your neighbors in Virginia and North Carolina, and we understand the unique risks in our communities. Our concierge service means you get personalized attention, not a one-size-fits-all approach.
We access over 30 top-rated companies to shop the market for you, finding the best coverage at the best price. We craft comprehensive insurance portfolios that make sense for your life, whether you’re a young professional, a family with teen drivers, or someone with significant assets.
The bottom line is simple: you can’t predict life’s curveballs, but you can be ready. Don’t let a sudden storm soak your financial security when protection is so affordable.
Ready to get started? We make it easy. Get a quote for your personal insurance needs today and find what true peace of mind feels like.