
Why Esthetician Insurance is a Must-Have for Your Business
Understanding insurance for estheticians is key to protecting your beauty business from unexpected risks. If you’re wondering what this type of insurance covers, here’s a quick overview:
- What is Insurance for Estheticians?
- It is specialized coverage designed to protect estheticians and their businesses from financial losses due to accidents, negligence claims, or property damage.
- Key Coverage Types:
- General Liability Insurance: Protects against claims of client injury (like a slip and fall) or damage to client property.
- Professional Liability Insurance (Malpractice/E&O): Covers claims related to professional mistakes, such as an adverse reaction to a treatment.
- Business Owner’s Policy (BOP): Bundles general liability with commercial property insurance, often at a lower cost.
- Workers’ Compensation Insurance: Required if you have employees and covers their work-related injuries or illnesses.
Working as an esthetician means helping clients look and feel their best. But even with the highest care, accidents can happen. A client might have an unexpected reaction to a product. Or they could trip and fall in your salon. These incidents can lead to expensive lawsuits. Having the right insurance means your business is protected. It safeguards your finances and lets you focus on your passion.
With over 15 years in treasury management, business consulting, and insurance, Christian Strange brings a deep understanding of financial protection to insurance for estheticians. His expertise helps businesses like yours steer risks and achieve peace of mind.
Insurance for estheticians terms to learn:
- insurance for beauty professionals
- liability insurance for professionals
- general liability insurance for independent contractors
As estheticians, you are dedicated to enhancing your clients’ personal appearance through a variety of skin treatments, from facials and waxing to microdermabrasion and advanced skincare. While your goal is always to provide exceptional service, the nature of your work inherently involves risks. That’s why esthetician insurance isn’t just a good idea—it’s a critical component for safeguarding your livelihood and reputation.
Imagine a scenario where a customer slips and becomes injured while in your salon, or perhaps they have an unexpected allergic reaction to a product you used. These aren’t just minor inconveniences; they can lead to significant financial losses, legal fees, and damage to your professional standing. Without adequate protection, your business could face severe setbacks or even closure.
Beyond protecting against unforeseen incidents, having comprehensive esthetician insurance demonstrates your commitment to professionalism and client safety. Many salon or spa owners, and even landlords, require proof of specific insurance coverage before you can operate. It’s a testament to your responsibility and provides peace of mind not only for you but also for your clients.
We understand that navigating insurance can seem complex. That’s why we’re here to simplify it for you. We believe that securing your business should be as seamless as possible, allowing you to focus on what you do best: making people feel beautiful. For more general information about protecting your business, explore our resources on Business Liability Insurance.
What is Esthetician Insurance?
At its core, esthetician insurance is a specialized form of business insurance custom to the unique risks faced by skincare professionals. It’s not a one-size-fits-all solution; instead, it comprises several types of coverage designed to address specific exposures in the beauty industry. Whether you’re an independent contractor renting a booth, a sole proprietor running your own studio, or a salon owner with multiple employees, the right insurance acts as your financial safety net.
This specialized coverage helps you manage the inherent risks of your profession, protecting your assets, covering treatment-related claims, and ensuring your business can continue to thrive even when faced with unexpected challenges. It protects you from the costs associated with claims of injury, property damage, or professional mistakes that could occur during your services.
The Importance of Protecting Your Practice
No matter how experienced or careful you are, accidents can happen. A client might claim a chemical peel caused a burn, or perhaps they experience an allergic reaction to a new product. These situations, while hopefully rare, can lead to costly client claims. For example, if a client claims a treatment caused harm, professional liability insurance can help cover the expenses. Similarly, if you accidentally spill hot wax on a client’s expensive shoes, general liability insurance might step in to cover the damage to their property.
Protecting your practice means being prepared for these possibilities. It means having the financial backing to handle legal fees, medical expenses, or settlement costs, rather than shouldering them yourself. It’s about safeguarding your hard-earned business from the unpredictable nature of human interactions and unforeseen events.
Core Insurance Policies Every Esthetician Needs

When it comes to building a robust shield for your esthetics business, certain insurance policies form the foundational layers. These are the coverages that most estheticians, whether independent or salon owners, will find essential. Often, you can even bundle several of these policies together for comprehensive protection and potential cost savings.
General Liability Insurance: Your First Line of Defense
Think of General Liability (GL) insurance as your everyday “slip-and-fall” coverage. It’s designed to protect your business from common third-party claims of bodily injury or property damage that occur on your premises or as a result of your business operations.
For an esthetician, this could manifest in several ways:
- Slip and Fall: A client slips on a freshly mopped floor near a workstation and gets injured. GL insurance can help cover their medical expenses and legal fees if they decide to sue.
- Client Injury (non-treatment related): A client trips over a loose rug in your waiting area and sprains an ankle.
- Property Damage: You accidentally spill water on a client’s designer handbag, damaging it beyond repair. GL can cover the cost of replacement or repair.
- Advertising Injury: Less common but still relevant, this covers claims of libel, slander, or copyright infringement in your advertising.
- Product Liability: While professional liability often covers claims related to your service, GL can sometimes include product liability for claims stemming from products you sell (e.g., a client has an allergic reaction to a skincare product purchased from your salon).
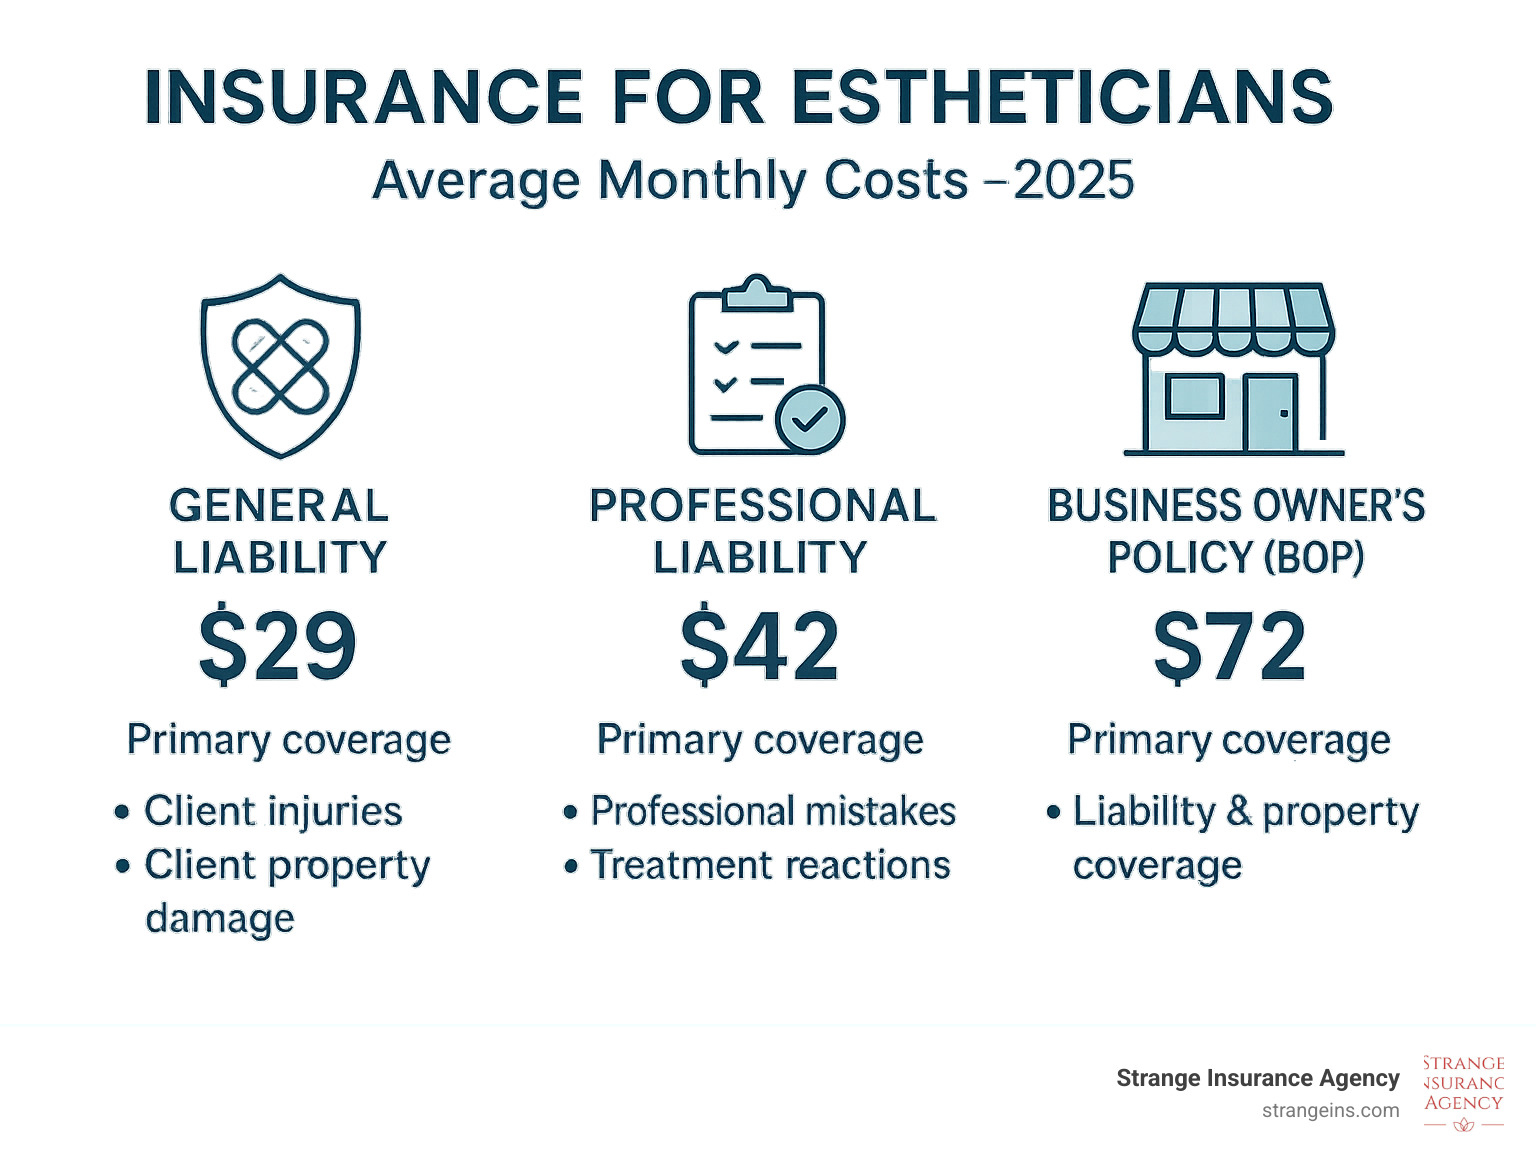
General liability insurance costs an average of $29 per month. It’s a critical layer of protection for any business that interacts with the public. To learn more about how this applies to independent professionals, check out our guide on General Liability Insurance for Independent Contractors.
What is Professional Liability Insurance for Estheticians?
While General Liability handles everyday accidents, Professional Liability insurance, often called “malpractice insurance” or “Errors & Omissions (E&O) insurance,” specifically addresses claims related to your professional services. This is where the specialized nature of insurance for estheticians truly shines.
Professional liability protects you from financial losses due to claims of:
- Negligence: A client claims your treatment was performed negligently, leading to an adverse outcome.
- Failure to Deliver Promised Results: A client alleges that a treatment did not achieve the results you guaranteed.
- Incorrect Treatments: You recommend or perform a skincare treatment that is later deemed unsuitable for the client’s skin type, causing irritation or damage.
- Misinformation or Bad Advice: A client claims they suffered harm because they followed your professional advice.
For example, if a client claims a chemical peel caused a burn, professional liability can help cover expenses like legal fees, settlements, or judgments. This coverage is absolutely vital for estheticians because your services directly impact a client’s appearance and well-being. Professional liability insurance costs an average of $42 per month. You can find more detailed information specifically for beauty professionals on our page about Esthetician Liability Insurance.
Business Owner’s Policy (BOP): The All-in-One Solution
A Business Owner’s Policy (BOP) is a fantastic option for many estheticians, especially if you own your salon space or have significant business property. A BOP bundles two critical coverages—General Liability and Commercial Property insurance—into a single, often more affordable policy. This combination typically costs less than purchasing the policies separately.
Here’s how a BOP works for estheticians:
- General Liability: As discussed, this covers third-party bodily injury and property damage claims.
- Commercial Property Insurance: This protects your physical business assets. This includes your salon space (if you own it), equipment (e.g., facial machines, steamers, microdermabrasion devices), furniture, inventory of products, and even improvements you’ve made to a leased space. For instance, if a burst pipe causes water damage to your expensive facial machines, or if your salon suffers vandalism, commercial property insurance can help with replacement costs. It can also help with loss of business income while your property is being repaired.
A BOP often includes additional perks like business interruption insurance, which can help cover lost income and operating expenses if your business has to temporarily close due to a covered property loss. A Business Owner’s Policy (BOP) costs an average of $72 per month.
Here’s a quick comparison of these core coverages:
| Policy Type | Primary Coverage | What it Protects Against |
|---|---|---|
| General Liability | Third-party bodily injury and property damage | Client slips and falls, accidental damage to client property, advertising injury. |
| Professional Liability | Claims of negligence or mistakes in professional services | Adverse reactions to treatments, alleged ineffective treatments, professional errors. |
| Business Owner’s Policy | General Liability + Commercial Property | All of the above, plus damage to your business property (equipment, inventory, salon space). |
This bundled approach makes a BOP a highly recommended choice by insurance agents for its increased coverage and affordability. For salon owners, this is particularly beneficial. Learn more about comprehensive options for your business on our page about Insurance for Beauty Salon.
Understanding the Cost of Insurance for Estheticians

Let’s talk about the elephant in the room: what does insurance for estheticians actually cost? It’s one of the first questions we get, and honestly, we wish we could give you a simple answer. But here’s the thing—your premium is as unique as your business.
Think of it this way: a solo esthetician offering basic facials in a small North Carolina town will pay very different rates than someone running a full-service medical spa in downtown Charlotte with advanced laser treatments. Both need protection, but their risk profiles are worlds apart.
The good news? Most estheticians find that quality coverage is more affordable than they expected. When you consider the potential cost of even one lawsuit or claim, those monthly premiums start looking like a pretty smart investment. We work with over 30 carriers to find you competitive rates without cutting corners on the coverage you actually need. For budget-conscious business owners, check out our guide on Cheap Esthetician Insurance.
Key Factors That Influence Your Premium
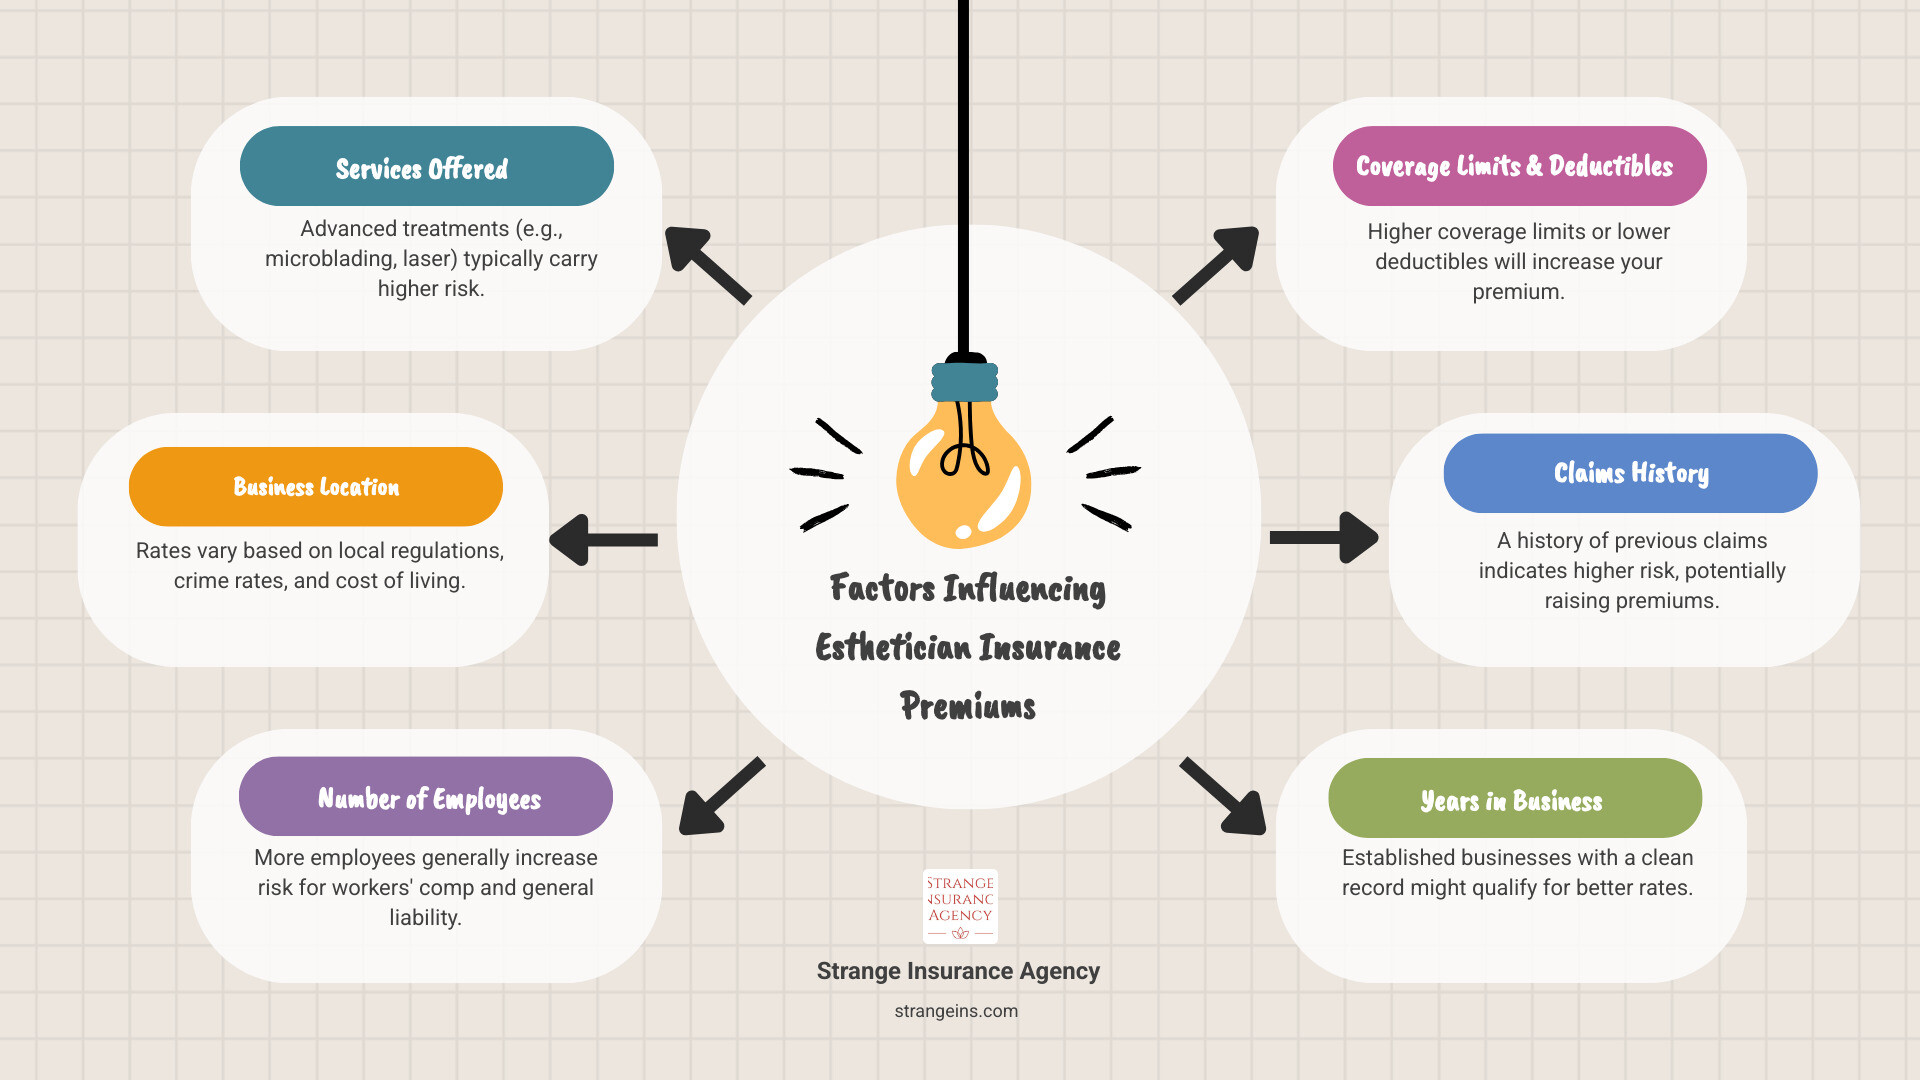
Your insurance premium isn’t pulled out of thin air. Several key factors determine what you’ll pay, and understanding them can help you make informed decisions about your coverage.
The services you offer make the biggest difference in your rates. Basic facials and eyebrow waxing carry less risk than chemical peels or microneedling. If you’re performing advanced treatments like laser hair removal or offering injectables, expect higher premiums. Insurance companies see these services as having greater potential for adverse reactions or complications.
Where you work matters more than you might think. A salon in Virginia Beach faces different risks than one in rural Virginia. Local crime rates, natural disaster risks, and even the local legal climate can affect your rates. Urban areas often have higher premiums due to increased liability exposure and higher property values.
Your team size directly impacts your costs, especially for workers’ compensation coverage. Solo practitioners pay less than salon owners with multiple employees. Each additional team member increases your exposure to workplace injuries and related claims.
Coverage limits and deductibles give you some control over your premium. Choosing higher liability limits—say $2 million instead of $1 million—increases your premium but provides much better protection for serious claims. Similarly, accepting a higher deductible can lower your monthly costs if you’re comfortable with more out-of-pocket risk.
Your business history tells insurers a lot about your risk level. A clean claims record and several years in business can help you qualify for better rates. New businesses often pay slightly more until they establish that track record of safe operations.
Average Costs for Essential Coverages
Here’s what most estheticians can expect to pay for their core insurance needs. These are averages—your actual costs might be higher or lower based on your specific situation.
General liability insurance typically runs about $29 per month. This covers those everyday risks like client slip-and-falls or accidental property damage. It’s your basic protection against third-party claims.
Professional liability insurance averages $42 monthly. This is your shield against claims related to your actual treatments—things like alleged negligence or adverse reactions to services you provided.
A Business Owner’s Policy (BOP) costs around $72 per month but gives you the most bang for your buck. It bundles general liability with commercial property coverage, often saving you money compared to buying them separately.
Workers’ compensation runs about $72 monthly on average, though this varies significantly based on your payroll and state requirements. If you have employees, this coverage is typically mandatory.
Cyber insurance averages $145 monthly, while commercial auto insurance runs around $147 per month if you need vehicle coverage for your business.
Want to keep your insurance for estheticians costs manageable? Bundling policies is often your best bet—that BOP we mentioned can save you serious money. Smart risk management practices like maintaining impeccable sanitation, using proper client consent forms, and keeping your workspace safe can help prevent claims and potentially lower your rates over time.
Consider choosing a higher deductible if you can handle more upfront costs in exchange for lower monthly premiums. Most importantly, compare quotes from multiple carriers. That’s where we come in—we do the shopping for you, comparing options from dozens of insurers to find your best value. And of course, maintaining a clean claims history keeps you in good standing with insurers for years to come.
Specialized Coverage for a Growing Esthetics Business
As your esthetics business blossoms, so do the opportunities! Perhaps you’re ready to offer exciting new treatments, welcome more talented team members, or even manage more client information digitally. This growth is fantastic, but it also means your business might face new kinds of risks. That’s where specialized insurance for estheticians comes in, offering protection custom to your evolving needs. For a broader look at coverage for beauty professionals, check out our resources on Insurance for Beauty Professionals.
When is Workers’ Compensation Required?
If your esthetics business starts to grow with employees, Workers’ Compensation insurance becomes a near-certain requirement. Most states, including Virginia, North Carolina, West Virginia, and Florida, have laws that make this coverage mandatory once you hire even one employee. Because rules can vary, it’s always good to check your specific state’s requirements. You can find more information on state-specific laws from the U.S. Department of Labor.
Think of Workers’ Comp as a safety net for your team. It helps pay for medical expenses and a portion of lost wages if an employee gets hurt or becomes ill because of their job. For example, if a team member slips on a wet floor and twists an ankle, or develops carpal tunnel syndrome from repetitive work, this policy steps in. It covers their medical care and can provide financial support while they recover.
While generally required for employees, some sole proprietors might consider it for themselves in certain situations or if contracts demand it. Just remember, correctly classifying your team (are they employees or independent contractors?) is super important. Getting this wrong can lead to big headaches and penalties. Also, having a strong plan to keep your workplace safe can even help you save on Workers’ Comp costs over time.
What Additional Insurance for Estheticians Should You Consider?
Beyond your essential policies, there are several other smart insurance choices that can give your thriving esthetics business an extra layer of security:
- Commercial Property Insurance (standalone): If you own your salon space, or if your Business Owner’s Policy (BOP) doesn’t fully cover your valuable items, a standalone Commercial Property policy offers more robust protection. This covers your building, all your expensive equipment (think laser machines, facial steamers), furniture, and product inventory against dangers like fire, theft, or vandalism. It’s about protecting the physical heart of your business.
- Equipment Breakdown Insurance: This often-overlooked coverage is a real lifesaver for estheticians. It protects against sudden and unexpected mechanical or electrical failures of your essential machines. If your high-tech facial machine suddenly stops working, or your HVAC system quits, this policy can help cover the repair or replacement costs. Regular property insurance often won’t cover these specific “breakdown” issues.
- Cyber Liability Insurance: As an esthetician, you likely handle sensitive client data online – personal information, health details, and payment information. This makes your business a target for cyberattacks. Cyber insurance helps you recover financially after a data breach. It can cover costs like telling your customers about the breach, offering credit monitoring, public relations expenses, and any legal fees that pop up. It’s peace of mind in our digital world.
- Commercial Auto Insurance: Do you use a vehicle for business? Maybe you transport supplies, travel between different client locations, or make product deliveries. If so, you’ll need Commercial Auto Insurance. This policy covers property damage, medical costs, and legal defense if an accident involves a business vehicle. Even if you use your personal car for work, you might need “hired and non-owned auto insurance (HNOA)” to cover liabilities when you or your employees use personal, rented, or leased vehicles for business tasks.
- Business Interruption Insurance: While often part of a BOP, you can also get this coverage separately. Think of it as income protection for your business. If a covered property loss (like a fire or major storm damage) forces your salon to close temporarily, this policy helps replace your lost income and covers ongoing operating expenses like rent and payroll. It helps ensure your business can bounce back without financial strain.
Considering these additional coverages means you’re prepared for a wider range of potential bumps in the road. It allows your esthetics business to keep operating with greater security and confidence, no matter what comes your way.
How to Get Your Esthetician Insurance Policy
Getting your esthetician insurance policy doesn’t have to be a complicated task that takes you away from perfecting a client’s glow. In fact, we’ve made the process incredibly straightforward and quick! Our goal is to get you covered with minimal fuss, so you can get right back to doing what you love most.
The journey usually involves just a few simple steps: getting a personalized quote, reviewing the options that fit your unique needs, and then easily purchasing the policy that gives you the best peace of mind. Many insurers can even provide you with proof of coverage within 24 hours of your application, meaning you get that immediate sense of security almost instantly.
Information Needed for a Quote
To get an accurate and custom esthetician insurance quote, we’ll need a little bit of information about your wonderful business. Think of it as helping us paint a clear picture of your unique risk profile, so we can craft the very best coverage options just for you.
Generally, you’ll want to have details like your business name and legal structure (are you a sole proprietor, an LLC, or a corporation?). We’ll also need your location(s) – whether that’s a busy salon in Norfolk, VA, or a cozy studio in a different state. Be ready to share the specific services you provide, especially any advanced treatments that might carry different risks. We’ll also ask about the number of employees you have, if any, and your estimated annual revenue. Finally, knowing your years in business and any past claims history helps us find you the most competitive rates. Having these details handy will make the quote process super smooth and speedy! For a deeper dive into what goes into getting liability coverage quotes, hop over to our page on Liability Insurance Quotes.
Receiving Your Certificate of Insurance (COI)
Once you’ve chosen and purchased your esthetician insurance policy, you’ll receive a very important document: your Certificate of Insurance, or COI. This isn’t just a piece of paper; it’s your official proof that your business is fully covered.
You’ll find your COI comes in handy for a number of reasons. Your landlord will almost certainly ask for it before you sign a lease or set up shop. Some clients, especially those opting for advanced services or corporate contracts, might also request to see proof of your insurance. Plus, if you partner with other vendors or suppliers, they might need to see your COI as well. Beyond all these practical uses, simply having your COI in hand provides immense peace of mind, knowing your hard work is protected.
The best part? With today’s technology, you can often access your COI 24/7 through a secure web portal or mobile app. This means you can download it instantly, or send it via email or text whenever it’s needed, usually without any extra cost and with unlimited certificates. This digital convenience ensures your proof of coverage is always right at your fingertips!
Conclusion
Running a successful esthetics practice means balancing your passion for helping clients look and feel their best with the practical realities of protecting your business. Throughout this guide, we’ve walked through why insurance for estheticians isn’t just another business expense—it’s your financial safety net and professional peace of mind rolled into one.
The foundation starts with General Liability Insurance to protect against everyday accidents, while Professional Liability Insurance shields you from claims related to your treatments and services. For many estheticians, a Business Owner’s Policy offers the sweet spot of comprehensive coverage at an affordable price by bundling these essential protections together.
As your business grows, you might find yourself needing Workers’ Compensation for employees, Cyber Liability for digital protection, or Commercial Auto coverage for business vehicle use. The beauty of working with an experienced agency is that we can help you steer these decisions as your needs evolve.
The costs we’ve discussed—from $29 per month for General Liability to $72 for a comprehensive BOP—represent a small investment compared to the potential financial devastation of a single uninsured claim. Factors like your services offered, business location, and coverage limits all influence your premiums, but there are practical ways to manage these costs through bundling and smart risk management.
At Strange Insurance Agency, we understand that every esthetician’s situation is unique. Whether you’re a solo practitioner in Norfolk or running a busy salon in Charlotte, we’re here to simplify the insurance process for you. As a concierge insurance agency, we help estheticians in Virginia, North Carolina, and across the U.S. find the right protection by comparing quotes from over 30 top carriers.
Your expertise lies in skincare and client care—ours lies in protecting what you’ve built. Don’t wait until an accident happens to find the gaps in your coverage. Take the proactive step today to secure your business’s future. Get a quote for your business insurance and let us help you focus on what you do best: making people feel beautiful and confident.