
Understanding Personal Umbrella Insurance Costs
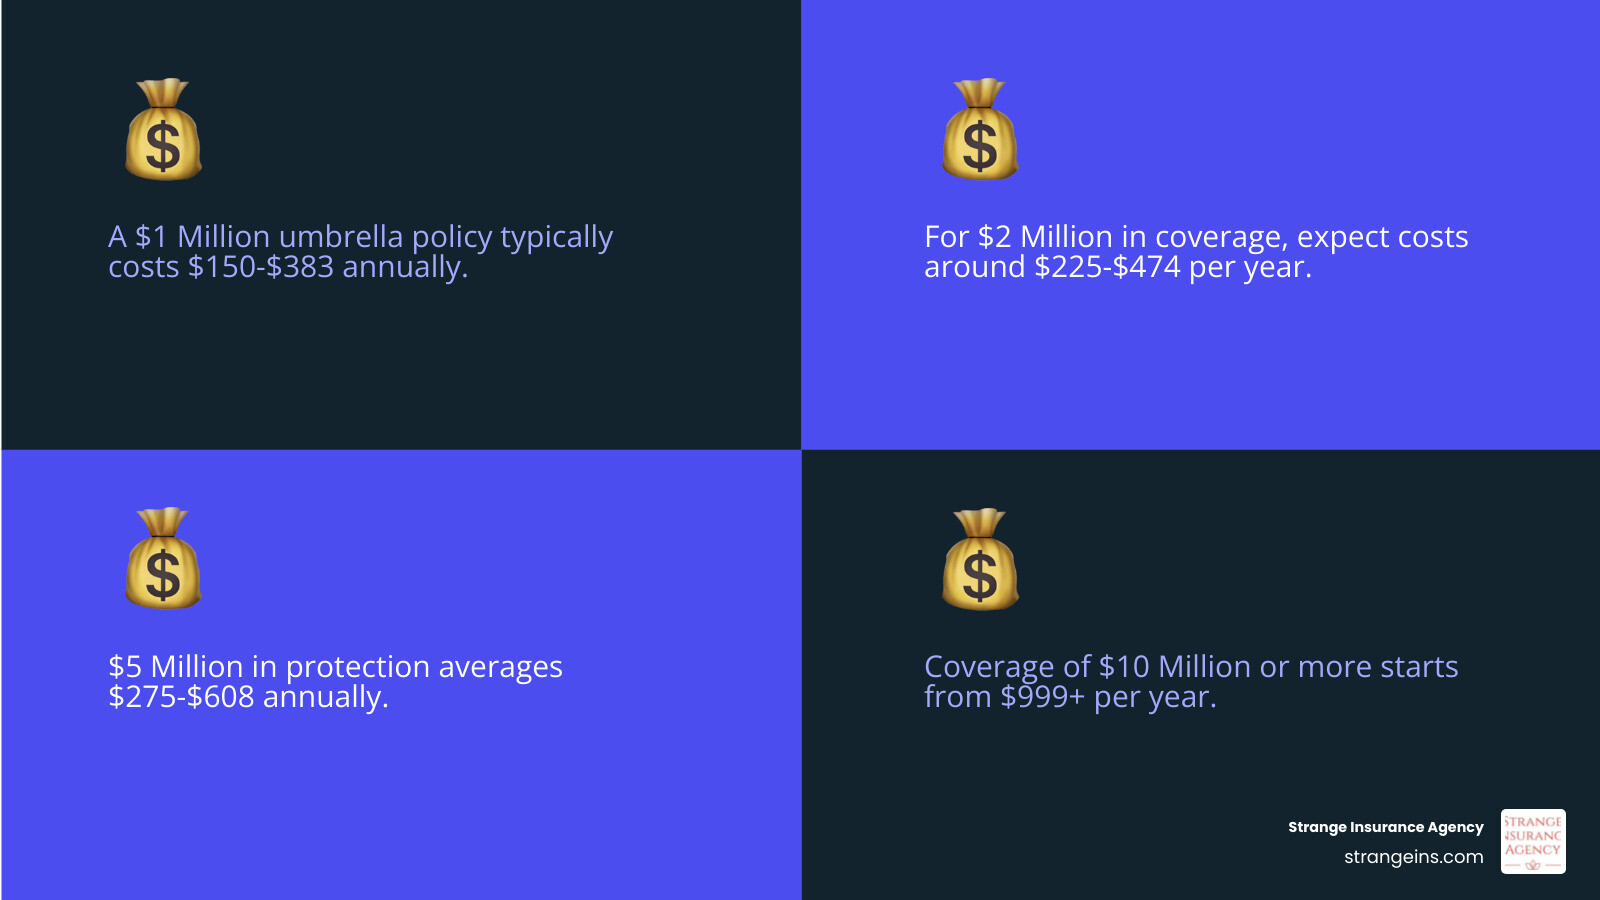
Personal umbrella insurance cost typically ranges from $150 to $500 annually for $1 million in coverage, making it an affordable way to dramatically increase your liability protection. Here’s a look at average annual costs:
- $1 Million Coverage: $150-$383 per year
- $2 Million Coverage: $225-$474 per year
- $5 Million Coverage: $275-$608 per year
- $10 Million Coverage: $999+ per year
The exact cost depends on your risk factors, such as the number of homes and cars you own, your driving record, and whether you have features like pools or teen drivers.
Personal umbrella insurance is a financial safety net that activates when a lawsuit or claim exceeds the liability limits of your home or auto insurance. According to Insurance Information Institute data, 13% of personal injury awards reach $1 million or more, making this extra protection the difference between a manageable claim and losing your life savings.
This coverage isn’t just for the wealthy. Anyone with assets to protect—including your home, savings, and future earnings—should consider it. The peace of mind it provides often costs less than a monthly coffee budget.
I’m Christian Strange. With over 15 years in insurance, I’ve seen how the right umbrella policy can provide millions in coverage for a surprisingly low cost, protecting families from financial ruin.
Personal umbrella insurance cost word guide:
What an Umbrella Policy Covers (and What It Excludes)
An umbrella policy is your financial backstop for major liability claims. It works with your existing home and auto insurance, kicking in when their liability limits are exhausted. Crucially, it also broadens your protection, covering situations that your standard policies might not.
Typical Coverages
Your umbrella policy covers a wide range of liability situations:
- Bodily Injury: Covers costs that exceed your auto or home policy limits if you’re at fault in an accident that injures someone. This includes medical bills, lost wages, and pain and suffering awards.
- Property Damage: Pays for damages to someone else’s property that exceed your underlying policy limits, such as in a major car accident.
- Personal Injury: This is a key benefit, covering claims your other policies often exclude, such as slander (spoken defamation), libel (written defamation), and false arrest.
- Landlord Liability: Provides crucial protection if you’re a landlord and a tenant or guest is injured on your rental property. Learn more in our guide to Landlord Umbrella Insurance.
- Legal Defense Costs: Covers attorney fees and other legal expenses for a covered claim, often without reducing your liability limit.
For a complete overview, visit our Personal Umbrella Insurance Coverage page.
Common Exclusions
Umbrella policies don’t cover everything. Key exclusions include:
- Your Own Injuries and Property Damage: Your health, auto, and homeowners insurance are designed to cover your own losses.
- Business-Related Losses: Liability from your business or professional activities requires separate commercial insurance.
- Intentional or Criminal Acts: Insurance is for accidents, not deliberate harm or illegal activities.
- Contractual Liability: Liability you assume under a contract is generally not covered.
These exclusions help keep the Personal umbrella insurance cost affordable by focusing on common and severe personal liability risks.
Umbrella vs. Excess Liability Insurance
While often used interchangeably, these are different. Excess liability insurance simply adds a higher dollar limit to your existing coverage. Umbrella insurance is more powerful: it not only increases your limits but also broadens coverage to include risks like libel or slander that your underlying policies may not cover.
This broader protection is why umbrella policies typically offer superior value. Learn more on our Personal Excess Liability page.
Key Factors That Determine Your Personal Umbrella Insurance Cost
Your Personal umbrella insurance cost is based on your unique risk profile, but even for those with higher risks, the coverage remains remarkably cost-effective.
Insurers assess the likelihood that you might face a large liability claim. This assessment, along with your chosen coverage amount and underlying policy limits, determines your premium.
Your Desired Coverage Limit
The coverage amount you select is the biggest factor in your premium, but the cost doesn’t scale linearly. A $1 million policy typically costs $150-$383 annually. Doubling that to a $2 million policy might only increase the cost to $225-$474 per year. A $5 million policy often runs just $275-$608 annually.
This incremental pricing makes higher limits surprisingly affordable, providing a significant financial cushion for a small additional cost. Our guide on Recommended Umbrella Insurance Coverage can help you choose the right amount.
Your Personal Risk Profile
Your lifestyle and assets influence your premium. Common factors include:
- Teen drivers: Statistically increase accident risk significantly.
- Attractive nuisances: Features like swimming pools, trampolines, and hot tubs.
- Multiple properties and vehicles: More properties and cars increase your overall exposure.
- Dog ownership: Certain breeds may be considered higher risk.
- Driving record: A history of tickets or at-fault accidents will affect your rate.
- Public profile: High-profile individuals may face increased risks of claims like slander or libel.
Your Underlying Policy Limits
Umbrella insurance requires you to have a certain amount of liability coverage on your base policies first. These minimums are typically:
- Auto Insurance: $250,000 per person / $500,000 per accident for bodily injury, and $100,000 for property damage.
- Homeowners Insurance: $300,000 to $500,000 in personal liability coverage.
Increasing your underlying limits can sometimes lower your Personal umbrella insurance cost, as it reduces the initial risk for the umbrella insurer. Understanding how your Umbrella Auto Policy and Umbrella Homeowners Insurance interact is key to cost-effective protection.
How Much Does Personal Umbrella Insurance Cost on Average?
Personal umbrella insurance cost is surprisingly affordable for the amount of protection it provides. Most people can secure $1 to $2 million in liability coverage for about $380 per year—roughly a dollar a day to safeguard your financial future.
Considering that a single major lawsuit can threaten everything you’ve worked for, this small annual investment is one of the best values in insurance.
The Average Personal Umbrella Insurance Cost for a $1 Million Policy
A $1 million umbrella policy typically costs between $150 and $383 per year. According to industry research, a household with one home and two cars pays around $383 annually. For less than a typical monthly phone bill, you can add a million dollars of liability protection over your existing policies.
Your exact cost will vary by location and risk factors, but it remains a small price for substantial peace of mind. Learn more about what’s included with a 1 Million Umbrella Policy and its 1 Million Umbrella Policy Cost.
The Average Personal Umbrella Insurance Cost for a $5 Million Policy
Higher coverage limits offer even better value. A $5 million policy averages around $608 per year for the same typical household. The cost does not increase proportionally; each additional million in coverage costs significantly less than the first. This incremental pricing makes high levels of protection accessible for families with significant assets or higher risks.
Our guide on the 5 Million Dollar Umbrella Policy explores when this level of coverage is appropriate.
Is an Umbrella Policy Worth the Price?
Absolutely. When you compare the low Personal umbrella insurance cost to the potential financial devastation of a major lawsuit, the decision is clear. A severe car accident, a slip-and-fall on your property, or even a social media post can lead to claims that exceed your standard policy limits. An umbrella policy ensures that one unfortunate event doesn’t wipe out your savings, home, and future earnings.
The peace of mind alone is worth the premium. See our full analysis on whether Umbrella Policies Worth It.
Do You Need an Umbrella Policy and How Much Coverage is Enough?
The decision to get umbrella insurance depends on your net worth, future earning potential, and lifestyle. It’s not just about protecting what you own today, but also what you could lose tomorrow, such as decades of future income.
Who Should Consider Umbrella Insurance?
Umbrella insurance is particularly valuable for:
- Asset owners: To protect homes, savings, and investments.
- Families with teen drivers: To cover the significantly higher accident risk.
- Owners of “attractive nuisances”: Such as pools, trampolines, or hot tubs.
- Dog owners: Especially of breeds considered higher risk by insurers.
- Landlords: To cover liability from rental properties.
- High earners: To protect future wages from garnishment.
- Public figures & community leaders: Who face higher risks of personal injury claims like libel or slander.
- Frequent entertainers: Hosting parties increases liability exposure.
For help determining your needs, see our guides on How Much Umbrella Insurance Do I Need? and why You Need an Umbrella.
When Might Umbrella Insurance Not Be Necessary?
While most people benefit from an umbrella policy, it may be less critical in rare cases. Someone with very limited assets and low future earning potential might find their underlying policies sufficient. Likewise, a person with an extremely low-risk lifestyle (no car, no home, no pets) has less exposure.
However, life is unpredictable. Given the affordable Personal umbrella insurance cost compared to the massive protection it offers, most people find the peace of mind is well worth the investment.
How to Get a Personal Umbrella Insurance Policy
Getting a personal umbrella policy is a straightforward process. We help families across Virginia, North Carolina, and beyond secure this vital coverage quickly and easily, often with a surprisingly affordable Personal umbrella insurance cost.
Requirements for an Umbrella Policy
Before issuing an umbrella policy, insurers have a few requirements:
- Underlying Policies: You must have existing auto and homeowners or renters insurance.
- Minimum Liability Limits: Your underlying policies must meet certain liability minimums, typically $250,000/$500,000 for bodily injury on your auto policy and $300,000-$500,000 on your home/renters policy. We can help you adjust your limits if needed.
- Bundling: Most insurers prefer you bundle your policies with them, which often provides a discount. However, we can also explore options for a Standalone Umbrella Policy or Umbrella Insurance Without Auto.
Steps to Get a Quote
Getting a quote is simple:
- Gather Information: We’ll collect details about your current policies, all drivers and vehicles in your household, properties you own, and any high-risk items like pools, trampolines, or boats.
- Assess Your Needs: We’ll help you determine the right coverage amount to protect your current assets and future earnings.
- Compare Options: We present clear policy options and pricing custom to your needs so you can choose the best fit.
- Review and Finalize: We’ll review the best options with you, answer all your questions, and ensure you feel confident in your choice. The entire process can often be completed in just a few days.
We are committed to making Affordable Umbrella Insurance accessible for our clients. Ready to start? Visit our Personal Liability Umbrella Policy Quote page.
Frequently Asked Questions about Umbrella Insurance
After helping many clients understand Personal umbrella insurance cost, we’ve compiled answers to the most common questions we receive.
How much does a $2 million umbrella policy cost?
A $2 million umbrella policy typically costs around $474 per year for a household with one home and two cars. This is often only about $75 more than a $1 million policy, making it a cost-effective upgrade. Your exact premium will depend on personal risk factors like teen drivers, pools, or your driving record. For more details, see our page on the Cost of 2 Million Umbrella Policy.
Can I get an umbrella policy if I don’t own a home?
Yes. You don’t need to be a homeowner. If you have renters insurance and auto insurance that meet the insurer’s minimum liability requirements, you can qualify for an umbrella policy. A lawsuit can target your savings and future wages regardless of whether you own or rent. Our guide to Umbrella Insurance Without Homeowners explains how this works.
Does a personal umbrella policy cover my business activities?
No, this is a critical distinction. A personal umbrella policy explicitly excludes liability related to business or professional activities, even for a home-based business. For that, you need separate commercial insurance, such as a business or General Liability Umbrella Insurance policy. We can help ensure you have the right coverage for both your personal and professional life.
Conclusion: Secure Your Financial Future with the Right Coverage
Understanding Personal umbrella insurance cost reveals it’s one of the smartest financial moves you can make. For a small annual premium—often just $150 to $500 for $1 million in coverage—you gain a massive layer of protection for your assets and future earnings. It’s an affordable way to secure peace of mind against life’s unexpected and costly events.
Whether it’s a serious car accident, an injury at your home, or a lawsuit from a social media comment, an umbrella policy is there to protect you. At Strange Insurance Agency, we’ve helped countless families across Virginia, North Carolina, and beyond find affordable protection.
Every family’s needs are different. We take the time to understand your unique situation to recommend the right coverage. We’ll match you with the right policy at a cost that fits your budget.
Get a Personalized Quote Today
An umbrella policy is a powerful tool for protecting the life you’ve built. We’re here to make the process simple and clear. No pressure, just honest guidance to help you make the right decision for your family.
Ready to take the next step toward complete financial protection? Learn more about our personal insurance solutions and let us help you find the umbrella coverage that fits your life perfectly.