
Why Public Liability Protection Is Essential for Your Business
Business public liability insurance protects your company from third-party injury and property damage claims, with coverage starting from just £4.95 per month and claims paid within 24 hours for 80% of cases.
Key Benefits:
- Legal Protection: Covers compensation costs and legal fees
- Wide Coverage: Available for 1,000+ trades and professions
- Flexible Limits: Choose from £1 million to £10 million coverage
- Fast Claims: 80% settled within 24 hours
- Affordable: Starting at £4.95 monthly
- Expert Support: UK-based claims team available 24/7
Slip, trip, and fall accidents cost UK businesses thousands annually. Whether you’re a builder, café owner, or consultant, public liability insurance provides essential financial protection.
As Christian Strange, with over 15 years of treasury management and insurance experience, I’ve helped countless professionals steer business public liability options through Strange Insurance Agency. We make complex insurance decisions simple and stress-free.
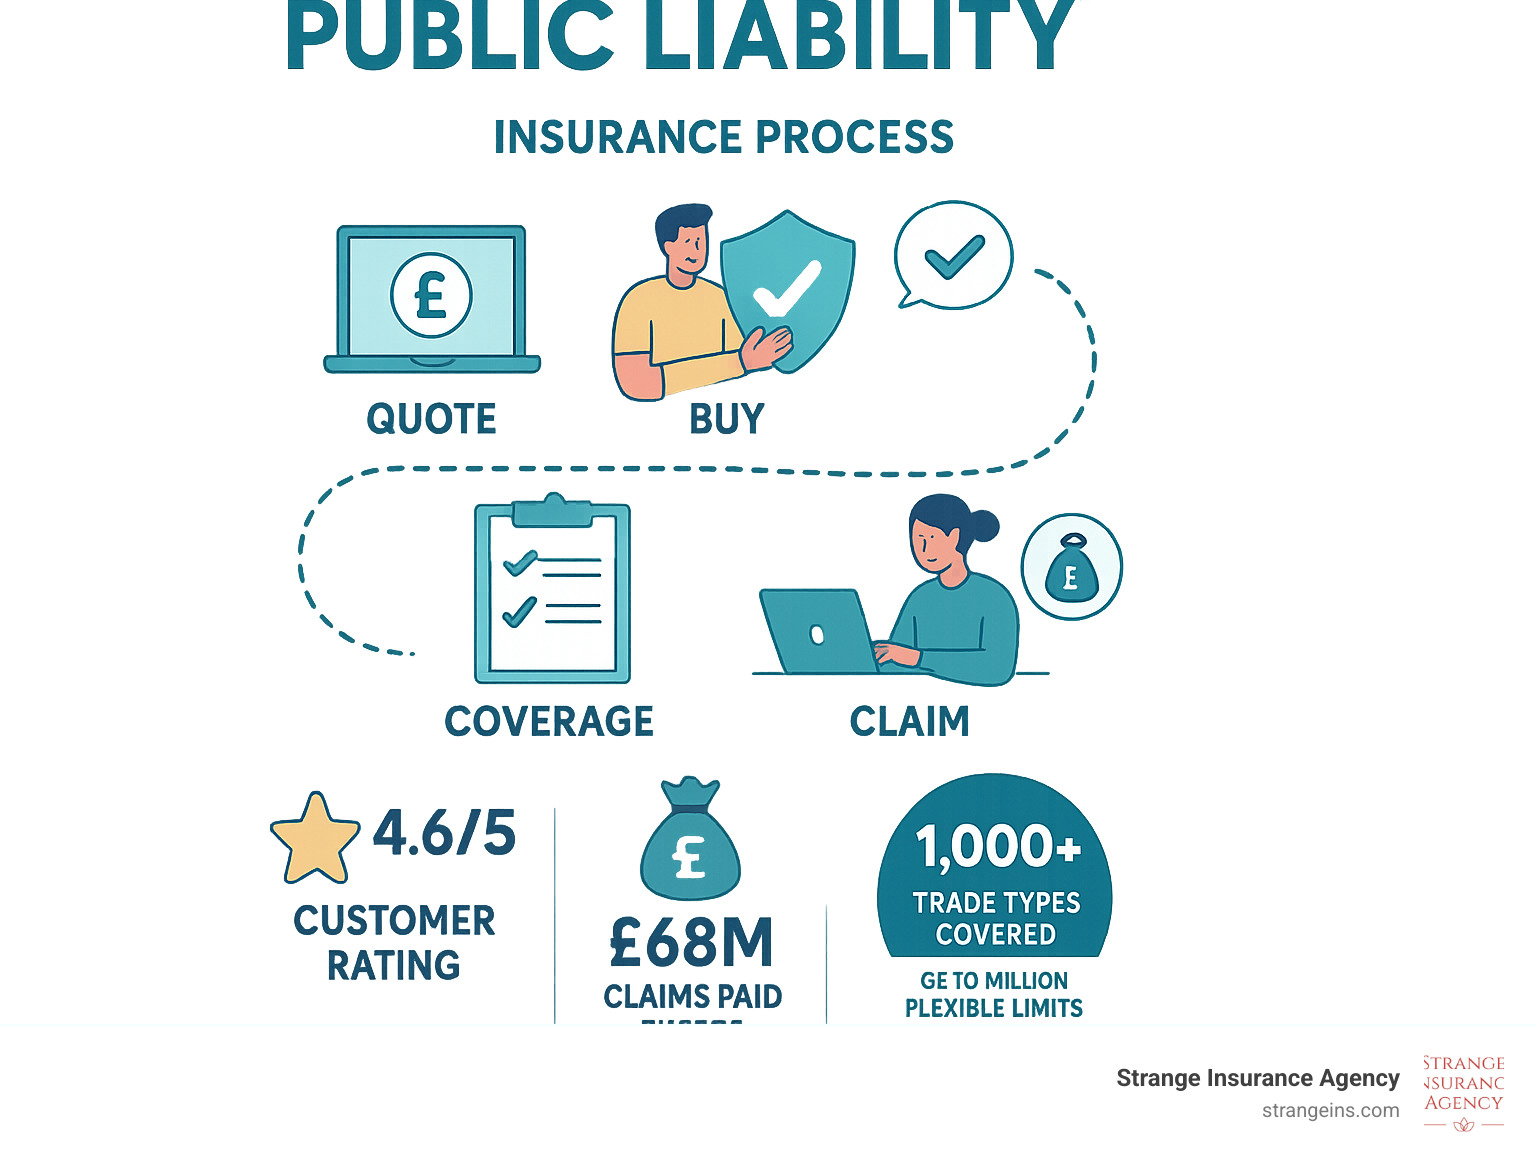
Key terms for business public liability:
What Is Public Liability Insurance and Why It Matters
Picture this: a guest slips on your café’s wet floor and breaks their wrist, or you accidentally damage expensive furniture while painting. These real risks could cost thousands without proper protection.
Simply business public liability insurance acts as your financial safety net when third-party injuries or property damage occur. This coverage protects you when someone who isn’t your employee gets hurt or has their property damaged because of your business activities.
Health and Safety Executive (HSE) statistics show workplace accidents cost UK businesses millions annually. Slip, trip, and fall incidents remain the most common workplace accidents, with single claims easily reaching tens of thousands when including medical bills, property repairs, and legal costs.
Your coverage follows you wherever business takes you – at your premises or client locations. It covers everything from customers tripping over equipment to accidentally damaging client property during service calls.
Simply Business Public Liability Defined
Simply business public liability provides comprehensive coverage that shields your business from third-party claims. It’s your business’s legal and financial protection when accidents happen.
The policy covers third-party injury compensation, property damage costs, and legal fees including court costs. Cover limits range from £1 million to £10 million, with most businesses finding £1 million adequate. Your policy excess typically runs between £100 and £500.
Modern coverage adapts to your business needs rather than offering cookie-cutter protection. You can tailor policies to match industry risks, client requirements, and budget constraints.
For comprehensive protection beyond public liability, explore our Business Insurance options or specialized Business Public Liability coverage designed for your industry’s unique risks.
7 Reasons Simply Business Public Liability Stands Out

Simply business public liability insurance delivers on seven key areas that matter most to business owners.
#1 Custom Cover for 1,000+ Trades
Modern public liability coverage understands your specific business. Whether you’re a builder, caterer, or retailer, there’s coverage designed for your trade. A roofer faces different risks than a hairdresser, and smart insurers price accordingly.
Trade selector tools help find coverage matching exactly what you do – no paying for unnecessary protection or missing coverage for actual risks.
#2 Cover From £1-10 Million – Pick Your Limit
Flexible coverage limits match protection to your needs and client requirements. Most small service businesses find £1 million coverage adequate, while construction contractors often need £2-5 million.
| Coverage Level | Best For | Monthly Cost Range |
|---|---|---|
| £1 Million | Small service businesses | £4.95-£25 |
| £2 Million | Medium businesses | £6-£35 |
| £5 Million | Large contractors | £15-£75 |
| £10 Million | Specialized industries | £25-£150 |
#3 Prices From Just £4.95 a Month
Ten percent of customers pay just £4.95 monthly for coverage up to £2 million. Your premium depends on business type, coverage limits, claims history, and annual turnover. Public liability insurance is tax-deductible, reducing your taxable profit.
#4 80% of Claims Paid Within 24 Hours
Speed matters when disaster strikes. 80% of claims paid within 24 hours comes from streamlined processes and dedicated UK-based teams. £68 million in claims were paid in 2024, with a 76% settlement rate.
#5 Easy Digital Certificate of Insurance
Digital certificate management puts proof of insurance at your fingertips 24/7. You can add additional insured parties, share certificates instantly, and never worry about losing documents. The system tracks expiration dates and sends renewal reminders.
#6 UK-Based Expert Support 24/7
Quality insurers provide phone support with knowledgeable UK-based teams, plus online chat and email support. This human touch becomes invaluable for complex claims or coverage modifications.
#7 Highly Rated by Nearly a Million Customers
A 4.6/5 rating based on nearly 40,000 reviews, with nearly one million customers, reflects real satisfaction with purchasing policies, managing coverage, and filing claims. High retention rates indicate ongoing satisfaction with ease of use and professional claim handling.
How Much Cover Do You Need & What Will It Cost?

Choosing the right simply business public liability coverage depends on several key factors. Business type plays the biggest role – consultants face different risks than roofers. Client interactions matter too – more people around means higher injury chances.
Work locations add complexity. Working at client sites creates more exposure than staying in your shop. Equipment and materials dramatically change risk levels. A graphic designer has different liability exposure than a welder.
Annual turnover influences coverage needs. Larger businesses typically need higher limits due to greater exposure. Client and contract requirements often make the decision – government contracts frequently demand £5-10 million coverage.
Public liability insurance is a tax-deductible business expense. At 20% basic rate tax, a £300 annual premium costs £240 after tax relief.
Simply Business Public Liability Cost Examples
Builder Example:
General building contractor with £150,000 annual turnover typically chooses £2 million coverage and pays £25-45 monthly.
Hairdresser Example:
Mobile hairdressing service with £35,000 annual turnover usually selects £1 million coverage and pays £8-15 monthly.
Café Example:
Small café with £200,000 annual turnover typically chooses £2 million coverage and pays £35-65 monthly.
These examples show how business type, turnover, and coverage limits determine premiums. Your actual cost depends on specific circumstances, claims history, and chosen deductible.
Claims, Certificates, and Compliance Made Simple
When you need simply business public liability insurance, the process should be straightforward. Whether filing claims or obtaining certificates, modern insurance administration removes traditional headaches.
Incidents happen to careful businesses. When they arise, understanding the claims process and having quick documentation access makes the difference between minor disruption and major crisis.
Your certificate of insurance serves as your business passport. Many customers won’t work with you without proof of coverage first. Digital certificate management transforms this once-cumbersome process into something handled in minutes.
From compliance perspective, public liability insurance satisfies client contract requirements, supports professional licensing needs, and serves as an HMRC-allowable expense reducing taxable profit.
Filing a Claim Step-by-Step
Report the incident immediately to your insurer, ideally within 24 hours. Provide basic facts about what happened, when, and where. Avoid admitting fault or discussing settlement amounts.
Complete the claim form thoroughly. Describe exactly what happened without speculation. Include witness contact information and take photos if safe. Gather relevant documents like contracts or maintenance records.
Cooperate with assessment. Respond promptly when adjusters request information. Facilitate property inspections or witness interviews quickly. Keep detailed communication records.
Settlement or defense is the final stage where coverage proves its worth. For valid claims, you receive payment minus policy excess. For disputed claims, insurers provide legal defense coverage.
Getting Your Certificate in Minutes
Your online portal provides 24/7 access to current and historical certificates. Download and share certificates instantly for last-minute client requests or tomorrow’s projects.
Customization options include adding additional insured parties, specific project information, and endorsements. Certificate holder information customizes for each situation.
Sharing and storage capabilities streamline operations. Email certificates directly, store copies in mobile wallet, or create secure sharing links for large projects.
Real-Life Claim Stories You Can Learn From

Learning from actual claim scenarios helps you understand coverage value and prevention methods:
Coffee Spill on Laptop:
Consultant accidentally knocked over coffee, destroying a £2,500 laptop and causing data recovery costs. Public liability covered the £3,200 total claim, minus £100 excess.
Wet Floor Injury:
Cleaning company failed to place warning signs after mopping. Visitor slipped and broke wrist, resulting in £8,500 in medical expenses and lost wages. Policy covered the full amount.
Paint Overspray Damage:
Decorator didn’t adequately protect nearby vehicles. Wind carried paint spray onto three cars, requiring £4,200 in professional correction. Coverage handled the claim.
Product Fault Incident:
Home baker’s cake caused food poisoning at wedding, affecting twelve guests. Medical expenses and disruption costs reached £15,000. Product liability coverage handled the claim.
Key Lessons:
- Simple precautions prevent many claims
- Proper procedures reduce risk
- Quick reporting improves outcomes
- Comprehensive coverage protects against unexpected scenarios
These stories demonstrate why simply business public liability insurance is essential protection.
Frequently Asked Questions about Public Liability
Is public liability insurance a legal requirement in the UK?
Here’s something that surprises many business owners: simply business public liability insurance isn’t actually a legal requirement in the UK. Unlike employers’ liability insurance, which you must have if you employ anyone, public liability coverage is technically optional from a legal standpoint.
But here’s the reality check – just because it’s not legally required doesn’t mean you can operate without it. Most clients won’t let you through their front door without proof of coverage. Venues require it before you can work on their premises. Many professional licenses and trade associations make it a condition of membership.
Think of it like wearing a seatbelt. It might not be legally required in every situation, but the financial risk of going without protection is simply too high. A single claim could wipe out years of hard work and savings.
Does it cover my employees?
This is where things get a bit confusing, and I see this misconception all the time. Public liability insurance doesn’t cover your employees – that’s what employers’ liability insurance is for. These are two completely different types of protection.
Public liability covers the “third parties” in your business world – your customers, clients, visitors, and random members of the public who might get hurt or have their property damaged because of your business activities. If a customer slips in your shop or you accidentally damage a client’s expensive vase, that’s public liability territory.
Your employees need their own protection through employers’ liability insurance, which is actually legally required if you have staff. The good news is that most insurers offer combined policies that include both coverages, making it simple to get complete protection without juggling multiple policies.
Can I get cover if I have a past conviction?
Having a criminal record doesn’t automatically slam the door on getting public liability insurance, but it does make things more complicated. The insurance world isn’t black and white – there’s usually a solution, even if it requires a bit more effort to find.
The key factors that insurers consider are what type of conviction you have, how long ago it happened, and whether it relates to your business activities. A single non-custodial conviction from years ago is very different from recent fraud charges, especially if you’re applying for professional indemnity coverage.
Some insurers will work with you directly, while others might require you to go through a specialist broker who understands these situations. The most important thing is complete honesty during the application process. Trying to hide a conviction is the fastest way to void your policy when you need it most.
At Strange Insurance Agency, we’ve helped clients with various backgrounds find appropriate coverage. Sometimes it takes a bit more work, but there’s usually a path forward. The key is working with experienced professionals who understand both the insurance market and your specific situation.
Conclusion
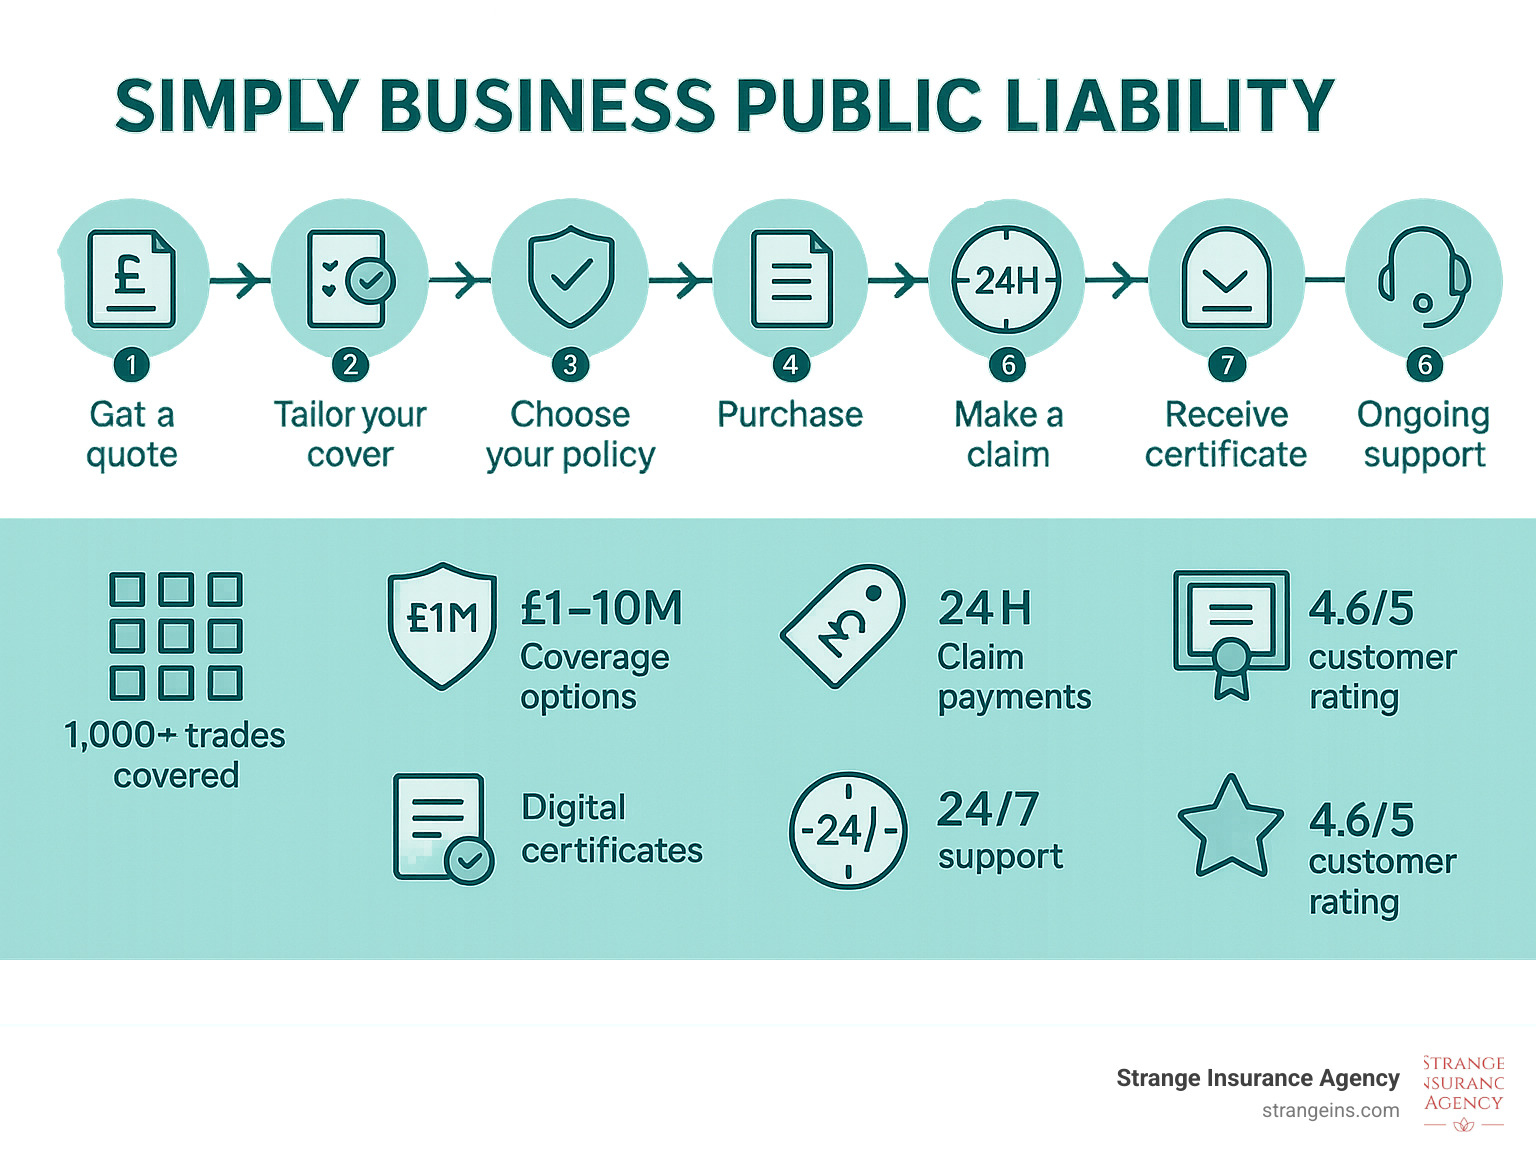
Running a business is challenging without worrying about liability claims that could destroy your work. Simply business public liability insurance offers peace of mind every business owner deserves, protecting from financial devastation a single accident could cause.
With coverage starting at £4.95 monthly and 80% of claims settled within 24 hours, this protection means focusing on business growth instead of what-if scenarios. The flexibility and accessibility – from £1-10 million coverage for 1,000+ trades – ensures protection fitting your needs and budget.
At Strange Insurance Agency, I understand unique challenges facing business owners. With 15+ years in treasury management and insurance, I’ve seen how right coverage makes or breaks businesses during incidents. Powered by Goosehead Insurance, we work with 30+ leading insurers finding coverage matching your risks and budget across Virginia, North Carolina, and nationwide.
Slip, trip, and fall accidents happen daily, and without coverage, single claims could force closure. With nearly a million satisfied customers and 4.6-star rating, quality public liability insurance proves its worth protecting family financial futures and ensuring businesses weather any storm.
Don’t let unexpected incidents undo years of work. Protection costs are minimal compared to potential devastation of operating without coverage. Contact Strange Insurance Agency today to explore options and secure deserved protection.
For comprehensive business protection covering all needs, explore our Business and Public Liability Insurance solutions designed to keep your business safe, compliant, and thriving.