
Why Understanding VA Home Benefits Is Critical for Your Investment
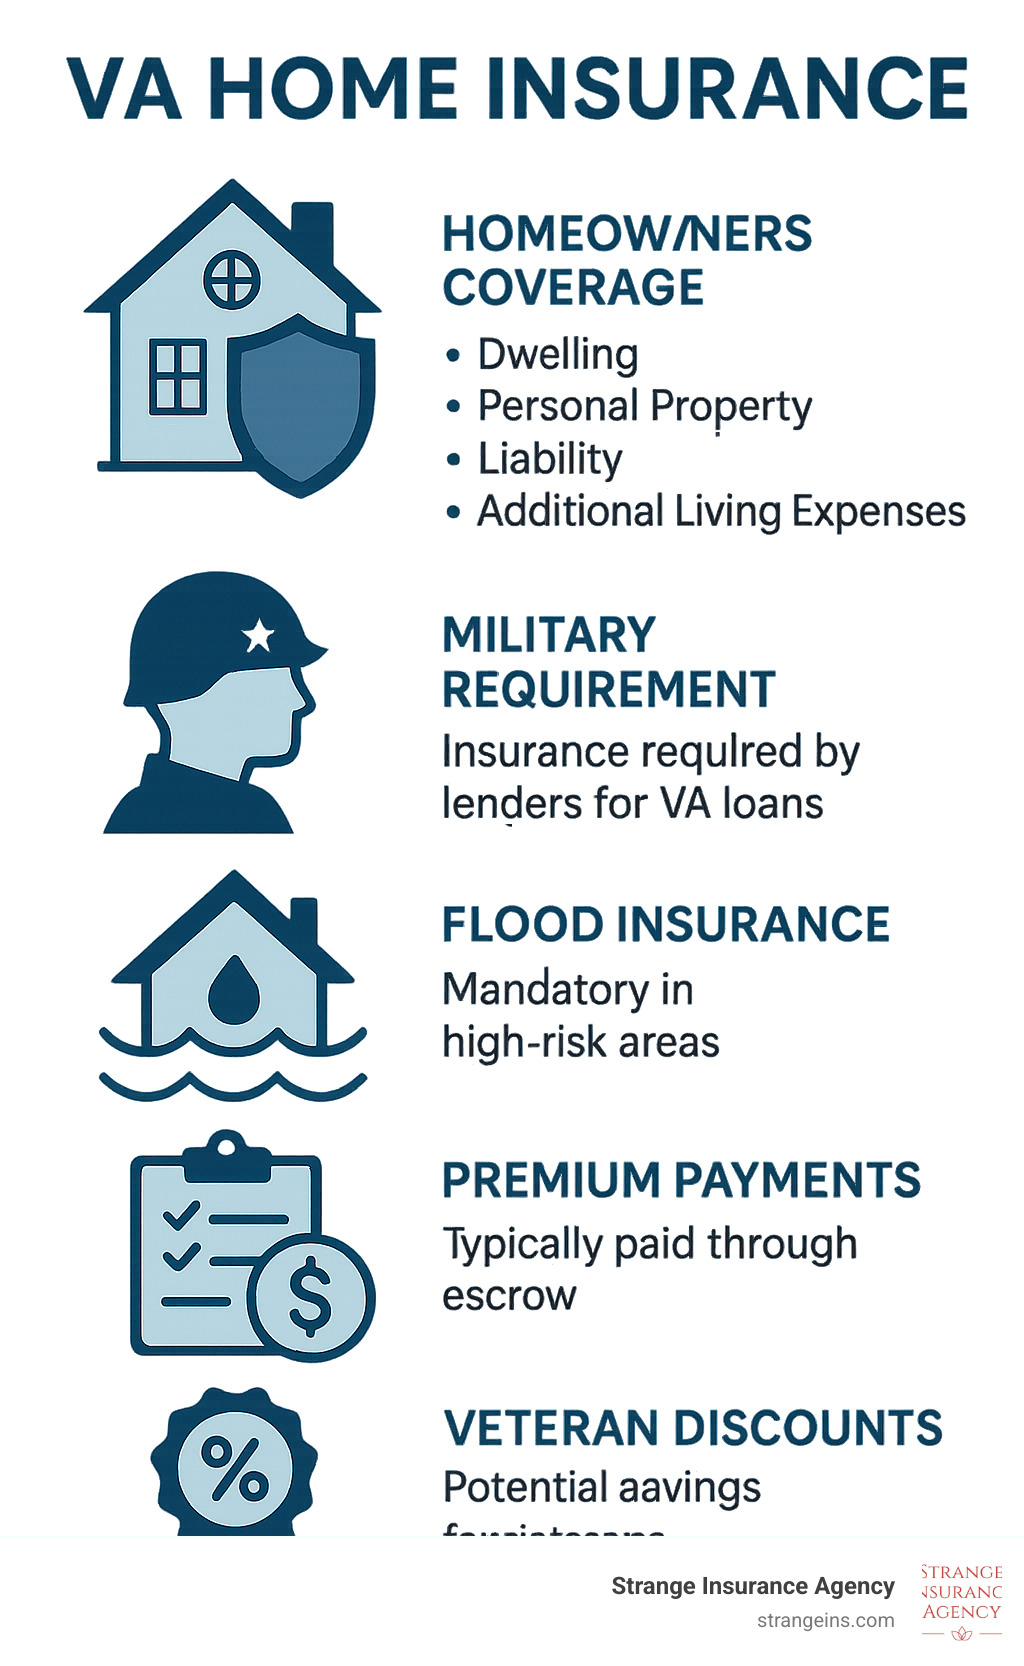
VA home insurance is a mandatory requirement when securing a VA loan, protecting both your investment and your lender’s interests. While the VA doesn’t provide insurance directly, they require you to maintain adequate homeowners insurance coverage for the life of your loan.
Quick Answer for VA Home Insurance:
- Required by lenders for all VA loans
- Covers dwelling, personal property, liability, and additional living expenses
- Must be in place before closing with 12 months of coverage paid
- Deductible generally cannot exceed 5% of dwelling coverage
- Flood insurance is required in Special Flood Hazard Areas
- Premiums are typically paid through an escrow account
The VA loan benefit offers incredible advantages like no down payment and no private mortgage insurance (PMI), but these come with the responsibility of maintaining proper homeowners insurance. This isn’t just a formality; it’s essential protection for your largest financial asset. Understanding the difference between homeowners insurance (for property damage) and Veterans’ Mortgage Life Insurance (VMLI, for certain disabled veterans) is key to making informed decisions.
As Christian Strange, I’ve spent over 15 years helping military families and veterans steer the unique insurance requirements that come with a VA loan. My experience in risk mitigation has shown me how vital the right coverage is for long-term financial stability.
Simple va home insurance word guide:
- Average Cost of Homeowners Insurance in Virginia
- Best Home Insurance Companies Virginia
- Home Insurance Richmond VA
Understanding the Homeowners Insurance Requirement for VA Loans
When you use a VA loan, a va home insurance policy isn’t just a good idea—it’s required. The VA doesn’t sell insurance, but it mandates that any home bought with a VA loan must be protected by hazard insurance for the entire loan term. This protects everyone involved: you, your lender, and the VA’s investment.
Your lender requires this protection because if a disaster destroys your property, the home’s value is lost. Homeowners insurance safeguards the physical structure, giving your lender confidence. Hazard insurance, which covers perils like fire, wind, and hail, is the core of your policy. However, a complete policy also covers your belongings, liability, and temporary housing costs.
A crucial detail for va home insurance is that your policy must be based on replacement cost, not market value. Replacement cost is what it would take to rebuild your home from the ground up, ensuring you have enough funds for repairs regardless of real estate market fluctuations.
These requirements remain the same when you refinance a VA loan. Your lender will verify your policy is up to date. For current pricing in our area, check out Home Insurance Rates in Virginia.
Standard Homeowners Insurance Coverage
A standard homeowners policy includes several key protections:
- Dwelling coverage: Protects the physical structure of your home (walls, roof, foundation). This is the primary concern for your lender.
- Personal property coverage: Covers your belongings (furniture, electronics, clothes) inside the home and often when you’re traveling.
- Other structures coverage: Protects detached structures like garages, sheds, and fences.
- Liability protection: Covers legal and medical costs if someone is injured on your property or if you damage someone else’s property. This can be a financial lifesaver.
- Additional Living Expenses (ALE): Pays for temporary housing and meals if your home becomes unlivable after a covered loss.
At Strange Insurance Agency, we help you build comprehensive Personal Insurance that covers these essentials.
Proving Coverage for Your VA Loan Closing
Before closing on your VA loan, you must prove you have active homeowners insurance. You’ll provide your lender with an insurance binder (temporary proof) or a declaration page (detailed summary). This document must list your lender as a payee or mortgagee, ensuring they receive claim payments for structural damage to protect their investment.
Lenders require a minimum of 12 months of coverage, with the policy starting on or before your closing date. Our team specializes in Homeowners Insurance Richmond VA requirements and can ensure your closing process is smooth.
How Premiums Are Paid with a VA Loan
With a VA loan, you’ll pay your first year’s premium at closing. After that, premiums are typically handled through an escrow account managed by your lender. Each month, a portion of your mortgage payment goes into this account to cover homeowners insurance and property taxes. Your lender pays these bills directly from the account on your behalf.
Because insurance premiums can change annually, your monthly mortgage payment can fluctuate. When your premium changes, your lender adjusts your escrow payment accordingly. We can help you understand How Much Does Virginia Home Insurance Cost? so you can budget with confidence.
Homeowners Insurance vs. Other Protections
When buying a home with a VA loan, you’ll encounter several types of protection. It’s vital to understand their different purposes. VA home insurance protects your physical property, while other products cover your mortgage payments or appliance repairs. Knowing the difference helps you protect your family and your largest investment.
Homeowners Insurance vs. Mortgage Insurance (PMI)
This is a common point of confusion. Homeowners insurance protects you and your property from damage and liability. If a tree falls on your roof or someone is injured on your property, your homeowners policy covers the costs.
Mortgage insurance (PMI) protects the lender if you default on your loan. You pay the premium, but the lender receives the benefit. Here’s a major advantage of VA loans: they never require PMI. The VA’s guarantee to the lender eliminates the need for this extra monthly cost, saving you thousands over the life of your loan. While you must have homeowners insurance, you’ll never pay for PMI.
Homeowners Insurance vs. Home Warranty
These two are also frequently confused. Homeowners insurance covers sudden, unexpected disasters like fires, theft, or storm damage. It’s required for your VA loan because these events can cause catastrophic financial loss.
A home warranty covers the repair or replacement of home systems and appliances due to normal wear and tear. Think of a furnace that stops working or a dishwasher that breaks down. Home warranties are optional and not required by your lender. If you’re interested in comprehensive coverage, we can help you explore Property and Liability Insurance options.
Veterans’ Mortgage Life Insurance (VMLI)
Veterans’ Mortgage Life Insurance (VMLI) is a specialized program for veterans with severe service-connected disabilities who have received a Specially Adapted Housing (SAH) grant. If the veteran passes away, VMLI can pay off the remaining mortgage balance (up to $200,000) directly to the lender. This ensures their family can keep the specially adapted home. Unlike homeowners insurance, which covers property damage, VMLI only addresses the mortgage debt. You can Learn about VMLI coverage directly from the VA.
| Feature | Homeowners Insurance | Mortgage Insurance (PMI) | Home Warranty | Veterans’ Mortgage Life Insurance (VMLI) |
|---|---|---|---|---|
| Purpose | Protects home, belongings, and liability from perils | Protects lender if borrower defaults on loan | Covers repairs/replacement of systems/appliances due to wear & tear | Pays off mortgage for disabled veterans’ families upon death |
| Required for VA Loan? | Yes (by lender) | No | No (Optional) | No (Optional, very specific eligibility) |
| Who it Protects | Homeowner, Lender | Lender | Homeowner | Veteran’s Family, Lender |
| Type of Coverage | Property damage, liability, additional living expenses | Financial guarantee for lender | Mechanical breakdown, appliance failure | Decreasing-term life insurance (mortgage protection) |
| Cost | Varies, paid monthly (often via escrow) | % of loan amount, paid monthly (not for VA loans) | Annual fee + service call fee | Monthly premium (for eligible disabled veterans) |
| What it Covers | Fire, theft, wind, hail, water damage (sudden) | Lender’s financial risk | HVAC, plumbing, electrical, appliances (wear & tear) | Mortgage balance |
| What it Doesn’t Cover | Wear & tear, floods, earthquakes (usually) | Property damage | Sudden perils, cosmetic issues | Property damage, general life insurance for beneficiaries |
Special Considerations for Your VA Home Insurance Policy

Military life presents unique challenges, and your va home insurance must account for them. Whether it’s deployment, living in a high-risk area, or buying a condo, your policy needs to fit your situation. We understand the needs of military families in Virginia and North Carolina and can help you steer these special considerations.
Coverage for Deployed Service Members
Deployment can create insurance complications. Most policies have occupancy clauses that may limit coverage if a home is vacant for over 30-60 days, as vacant homes are at higher risk for theft or unnoticed damage like burst pipes.
It is essential to notify your insurer about your deployment. We can help you add a vacant property endorsement or find a military-friendly policy that maintains your protection while you’re serving. This prevents a potential denial of a claim due to a vacancy clause.
High-Risk Areas: Flood and Natural Disaster Coverage
Virginia’s geography includes coastal areas prone to hurricanes and inland regions at risk of flooding. Your va home insurance must address these local risks.
Crucially, standard homeowners policies do not cover floods. If your home is in a Special Flood Hazard Area (SFHA), the VA will require you to buy a separate flood insurance policy. You can check your flood risk on FEMA’s website. Since many flood claims occur outside SFHAs, we often recommend this affordable protection even when it’s not required.
Hurricane and windstorm coverage is another key consideration. While standard policies usually include wind damage, coastal properties may have a separate, higher deductible for wind and hail. We specialize in Home and Flood Insurance Quotes and can ensure you have the right protection for your area.
Insurance for Condos and Other Property Types
VA loans cover more than just single-family homes. For a condominium, your Homeowners Association (HOA) has a master policy that covers the building’s exterior and common areas. You need your own HO-6 policy for “walls-in” coverage, which protects your interior, personal belongings, and provides liability protection.
We can review your HOA’s master policy to identify any gaps your individual Condo Insurance needs to fill. Manufactured homes also require specialized hazard insurance that accounts for their unique construction. We have experience with all property types and can guide you to the right Home Insurance Virginia policy for your needs.
How Veterans Can Find Affordable Coverage

As a veteran, you deserve to save money on your va home insurance without sacrificing protection. Here are smart strategies to lower your premiums:
- Shop for quotes: This is the most effective way to find affordable coverage. As an independent agency, we shop over 30 top-rated companies for you, saving you time and ensuring you get a great rate.
- Bundle your policies: Combining your home and auto insurance with the same carrier can lead to discounts of 10-25%.
- Install safety features: Monitored security systems, smoke detectors, and deadbolt locks reduce your home’s risk and can lower your premium.
- Raise your deductible: A higher deductible (e.g., $1,000 instead of $500) can significantly lower your annual premium. Just ensure it doesn’t exceed the VA’s 5% limit of your dwelling coverage.
- Maintain good credit: In most states, a healthy credit history can lead to lower insurance rates.
We can help you find the Cheapest Home Insurance in Virginia while ensuring you have excellent coverage.
Securing Discounts for Veterans
Many insurance companies offer military-specific discounts of 5-15% to honor your service. We know which of our partner carriers provide these benefits and will ensure you receive them. Bundling your policies and earning credits for home security systems can stack on top of these savings. A claims-free history also rewards you with loyalty discounts over time. We work with the Best Home Insurance Companies Virginia has to offer, and they value responsible homeowners.
Assistance for Disabled Veterans
If you’ve made home modifications for accessibility, your policy must reflect their value. Veterans who received Specially Adapted Housing (SAH) grants to build or modify their homes need to ensure their va home insurance covers the full replacement cost of these adaptations. You can learn more about Adapted Housing Grants from the VA.
We specialize in finding coverage for adapted homes. Common improvements like monitored security systems, hardwired smoke detectors, fire extinguishers, and smart home leak detectors not only make your home safer but can also earn you significant discounts.
The Claims Process: What to Do When Disaster Strikes
No one wants to imagine their home being damaged, but understanding the claims process for your va home insurance can make a chaotic situation manageable. Knowing the steps helps you focus on your family’s safety and recovery.
When disaster strikes, your first priority is safety. Once secure, the process is straightforward:
- Document the Damage: Take extensive photos and videos of all damage. The more evidence you have, the smoother the claim will be.
- Contact Your Insurer: Report the claim as soon as possible. Most companies have 24/7 hotlines.
- Begin the Process: Your insurer will send an adjuster to assess the damage and guide you through the repair and rebuilding process.
Since your lender is listed as a payee on your policy, they will be involved in larger payouts to ensure repairs are completed properly. This lender involvement protects both you and their investment.
What happens if a veteran’s home is damaged or destroyed?
After ensuring everyone’s safety, contacting your agent should be your first call. We can help you steer the process, understand your coverage, and prepare the necessary documentation.
When you file your claim, focus on the basic facts. You can add details later. If your home is uninhabitable, your Additional Living Expenses (ALE) coverage will help pay for temporary housing and meals, so keep all your receipts.
Working with the insurance adjuster is a collaborative process. Provide them with your documentation and walk them through the damage. Their job is to assess the loss fairly so you can begin repairs.
How does homeowners insurance facilitate repairs or rebuilding?
Your va home insurance policy is your financial partner in restoration. Because VA loans require replacement cost coverage, your policy pays to rebuild or repair your home to its pre-loss condition, without deducting for depreciation.
While you can choose your own contractors, your insurer may offer a list of pre-vetted professionals. Always check references and ensure any contractor is licensed and insured.
For major structural damage, claim payments may be sent to your lender. These lender-managed funds are released in stages as work is completed. This oversight ensures that repairs meet quality standards and your home’s value is restored, protecting both you and the lender. This is why you have va home insurance—to help you recover fully from unexpected events.
Frequently Asked Questions about VA Home Insurance
Navigating va home insurance brings up common questions. Here are the answers to the ones we hear most often.
What is the maximum deductible for homeowners insurance on a VA loan?
While the VA itself doesn’t set a specific dollar amount, most lenders enforce the “5 percent rule.” This means your policy’s deductible cannot be more than 5% of your dwelling coverage amount. For a home with $300,000 in dwelling coverage, the maximum deductible would be $15,000.
This rule protects both you and the lender by ensuring the deductible is not so high that you couldn’t afford to make necessary repairs after a disaster. We can help you select a deductible that lowers your premium while keeping your out-of-pocket risk manageable.
Does the VA offer homeowners insurance directly?
No, the VA does not sell homeowners insurance. The VA’s role is to guarantee a portion of your loan, which allows private lenders to offer favorable terms like no down payment and no PMI. However, the VA requires you to purchase a homeowners insurance policy from a private insurance company to protect the property that secures the loan.
That’s where we come in. As an independent agency, we shop the private market for you to find the best va home insurance coverage at a competitive price.
What happens if I can’t get insurance for a property?
This is a rare but serious issue. If a property is deemed uninsurable, you cannot get a VA loan for it. Lenders must notify the VA if insurance cannot be obtained, as continuous hazard insurance is a non-negotiable requirement of the loan program. An uninsurable home poses too great a risk to both you and the lender.
This is why it’s wise to get an insurance quote early in the home-buying process. We can quickly assess a property’s insurability. Often, a home that is declined by one carrier may be acceptable to another, especially a company that specializes in high-risk properties. Working with an experienced agency is key to finding a solution.
Conclusion
Your journey to homeownership with a VA loan is a significant achievement, and understanding va home insurance is essential to protecting that investment. This insurance is not just a requirement; it’s your shield against unexpected financial loss.
VA loans offer incredible benefits, but they come with the responsibility of maintaining proper insurance. We’ve covered the essential protections for your dwelling and liability, the unique needs of military families facing deployment or living in high-risk areas, and the specialized requirements for disabled veterans.
Finding affordable coverage is possible through smart shopping, bundling, and leveraging military discounts. At Strange Insurance Agency, we specialize in serving veterans and military families. We act as your concierge partner, shopping over 30 top-rated companies to find you comprehensive protection with military-specific savings.
Your home is the American dream you fought to protect. Let our expertise ensure it’s properly shielded from the unexpected, giving your family the peace of mind it deserves.
Get a comprehensive homeowners insurance quote today and let us help safeguard your future.