
Why Virginia Homeowners Need Reliable Protection
Virginia home insurance providers offer essential protection for your most valuable asset in a state that faces unique weather challenges and regulatory changes. With average costs 25% below the national average at $1,445 annually, Virginia homeowners have access to competitive coverage options from multiple carriers.
Top considerations when choosing Virginia home insurance providers:
- Coverage for state-specific risks – Flooding, hurricanes, winter storms
- Financial strength ratings – Ensure claims can be paid when needed
- Local expertise – Understanding Virginia’s insurance regulations and requirements
- Customer service quality – Claims handling and policy support
- Competitive pricing – Average premiums and available discounts
- Policy customization – Coverage that fits your specific property and needs
Virginia’s insurance landscape requires careful navigation. The state experiences an average of six severe weather disasters annually, with flooding being the most common threat despite only 3% of residents carrying flood insurance. Recent legislation effective July 2025 will also require new coverage for sewer backup and depreciation protection.
Your home represents decades of financial investment and irreplaceable memories. Whether you’re protecting a historic colonial in Richmond, a coastal property in Virginia Beach, or a rural estate in Shenandoah Valley, the right insurance partner makes all the difference.
As Christian Strange, I’ve spent over 15 years helping Virginia families steer complex insurance decisions and find comprehensive protection for their homes and assets. My experience working with virginia home insurance providers has shown me that the best coverage comes from understanding both state-specific risks and individual family needs.
Simple virginia home insurance providers word guide:
- average cost of homeowners insurance in virginia
- home insurance quotes in virginia
- home insurance Virginia
Understanding Virginia Home Insurance Costs
When you’re shopping for home protection in Virginia, the first question that naturally comes up is: “What’s this going to cost me?” The good news is that Virginia homeowners often get a pleasant surprise when they see the numbers.
The average homeowners insurance premium in Virginia sits at about $1,445 per year – that’s roughly 25% lower than what homeowners pay nationwide. While this gives you a solid starting point, your actual premium will depend on several factors that are unique to your specific situation and property.
Your home’s location plays the biggest role in determining your insurance costs. If you live near fire stations and hydrants, you’ll likely see lower rates. However, if your home sits in an area prone to flooding or hurricanes – especially along Virginia’s beautiful but risk-prone coastline – your premiums will reflect that increased exposure.
The age and construction materials of your home make a significant difference too. Newer homes built with modern materials and up-to-date building codes typically cost less to insure because they’re more resilient to damage. That charming older home might steal your heart, but it could also mean higher premiums since repairs tend to be more extensive and costly.
Your claims history follows you from property to property. Insurance companies look at both your personal claims record and any claims filed on your current home by previous owners. A clean history signals lower risk, while frequent claims suggest you might be more likely to file again.
Your credit score affects your premiums in Virginia, just like in most states. A strong credit score often translates to lower insurance costs because virginia home insurance providers view good credit as an indicator of responsibility and lower claim likelihood.
The deductible you choose creates a direct trade-off with your premium costs. Select a higher deductible, and you’ll pay less each year – but you’ll also pay more out of pocket if you need to file a claim. It’s about finding the right balance between monthly savings and potential future costs.
Understanding these cost factors helps you make smarter decisions about your coverage. We work with you to steer these details and find protection that fits your budget without leaving gaps in your coverage. For a deeper dive into Virginia’s insurance costs, check out our comprehensive guide on How Much is Virginias Home Owner Insurance.
Navigating Virginia’s Unique Risks and Coverage Needs
Living in Virginia means embracing everything from the rolling Blue Ridge Mountains to the beautiful Chesapeake Bay coastline. But this diverse geography also brings unique challenges that every homeowner should understand when choosing virginia home insurance providers.

The numbers tell a sobering story. From 1980 to 2024, Virginia experienced 116 confirmed natural disasters that each caused losses of $1 billion or more. That’s not just a statistic – it represents thousands of families whose lives were disrupted and homes damaged by forces beyond their control.
Flooding stands out as Virginia’s most persistent threat. Whether it’s flash floods from mountain runoff, river flooding along the Dan River region, or coastal storm surge, water finds a way. The tricky part? Your standard homeowners policy doesn’t cover flood damage. It’s a gap that catches many families off guard.
Hurricanes and tropical storms bring their own set of challenges to Virginia’s 132 miles of coastline. Hurricane Helene in September 2024 reminded us just how vulnerable we can be. These storms pack a triple punch: devastating winds, torrential rain, and dangerous storm surge. While your homeowners policy typically covers wind damage, that flood damage exclusion comes into play again with storm surge.
Winter storms might seem less dramatic, but they’ve caused 19 separate billion-dollar disasters in Virginia since 1980. Ice dams, burst pipes, and roofs collapsing under snow loads are real concerns. The good news is that most winter storm damage is covered by standard policies – as long as you’ve taken reasonable precautions like keeping your heat on when you’re away.
Tornadoes are less common in Virginia, but they do occur. Fortunately, the wind damage they cause is typically covered by standard homeowners policies. Landslides present another risk, particularly in mountainous regions, but standard policies usually exclude this type of earth movement damage.
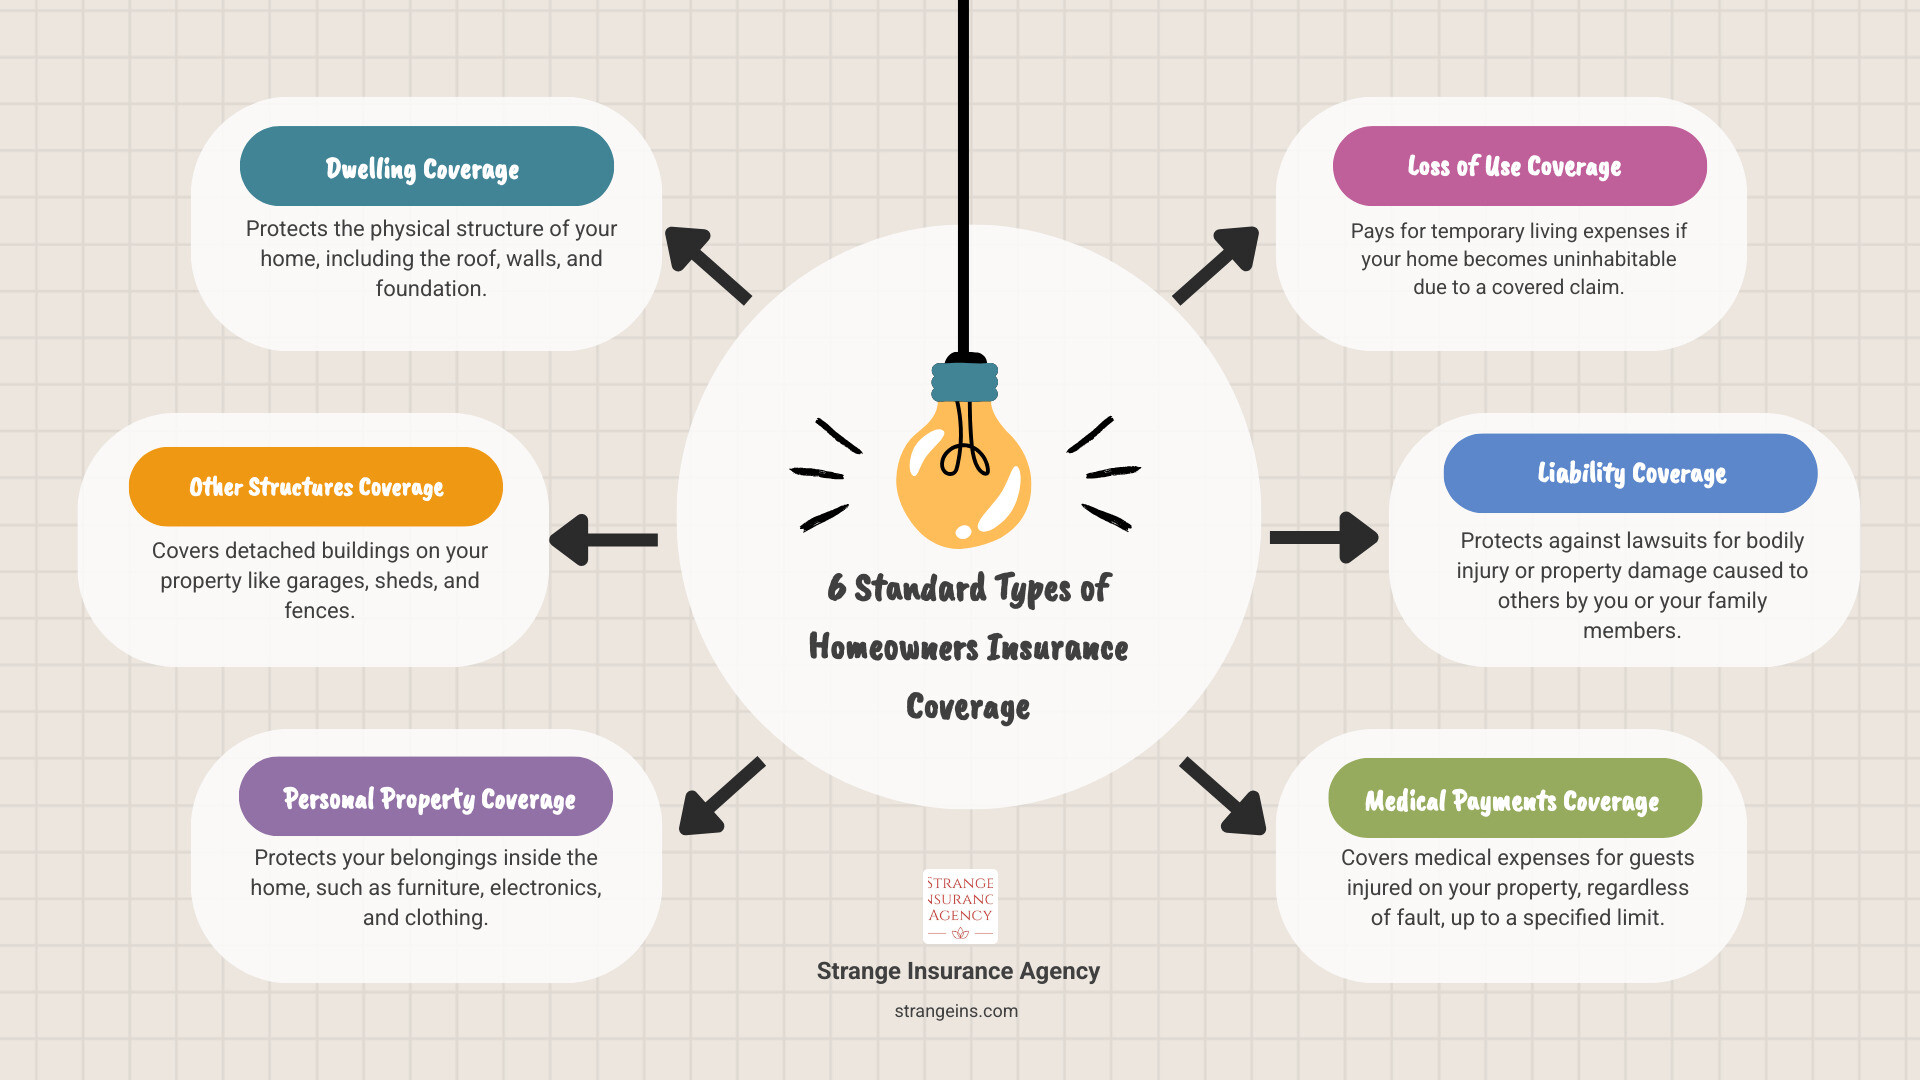
So what does this mean for your coverage? Your standard homeowners policy includes the six core protections: dwelling coverage for your home’s structure, other structures coverage for detached buildings, personal property coverage for your belongings, loss of use coverage for temporary living expenses, liability coverage for accidents, and medical payments coverage for guest injuries.
But Virginia’s unique risks call for additional considerations. Flood insurance is absolutely essential – and it’s purchased separately through the National Flood Insurance Program or private insurers. Only 3% of Virginians currently carry flood insurance, which is concerning given our state’s flood history.
A water backup endorsement protects against sewer and drain backup damage, which standard policies exclude. This coverage becomes especially valuable after heavy storms when municipal systems get overwhelmed. Windstorm coverage handles the high winds from hurricanes and severe storms, while replacement cost coverage ensures you can replace damaged belongings with new items rather than receiving their depreciated value.
The landscape is evolving too. New legislation effective July 2025 will require virginia home insurance providers to include sewer/drain backup coverage and address diminished value issues for repaired items. This means broader protection for Virginia homeowners, but it also highlights the importance of staying informed about your policy changes.
Understanding these risks and coverage options helps you make informed decisions about protecting your home. For more comprehensive information about property protection, visit our Property Insurance Virginia page.
Essential Coverage for Virginia’s Climate
Virginia’s climate demands specific attention to coverage details that might seem minor until you need them most.
Flood insurance deserves special emphasis because it’s both critically important and widely misunderstood. Standard homeowners insurance simply doesn’t cover flood damage – period. This distinction has caught countless Virginia families off guard when heavy rains cause unexpected flooding, even in areas not typically considered high-risk.
The Virginia’s Flood Risk Information System provides valuable insight into your property’s specific flood risk. Even if you’re not in a designated flood zone, consider this: just one inch of water in your home can cause $25,000 or more in damage. That’s a costly lesson to learn without proper coverage.
Windstorm and hurricane deductibles work differently than your standard deductible, especially in Virginia’s coastal counties. Instead of a flat dollar amount, you’ll often see a percentage-based deductible ranging from 1% to 5% of your home’s insured value. If your home is insured for $300,000 and you have a 2% hurricane deductible, you’d pay the first $6,000 out of pocket for hurricane-related wind damage.
These deductibles activate when a named hurricane or tropical storm impacts your area. Understanding when and how these apply prevents unpleasant surprises when you’re already dealing with storm damage.
Winter storm damage coverage has its own nuances. Damage from ice, snow, or sleet weight – like roof collapses or structural strain – is typically covered. However, issues like ice dams that cause water to back up under shingles, or frozen pipes that burst, require careful attention to policy language.
Most policies cover burst pipes if you’ve taken reasonable steps to prevent freezing, like maintaining heat in your home. It’s a good reminder that prevention is always your first line of defense, followed by proper insurance coverage.
Recent Legislative Updates Impacting Your Policy
Virginia’s insurance landscape continues evolving, and staying informed about legislative changes protects your interests as a homeowner.
The most significant recent change comes with new legislation effective July 1, 2025. This law requires virginia home insurance providers to include coverage for sewer/drain backup damage and address the decreased value of repaired damaged items. Both issues have historically been pain points for policyholders.
Sewer and drain backup coverage was previously an optional endorsement that many homeowners didn’t know they needed until facing a messy, expensive cleanup. The diminished value provision addresses the frustrating reality that repaired items often aren’t worth as much as they were before damage occurred.
These changes reflect growing recognition of common homeowner concerns and aim to provide more comprehensive protection. However, it’s crucial to review your policy carefully when it renews after July 2025 to understand exactly how this new coverage applies to your situation.
The implications for policyholders are positive – your standard homeowners policy will soon offer broader protection in these specific areas. But policy language matters, and understanding the details ensures you can make the most of these new protections.
We stay on top of these regulatory changes so we can help you steer them effectively. When legislation affects your coverage, we’ll make sure you understand what it means for your specific situation and help you adjust your policy accordingly.
How to Find the Right Virginia Home Insurance Solution
Finding the perfect home insurance can feel overwhelming when you’re faced with countless options and confusing policy language. That’s where having the right partner makes all the difference. At Strange Insurance Agency, we believe protecting your home shouldn’t be complicated or stressful.
When you work with us, we focus on what truly matters for your peace of mind. Financial strength is our starting point – we only work with insurers who have proven they can pay claims when disaster strikes. There’s nothing worse than finding your insurance company can’t cover your losses when you need them most.
We also prioritize customer service reputation because we know how important it is to have responsive, caring support during difficult times. The best policy in the world means nothing if you can’t get help when filing a claim. That’s why we carefully evaluate how each insurer treats their policyholders.
Claims satisfaction tells the real story of an insurance company. We look at how quickly and fairly claims are handled, because that’s when your coverage truly gets tested. Our goal is connecting you with virginia home insurance providers who have earned their reputation through consistent, fair claim settlements.

Our local expertise sets us apart. We understand Virginia’s unique weather patterns, from coastal hurricane risks to mountain winter storms. We know which coverage options work best for different areas of the state and can recommend the right protection for your specific location.
Most importantly, we believe in policy customization. Your 1950s colonial in Richmond has different needs than a new construction home in Virginia Beach. We work with multiple carriers to build coverage that fits your home, your budget, and your peace of mind. For more details on our comprehensive approach, visit our Insurance Solutions in Virginia page.
Comparing Your Options for a Virginia Home Insurance Solution
When shopping for homeowners insurance, you have several paths to choose from. Understanding these options helps you make the best decision for your situation.
Working with a local agency like Strange Insurance gives you access to multiple virginia home insurance providers through one relationship. You get personalized advice custom to Virginia’s specific risks, plus ongoing support throughout the life of your policy. We handle the comparison shopping, explain complex coverage options in plain English, and advocate for you during claims.
Purchasing directly online might seem convenient and potentially cheaper upfront. However, you’re largely on your own when it comes to understanding coverage gaps, state-specific requirements, or navigating claims. What looks like savings initially can become costly mistakes when you find coverage limitations after a loss.
Working through a single provider limits your options to one company’s products and pricing. While some insurers offer good coverage, you miss the opportunity to compare rates and coverage options across the market.
The choice often comes down to whether you value convenience over comprehensive protection and personalized service. We believe your home – likely your largest investment – deserves the thorough attention that comes with professional guidance and multiple coverage options.
What If You Can’t Find Coverage?
Sometimes finding standard homeowners insurance becomes challenging, especially for properties in high-risk areas. Coastal homes, properties with previous claims, or homes in flood-prone areas might face coverage limitations or higher premiums.
If you’re having trouble securing coverage through traditional channels, Virginia offers the Virginia FAIR Plan through the Virginia Property Insurance Association. This program provides basic property insurance for high-risk properties that can’t obtain coverage in the standard market.
The FAIR Plan isn’t ideal – coverage is limited and rates are typically higher than standard policies. But it serves as important protection when other options aren’t available. We can help you explore all possibilities before considering this last-resort option, and if needed, guide you through the FAIR Plan application process.
Even challenging insurance situations often have solutions. Our experience working with multiple virginia home insurance providers means we can often find coverage where others can’t. We’re committed to helping every Virginia homeowner find appropriate protection for their property.