
Why Small Business Owners Need Comprehensive Liability Protection
Comprehensive general liability insurance for small business is an older term for what is now called Commercial General Liability (CGL) insurance. It’s the foundational protection every business owner needs against costly third-party claims.
Quick Answer for Business Owners:
- What it is: CGL insurance protects against customer injuries, property damage, and advertising injury claims.
- Who needs it: Nearly every business, especially those with customer contact or a physical location.
- Average cost: $42-$85 per month for most small businesses.
- Key benefit: Covers legal defense costs and damages from lawsuits that could otherwise bankrupt your business.
Running a small business means facing daily risks. A customer could slip and fall, an employee could damage client property, or a marketing campaign could lead to a copyright lawsuit. These aren’t just possibilities; they are realities that can destroy unprepared businesses. Without proper coverage, even a frivolous lawsuit could force you to close your doors.
General liability insurance acts as your financial safety net, covering legal costs and damages so you can focus on growth. As Christian Strange of Strange Insurance Agency, I’ve seen how comprehensive general liability insurance for small business provides the peace of mind entrepreneurs need to take calculated risks and succeed.
Comprehensive general liability insurance for small business terms to remember:
- Virginia small business insurance
- accountants professional liability insurance
- directors & officers insurance
What Is General Liability Insurance and What Does It Cover?
General liability (GL) insurance is an essential shield for your business, protecting you from claims of injury or damage that your operations might cause to a third party. It’s a crucial safety net for the financial shockwaves of accidents and lawsuits that can arise during everyday business. For a deeper dive, explore our General Liability Insurance page.
So, what exactly does this powerful shield cover?

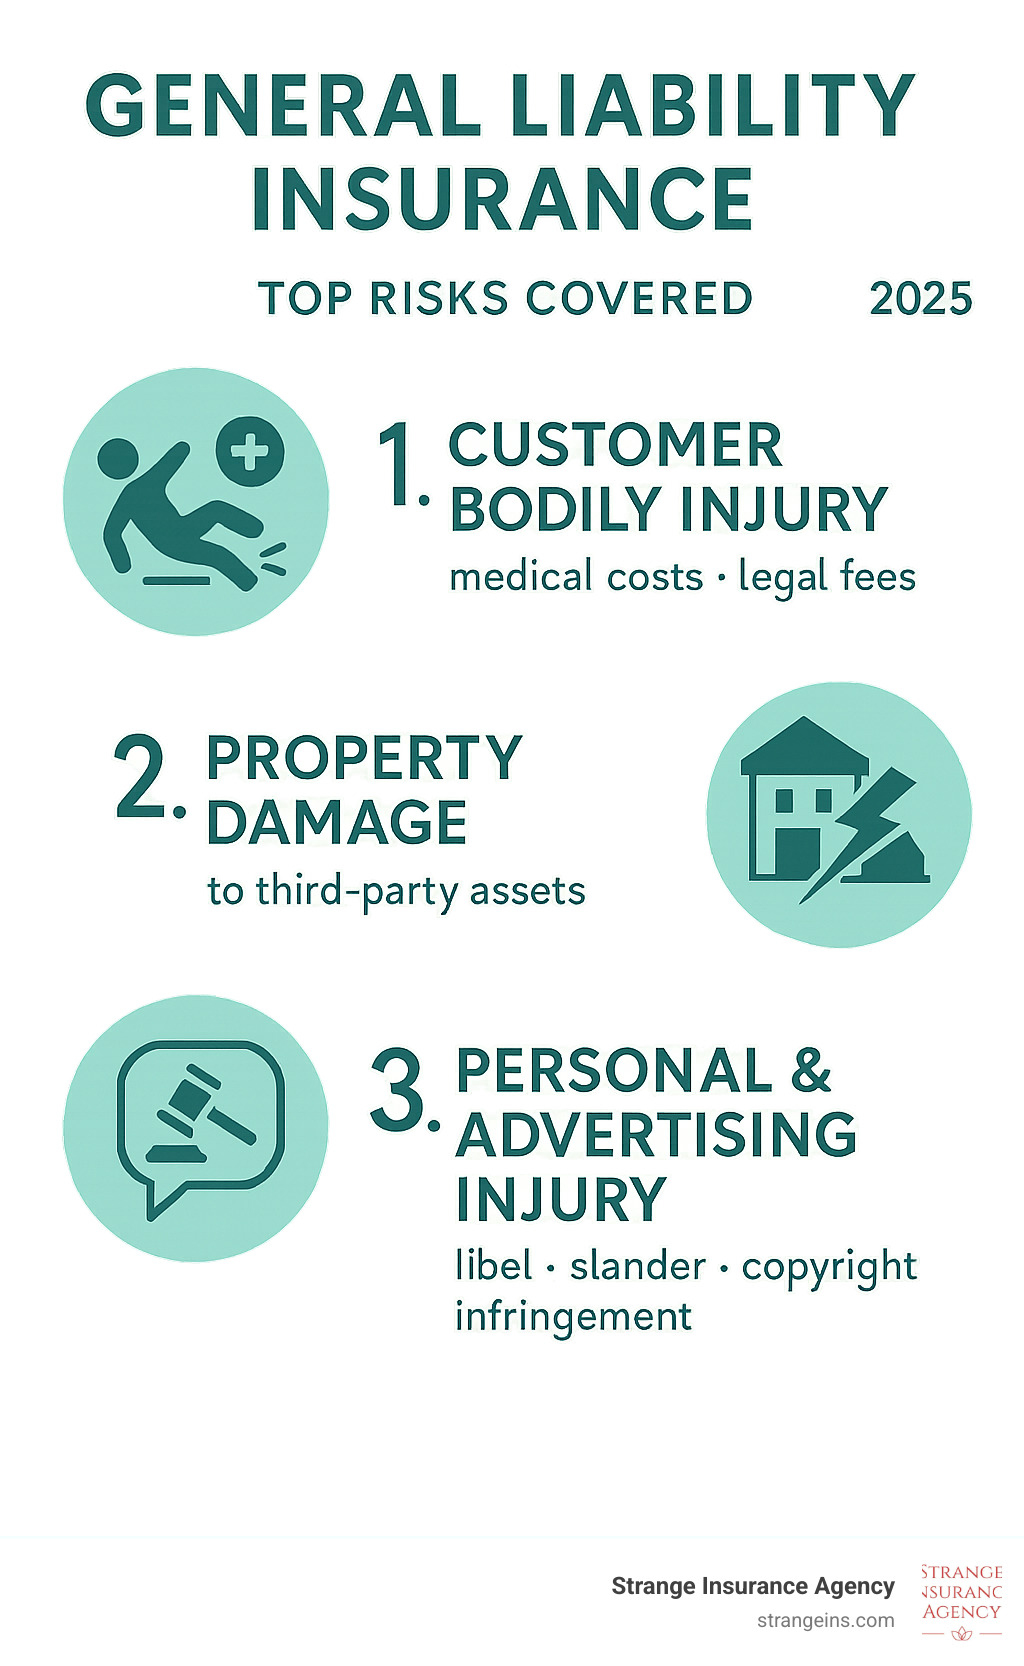
- Bodily Injury: If a customer or other third party is injured on your property or due to your operations (e.g., a “slip-and-fall”), this covers their medical bills and legal fees if you’re sued.
- Property Damage: If you or an employee accidentally damage someone else’s property, this covers the repair or replacement costs. This is vital for contractors, cleaners, or anyone working on client sites.
- Personal and Advertising Injury: This covers non-physical damages from claims like libel (written defamation), slander (spoken defamation), and copyright infringement in your advertising. If you unknowingly use a copyrighted image in an ad and get sued, this coverage helps with legal defense and settlements.
- Damage to Rented Premises: If you rent your business space, this covers costs if you accidentally cause damage, such as from a small fire, to the landlord’s property.
- Medical Payments: This provides for immediate medical care for someone injured on your premises, regardless of who is at fault, helping to resolve minor incidents before they become major lawsuits.
- Legal Defense Costs: One of the most valuable benefits. Your GL policy typically covers the high cost of defending your business in court, even for frivolous claims, often in addition to your policy’s liability limits.
This protection ensures your business is safeguarded from common accidents and legal battles. Learn more about what’s covered in our guide: What Does Business Liability Insurance Cover?.
What’s the Difference Between CGL and GL?
There is no functional difference. Comprehensive general liability insurance for small business is simply an older term for what is now called Commercial General Liability (CGL) or just general liability (GL) insurance.
The industry moved away from “comprehensive” to avoid the misconception that the policy covers every possible risk. No policy can do that. While GL coverage is incredibly broad and foundational, it has specific exclusions. So, if you’re looking for comprehensive general liability, a CGL or GL policy provides the robust, standard protection you need.
Why Your Small Business Needs General Liability Insurance
Comprehensive general liability insurance for small business isn’t just an expense; it’s a smart investment in your company’s future. Without it, a single accident or lawsuit could wipe out everything you’ve worked to build.

Here’s why it’s essential:
- Win Contracts: Many clients and project managers require a Certificate of Insurance (COI) before they’ll hire you. Proof of coverage shows you’re a responsible professional.
- Meet Landlord Requirements: Commercial leases almost always mandate that tenants carry general liability insurance to protect the landlord’s property investment.
- Gain Legal Protection: Even a frivolous lawsuit can cost tens of thousands in legal fees. A GL policy covers these defense costs, protecting your business from financial ruin.
- Achieve Peace of Mind: Knowing you’re protected from common risks lets you focus on serving customers and growing your business, not worrying about potential accidents.
For business owners in our region, securing Virginia Small Business Insurance with robust GL coverage is key to long-term stability.
Who Needs This Coverage?
Almost every business needs general liability insurance. If you interact with customers, work on client property, or have a physical location, you have liability risks. This includes:
- Contractors and tradespeople working on client property.
- Retail stores and restaurants with public foot traffic.
- Consultants and professional services at risk for advertising injury (e.g., libel, copyright infringement).
- Landscapers operating equipment on customer lawns.
- Any business with a physical location where clients visit.
Is General Liability Legally Required?
While not typically required by federal or state law, general liability insurance is often a practical necessity.
- Industry Mandates: Some states or cities require GL insurance for specific licensed professions, like certain construction trades.
- Contractual Obligations: This is the most common requirement. Clients, landlords, and lenders will often demand proof of insurance before signing a contract, lease, or loan.
- LLC Protection: An LLC protects your personal assets from business debts, but it doesn’t protect the business itself. If your LLC is sued, its assets are at risk. General liability insurance pays for covered claims, protecting your business’s financial health.
While not always legally mandated, GL insurance is essential for any business serious about success. If you’re ready to explore your options, you can get a quote today and see how affordable this crucial protection can be.
What GL Doesn’t Cover and Other Essential Policies
While comprehensive general liability insurance for small business is a powerful shield, it doesn’t cover everything. Understanding its limits is key to building a complete safety net. By combining GL with other key policies, like a Businessowners Policy (BOP) or Commercial Umbrella Insurance, you can ensure your business is ready for a wider range of challenges.
Common Exclusions in a General Liability Policy
General liability is designed for specific third-party risks, leaving other exposures to be covered by specialized policies. Key exclusions include:

- Employee Injuries: These are covered by Workers’ Compensation insurance, not GL.
- Professional Errors: Mistakes or negligence in your professional services require Professional Liability (E&O) insurance.
- Commercial Auto Accidents: Accidents involving business vehicles are covered by a Commercial Auto policy.
- Your Own Property Damage: GL covers damage to other people’s property. Your own building, equipment, and inventory are protected by Commercial Property insurance (often part of a BOP).
- Intentional Acts: GL is for accidents. It does not cover intentional harm, criminal behavior, or fraud.
- Data Breaches: A Cyber Liability policy is needed to cover costs related to cyberattacks and data breaches.
Other Insurance Your Small Business Might Need
To create a robust risk management plan, consider adding these policies:
- Workers’ Compensation Insurance: Legally required in most states if you have employees, it covers their on-the-job injuries. Learn more about General Liability Insurance and Workers’ Comp.
- Professional Liability (E&O): Essential for businesses that provide advice or services, protecting against claims of errors or bad advice that cause a client financial harm.
- Commercial Auto Insurance: Covers liability and damage related to vehicles used for business.
- Cyber Liability Insurance: Helps your business recover from a data breach or cyberattack by covering costs like customer notification, credit monitoring, and legal fees.
- Business Owner’s Policy (BOP): A great option for many small businesses, bundling GL, Commercial Property, and Business Interruption insurance into one convenient and affordable package.
- Commercial Umbrella Insurance: Provides an extra layer of liability protection that kicks in after your other policies (like GL or auto) have reached their limits, protecting you from catastrophic claims.
How to Secure Comprehensive General Liability Insurance for Your Small Business
Getting the right comprehensive general liability insurance for small business is simpler than you think. At Strange Insurance Agency, we streamline the process so you can focus on your business.
Working with an independent agency means we do the heavy lifting. We tap into our network of over 30 top-rated insurance companies to find you the best coverage at a competitive price. We handle the research and comparison shopping, presenting you with clear options explained in plain English. We’ll help you understand your coverage limits (e.g., “$1 million per occurrence / $2 million aggregate”) and can quickly generate a Certificate of Insurance (COI) when you need one for a contract or lease.
Ready to see how straightforward this can be? Start with our Liability Insurance Quotes today.
Factors That Influence Your Insurance Cost
Your premium is calculated based on your business’s unique risk profile. Understanding these factors helps you see what drives your cost.
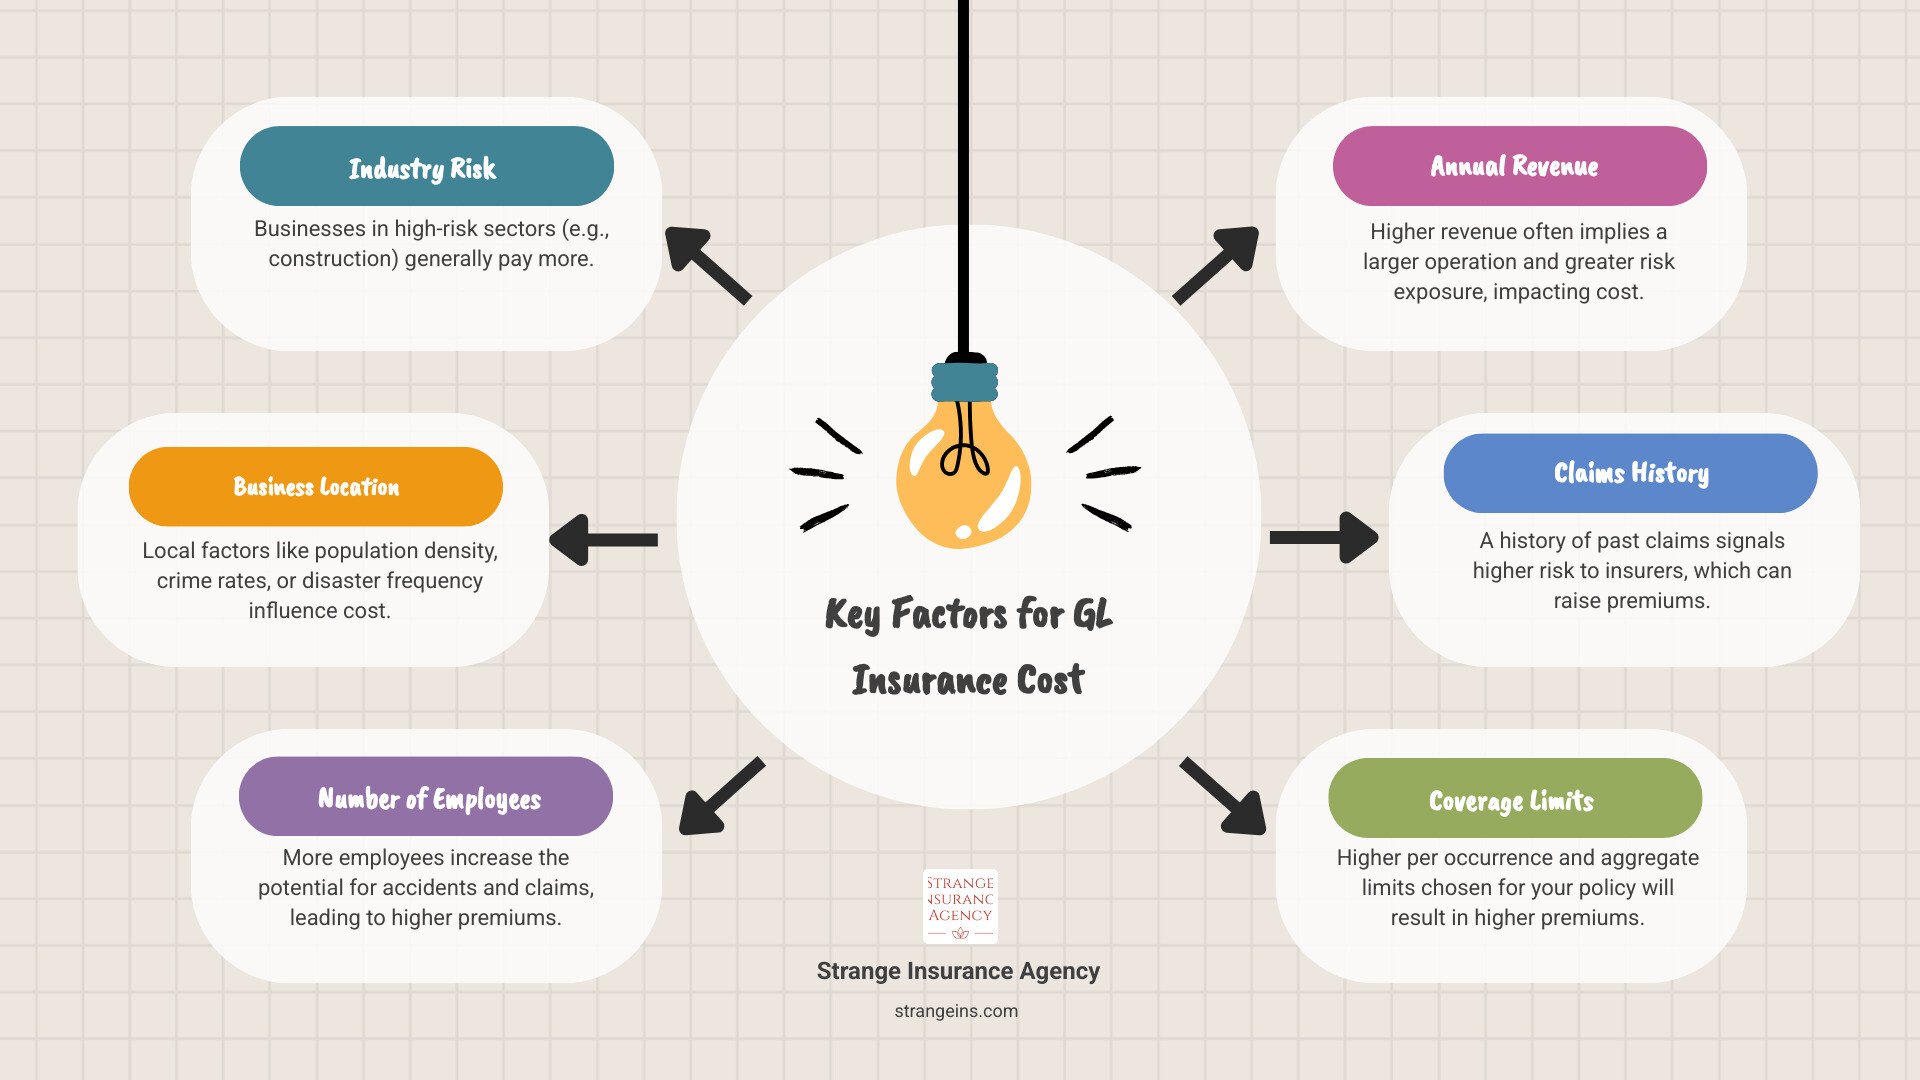
- Industry Risk: A roofing contractor has higher risk than a home-based bookkeeper, which is reflected in the premium.
- Business Location: Operating in a busy urban area can have different risks than a suburban office park. Local factors in Virginia, North Carolina, West Virginia, and Florida can influence pricing.
- Number of Employees & Revenue: These factors serve as indicators of your business’s size and activity level. More activity generally means more exposure.
- Claims History: A clean claims history helps keep rates down, similar to a good driving record.
- Coverage Limits & Deductible: Higher limits increase your premium, while a higher deductible can lower it. The standard $1M/$2M limit is a common requirement for contracts.
How much does comprehensive general liability insurance for small business cost?
The cost varies, but industry data provides helpful benchmarks. In 2024, many small businesses pay between $42 and $85 per month. Low-risk businesses might pay as little as $19 per month, while the average annual premium is often between $500 and $800.
These are just averages. Your actual cost will depend on the factors listed above. The only way to know for sure is to get a personalized quote.
Are premiums for comprehensive general liability insurance for small business tax-deductible?
Yes, in most cases. The IRS generally considers business insurance premiums to be ordinary and necessary business expenses. This means you can typically deduct them on your tax return, lowering your taxable income.
As tax laws can be complex, we always recommend consulting a qualified tax professional for advice specific to your situation. For general guidance, the IRS provides helpful information at Deducting Business Expenses.
Conclusion
Comprehensive general liability insurance for small business is not just an expense; it’s a critical investment in your company’s future. It’s the foundational shield that protects you from slip-and-fall accidents, property damage claims, and copyright lawsuits—the unexpected events that can derail an otherwise successful business.
This coverage provides the peace of mind to focus on what you do best: serving customers and growing your enterprise. It preserves your ability to operate, knowing that a single lawsuit won’t wipe out your hard-earned assets.
At Strange Insurance Agency, our mission is to simplify this process. As a concierge agency, we shop our network of over 30 top-rated carriers for you. We don’t offer one-size-fits-all solutions; we find the right policy for your unique risks and budget, whether you’re in Norfolk, VA, or across North Carolina, West Virginia, and Florida.
Proactive risk management is about being prepared. Don’t leave your business vulnerable. We handle the heavy lifting—from comparing quotes to explaining policy details—so you can get the protection you need without the hassle.
Ready to secure your business’s future? Contact us for your business insurance needs today. Let’s build the safety net your business deserves so you can grow with confidence.